CPF Changes 2026 Singapore: BRS, BHS, OW Ceiling and Contribution Rate Updates
Table of Contents
- What Changed in CPF 2026?
- 1. Ordinary Wage Ceiling Raised to S$8,000
- 2. New CPF Retirement Sums (BRS / FRS / ERS)
- 3. Basic Healthcare Sum Raised to S$79,000
- 4. Contribution Rate Changes for Workers Aged 55-65
- 5. CPF Interest Rates Q3 2026
- 6. What These Changes Mean for You
- 7. How to Maximise Your CPF in 2026
- Frequently Asked Questions
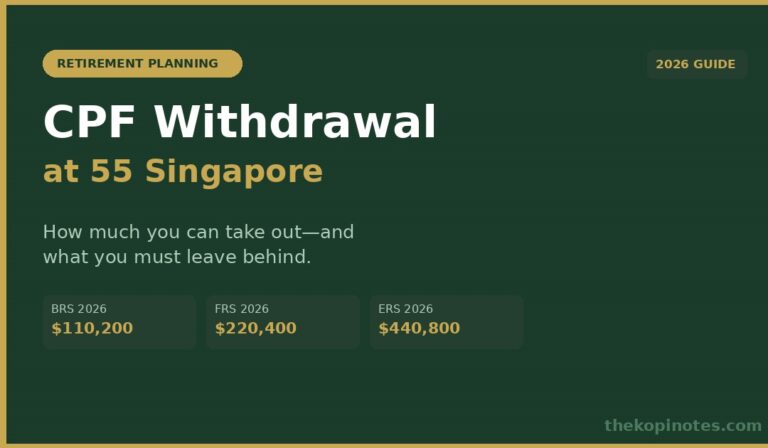
Singapore’s CPF scheme saw six notable changes in 2026. The Ordinary Wage (OW) ceiling rose from S$7,400 to S$8,000 per month from 1 January 2026, completing a four-year step-up plan. The Basic Retirement Sum (BRS) is now S$110,200, the Full Retirement Sum (FRS) is S$220,400, and the Enhanced Retirement Sum (ERS) stands at S$440,800 — fixed at 4x the BRS. The Basic Healthcare Sum (BHS) for members below 65 increased from S$75,500 to S$79,000. Workers aged 55 to 65 saw a 1.5 percentage point rise in contribution rates. The SMRA floor rate of 4% p.a. remains in place through 31 December 2026.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
- OW ceiling is now S$8,000 per month — more of your salary attracts CPF if you earn above S$7,400
- BRS is S$110,200 | FRS is S$220,400 | ERS is S$440,800 — check your RA if you turn 55 this year
- BHS hit S$79,000 — MediSave overflow goes to OA/SA once you hit this cap
- Workers aged 55-65 contribute more in 2026 — the final step-up is now done
- CPF SMRA floor rate of 4% locked in through end-2026
1. Ordinary Wage Ceiling Raised to S$8,000
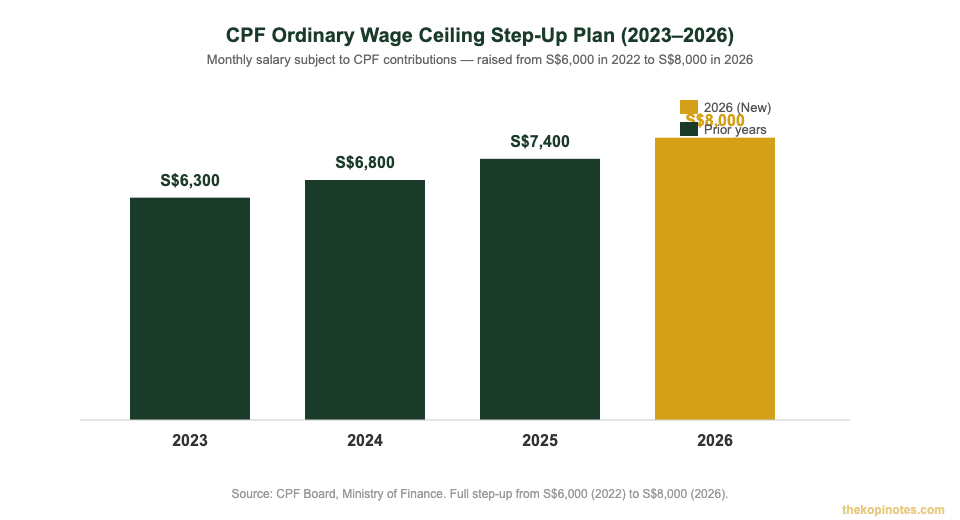
From 1 January 2026, the CPF Ordinary Wage (OW) ceiling rose to S$8,000 per month. This completes the phased increase that began in 2023, when the ceiling was first raised from S$6,000 to S$6,300.
The ceiling is the maximum monthly wage on which CPF contributions are calculated. If you earn S$10,000 a month, CPF is only computed on S$8,000. The extra S$2,000 goes entirely into your take-home pay with no CPF applied.
The CPF Annual Wage Supplement (AWS) ceiling stays at S$102,000. The total CPF contribution limit per year remains S$37,740 for employees. These two caps are unchanged from 2025.
For a Singapore Citizen or PR aged below 55 earning S$8,500 a month, the new ceiling means S$600 more of their salary attracts CPF. At the combined 37% rate, that is S$222 more in CPF contributions each month — split as S$120 employer and S$102 employee.
2. New CPF Retirement Sums for 2026 (BRS / FRS / ERS)
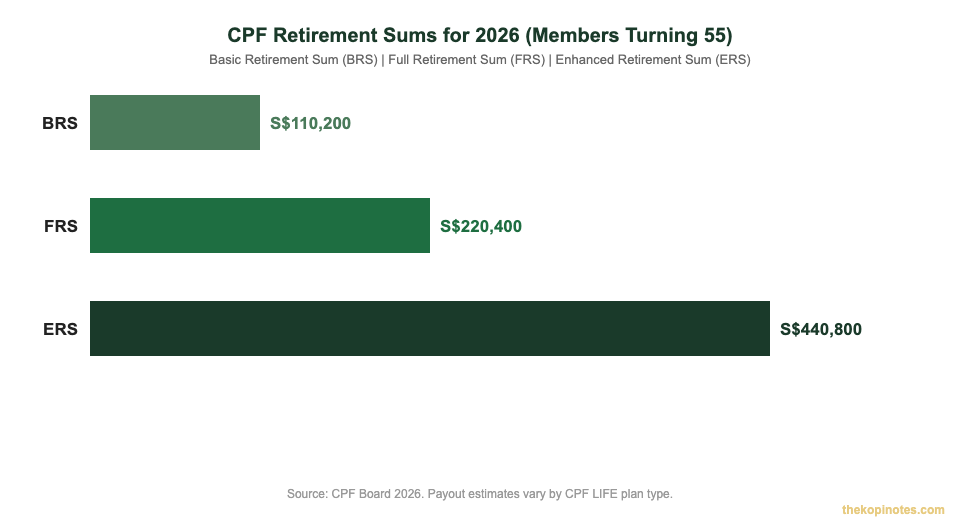
If you turn 55 in 2026, three retirement sum figures apply to you when CPF assesses your Retirement Account (RA). These sums are reviewed annually and increase by roughly 3.5% each year to account for inflation and rising living costs.
| Retirement Sum | 2026 Amount | Est. CPF LIFE Payout |
|---|---|---|
| Basic Retirement Sum (BRS) | S$110,200 | ~S$900-1,000/month |
| Full Retirement Sum (FRS) | S$220,400 | ~S$1,600-1,900/month |
| Enhanced Retirement Sum (ERS) | S$440,800 | ~S$3,300-3,900/month |
Source: CPF Board 2026. Payouts are estimates under the CPF LIFE Standard Plan. Actual amounts depend on plan type and age at payout start.
The ERS deserves special mention. From 2025 onwards, the ERS is set at 4x the BRS, up from the previous 3x cap. This means members can now top up more into their RA for higher CPF LIFE payouts in retirement.
You can use our Singapore retirement calculator to model how much CPF LIFE income you would receive based on your projected RA balance at 55.
3. Basic Healthcare Sum (BHS) Raised to S$79,000
For 2026, the Basic Healthcare Sum (BHS) is set at S$79,000 for CPF members below 65. This is up from S$75,500 in 2025 — an increase of S$3,500.
The BHS is the cap on your MediSave Account (MA). Once your MediSave balance reaches S$79,000, any further MediSave contributions are automatically transferred to your Ordinary Account (OA) or Special Account (SA).
For members who turn 65 in 2026, their BHS is fixed at S$79,000 for life. It will not change as they age further. Members aged 66 and above in 2026 retain their previously fixed BHS cohort amount and are not affected by this year’s update.
The BHS is adjusted yearly to keep pace with projected healthcare consumption. CPF Board targets the BHS to cover 10 to 12 months of hospitalisation expenses at B2 ward rates.
If you are close to the BHS cap, check your MediSave balance on the CPF website. Any new contributions that push you over S$79,000 will flow to your OA or SA, where they earn 2.5% or 4% respectively — still a solid return.
4. CPF Contribution Rate Changes for Workers Aged 55 to 65
Workers aged 55 to 65 saw a 1.5 percentage point increase in total CPF contribution rates in 2026. This is the final step of a multi-year plan to bring senior worker contribution rates closer to those of younger workers.
Higher contribution rates mean more savings flowing into CPF for this age group — building a larger RA balance before and after retirement age.
| Age Group | Employer | Employee | Total 2026 |
|---|---|---|---|
| Below 55 | 17% | 20% | 37% |
| 55 to 60 | 16% | 18% | 34% |
| 60 to 65 | 12.5% | 12.5% | 25% |
| 65 to 70 | 9% | 7.5% | 16.5% |
| Above 70 | 7.5% | 5% | 12.5% |
Source: CPF Board, effective 1 January 2026. Applies to Singapore Citizens and Permanent Residents.
For employees aged 55-60 earning S$8,000 a month, the combined employer-employee contribution is S$2,720 per month (34% of S$8,000). That is S$32,640 per year going into CPF — a meaningful boost to retirement savings in the final decade of most working careers.
5. CPF Interest Rates Q3 2026
CPF interest rates in Q3 2026 (July to September 2026) remain at their floor levels. The government extended the Special, MediSave, and Retirement Account (SMRA) floor rate of 4% p.a. through 31 December 2026.
| CPF Account | Base Rate (p.a.) | With Extra Interest Bonus |
|---|---|---|
| Ordinary Account (OA) | 2.5% | 3.5% on first S$20,000 (4.5% if aged 55+) |
| Special Account (SA) | 4.0% | Up to 5.0% within the S$60,000 combined cap |
| MediSave Account (MA) | 4.0% | Up to 5.0% within the S$60,000 combined cap |
| Retirement Account (RA) | 4.0% | Up to 6.0% for members aged 55+ on first S$30,000 |
Source: CPF Board, Q3 2026 (July-September 2026). SMRA floor rate of 4% extended to 31 December 2026.
The extra interest on the first S$60,000 of combined CPF balances earns an additional 1% per year. This cap is applied with priority to OA (up to S$20,000) first, then to the remaining accounts.
For members aged 55 and above, there is an additional 1% bonus on the first S$30,000 of combined balances. That means the first S$30,000 in your RA can earn up to 6% p.a. — risk-free and government-backed.
Use our CPF interest calculator to estimate exactly how much interest your CPF accounts will earn this year based on your balances.
6. What These CPF Changes Mean for You
The six 2026 changes pull in one direction: more money flowing into CPF and more of it protected for retirement and healthcare. Here is how each change affects you depending on your life stage.
If you earn above S$7,400/month: You now contribute CPF on more of your pay. Your take-home changes by a small amount but your CPF balance grows faster. Over a 10-year career, the extra S$600/month of CPF-eligible income adds a meaningful sum to your OA.
If you turn 55 this year: Your RA is assessed against BRS S$110,200, FRS S$220,400, and ERS S$440,800. If you hit the FRS, your property pledge (if any) is released. If you are below BRS, CPF will contact you about topping up before payout starts.
If your MediSave is close to S$75,500: Your cap has now moved to S$79,000. That is S$3,500 more room before overflow kicks in. If you are already above the old BHS, the difference has already been transferred to OA or SA.
If you are aged 55-65: Your contribution rates rose by 1.5 percentage points. This reduces your take-home pay slightly but accelerates your CPF LIFE payout build-up. The net effect is almost always positive for retirement adequacy.
If you rely on CPF SMRA interest: The 4% floor is confirmed through December 2026. You have full-year certainty on your SA and MA returns. Review your CPF investment strategy before touching your SA for CPFIS investments.
7. How to Maximise Your CPF in 2026
These policy changes create specific action points. Here are four things worth doing before the end of 2026.
Top up your SA or RA (cash top-up): The CPF Retirement Sum Topping-Up Scheme (RSTU) lets you top up your own or a family member’s SA or RA with cash. You get S$8,000 in tax relief per year for topping up your own account, and another S$8,000 for topping up a parent’s or spouse’s account. With the ERS now at S$440,800, there is more room than before for those who want to maximise CPF LIFE payouts.
Consider SRS contributions: The Supplementary Retirement Scheme (SRS) is separate from CPF but complements it. You contribute after-tax dollars, get an income tax deduction, and invest the funds. Read our SRS account Singapore guide to understand how SRS and CPF work together.
Check your MediSave balance: If you are close to S$79,000, any new contributions overflow to OA or SA. Plan accordingly — especially if you have flexible CPF contributions coming in.
Review your retirement income gap: Use our Singapore retirement calculator to see if your projected CPF LIFE payout covers your expected monthly expenses in retirement. If not, consider topping up your RA or investing with platforms like Endowus (referral code: 2V343) or Syfe (referral code: SRPRFFFCD) to build supplementary income streams.
Frequently Asked Questions
What is the Basic Retirement Sum (BRS) in 2026?
How does the OW ceiling increase to S$8,000 affect my CPF contributions?
What is the Basic Healthcare Sum (BHS) for 2026?
Did CPF contribution rates increase in 2026 for older workers?
What are CPF interest rates in Q3 2026?
What is the Enhanced Retirement Sum (ERS) in 2026?
How do CPF retirement sums compare between 2025 and 2026?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.