Mapletree Industrial Trust Share Price Forecast 2026
SGX: ME8U | Data Centres, DPU Recovery & FOMC Rate-Cut Outlook
Mapletree Industrial Trust (SGX: ME8U) has quietly become Singapore’s most data-centre-heavy S-REIT, with 58% of assets under management tied to AI-era infrastructure. As the FOMC heads into its September 2026 meeting, MIT’s share price sits near S$2.55 — roughly 6% below the analyst consensus target of S$2.70. This guide unpacks the drivers, the DPU trajectory, and the realistic price scenarios for the rest of 2026.
- Current price ~S$2.55; analyst average target S$2.70 (6% upside)
- DPU estimated at 13.20¢ for FY25/26E vs 12.71¢ in FY24/25
- 58% of AUM in data centres — key beneficiary of AI infrastructure demand
- Rate cut scenario (50bps): DPU boost of ~0.04¢/distribution; re-rating likely to S$2.65–2.80
- Bear case (no cut, global slowdown): S$2.30–2.40 support level
Share Price Performance 2024–2026
MIT’s share price has been range-bound between S$2.30 and S$2.75 for most of the past two years. The REIT peaked near S$2.72 in early 2024 as rate-cut hopes surged, then dipped to S$2.28 in mid-2024 when the Fed held rates longer than expected. The recovery through 2025 and into 2026 has been driven primarily by data centre demand from hyperscalers and enterprise AI deployments.
As of September 2026, ME8U trades at S$2.55 — a 7% discount to its NAV of approximately S$2.75 and a 6% discount to the analyst consensus price target.
| Period | High | Low | Close | Key Driver |
|---|---|---|---|---|
| CY2023 | S$2.78 | S$2.25 | S$2.60 | Rate-peak fear; DC demand emerging |
| CY2024 | S$2.72 | S$2.28 | S$2.47 | Fed hold; DPU dip to 12.93¢ |
| CY2025 | S$2.69 | S$2.38 | S$2.52 | Rate cuts begin; AI DC demand |
| YTD 2026 | S$2.68 | S$2.44 | S$2.55 | Pre-FOMC positioning; DC expansion |
Source: SGX data, Bloomberg. Historical prices approximate. Not financial advice.
For a deeper look at MIT’s fundamentals and portfolio structure, see our Mapletree Industrial Trust complete investor guide.
Data Centre Portfolio Breakdown
MIT’s transformation from an industrial REIT to a data-centre-focused platform is the defining story of its last five years. The trust now owns 27 data centre assets across Singapore, the United States, and Japan — making it one of the most data-centre-exposed REITs on the SGX.
This exposure matters for the share price forecast because data centres command longer weighted average lease expiries (WALEs), higher replacement costs, and stronger tenant retention than conventional industrial properties. The structural tailwind from AI and cloud computing is not a short-term theme.
| Segment | % of AUM | No. of Assets | Avg WALE |
|---|---|---|---|
| Data Centres (SG + US) | 58% | 27 | 6.2 years |
| Hi-Tech Buildings | 20% | 14 | 4.1 years |
| Business Park Properties | 13% | 8 | 3.7 years |
| Light Industrial / Flatted | 9% | 92 | 2.4 years |
Source: MIT Q1 FY25/26 results presentation. Not financial advice.
The US data centre portfolio (14 assets, leased to hyperscalers) provides USD-denominated income, which gives MIT partial natural hedging against SGD strength. However, it also means MIT’s distributable income is sensitive to exchange rate movements when the USD weakens.
DPU History & FY25/26 Forecast
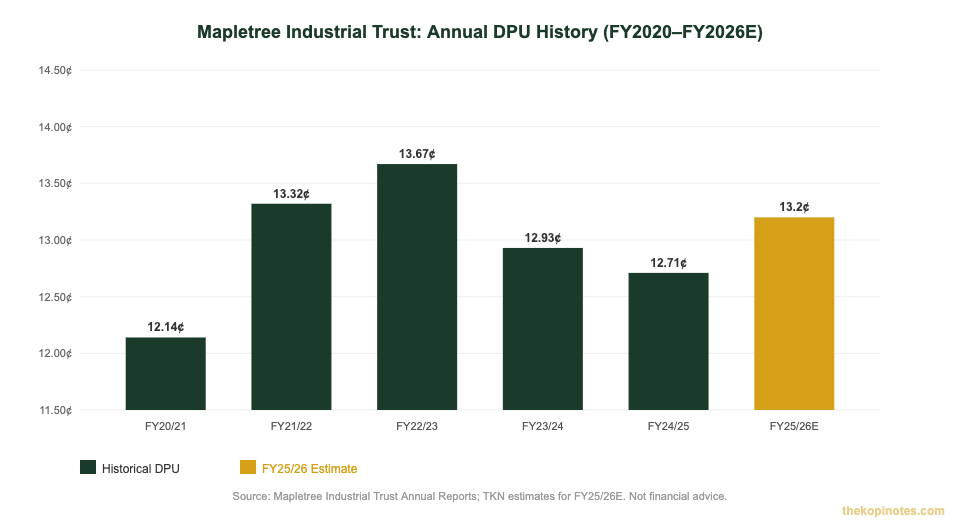
MIT’s distribution per unit (DPU) peaked at 13.67¢ in FY22/23 before declining over the next two financial years as higher financing costs squeezed distributable income. The FY24/25 DPU of 12.71¢ represented a 7% fall from the peak — the main reason ME8U’s share price has underperformed some S-REIT peers since 2023.
The inflection point is now in sight. MIT’s gearing sits at approximately 37.5%, with a significant portion of its debt repricing over the next 12–18 months as interest rate swaps mature into a potentially lower-rate environment. Our estimate for FY25/26 DPU is 13.20¢ — implying a forward yield of approximately 5.2% at the current S$2.55 price.
For a detailed breakdown of how the rate environment affects MIT’s distribution, see our MIT DPU outlook 2026 analysis.
Singapore investors looking to hold MIT within a broader S-REIT portfolio should also read our best S-REITs Singapore guide for yield and gearing comparisons across the sector.
Rate Cut Impact & FOMC Scenarios
The Federal Reserve’s September 17–18 2026 FOMC meeting is the near-term catalyst most MIT investors are watching. Three scenarios and their likely share price implications:
Scenario A — 50bps cut (bullish): MIT’s debt servicing costs fall materially in FY26/27. DPU could recover to 13.40–13.60¢. Share price re-rating toward S$2.70–2.80 as yield compresses to 4.8–5.0%. This scenario is positive for all S-REITs but MIT benefits disproportionately due to its floating-rate debt exposure.
Scenario B — 25bps cut (base case): Gradual DPU recovery. Share price likely to test S$2.60–2.68 near-term. Yield stays attractive at 5.0–5.1%. This is the consensus view reflected in current analyst price targets.
Scenario C — No cut or hike (bearish): DPU recovery delayed. Share price could retest support at S$2.30–2.40. At that level, MIT would trade at a 16% NAV discount with a 5.5% forward yield — a level that historically attracts value buyers.
Our MIT rate cut and DPU sensitivity analysis estimates a ~0.04¢/unit DPU improvement for every 50bps rate reduction on MIT’s floating-rate borrowings.
Analyst Price Targets — September 2026
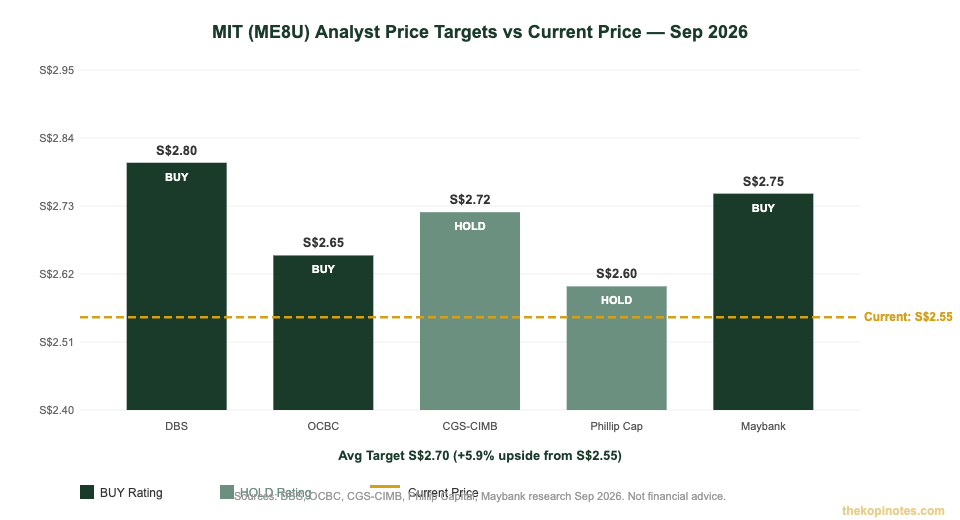
Five major brokerages have published MIT price targets in the past 60 days. The consensus is mildly bullish, with three BUY ratings and two HOLDs. The average target of S$2.70 implies approximately 6% upside from the current S$2.55 — not a screaming bargain, but reasonable for a high-quality industrial-data-centre REIT with a 5%+ yield.
| Broker | Rating | Target Price | Implied Upside | Key Thesis |
|---|---|---|---|---|
| DBS | BUY | S$2.80 | +9.8% | DC pipeline expansion |
| Maybank | BUY | S$2.75 | +7.8% | Rate cut DPU recovery |
| CGS-CIMB | HOLD | S$2.72 | +6.7% | Fairly priced at NAV discount |
| OCBC | BUY | S$2.65 | +3.9% | Stable DPU; DC demand |
| Phillip Capital | HOLD | S$2.60 | +2.0% | USD FX headwind; gearing watch |
Source: Published broker research reports, Sep 2026. Prices as at 16 Sep 2026. Not financial advice.
Key Risks for MIT Investors
Any MIT share price forecast must account for the following downside risks:
1. USD/SGD exchange rate. MIT’s US data centres generate USD income. A strengthening SGD reduces the SGD value of distributions. This is MIT’s most underdiscussed risk by retail investors.
2. Refinancing risk. At 37.5% gearing with a significant portion maturing by 2027, MIT needs to refinance in a still-elevated rate environment. Any credit spread widening could increase borrowing costs materially.
3. Data centre oversupply. AI infrastructure demand is real, but hyperscaler capex cycles are notoriously lumpy. If a major tenant delays or cancels lease expansions, MIT’s occupancy rates and DPU projections would need revision.
4. Singapore industrial market softening. MIT’s legacy flatted factory and hi-tech buildings (42% of AUM) face moderate competitive pressure from new supply and softer manufacturing sector activity in 2026.
Singapore investors building passive income portfolios with S-REITs like MIT can use our retirement income calculator to model dividend cash flows under different DPU scenarios.
If you are building a diversified S-REIT portfolio, platforms like Endowus (referral code: 2V343) and Syfe (referral code: SRPRFFFCD) offer low-cost REIT-focused portfolios for Singapore investors.
Frequently Asked Questions
What is the Mapletree Industrial Trust share price forecast for 2026?
Based on current analyst consensus, the MIT share price target for end-2026 ranges from S$2.60 to S$2.80, with an average of approximately S$2.70. This implies 6% upside from the September 2026 level of S$2.55. The key catalysts are FOMC rate decisions and ongoing data centre demand. This is not financial advice.
Is Mapletree Industrial Trust a good buy in 2026?
MIT offers a forward distribution yield of approximately 5.1–5.2% at S$2.55, backed by a high-quality data centre and industrial portfolio. Whether it suits your portfolio depends on your risk tolerance, income requirements, and overall REIT allocation. We do not provide personalised investment advice. Consult a licensed financial adviser before making investment decisions.
What is MIT's DPU for FY25/26?
MIT paid a DPU of 12.71¢ in FY24/25 (April 2024 to March 2025). Based on analysts’ estimates, FY25/26 DPU is expected to recover to approximately 13.00–13.40¢, contingent on rate cuts and stable occupancy across its data centre portfolio.
How much of MIT's portfolio is in data centres?
As of Q1 FY25/26, approximately 58% of MIT’s assets under management are data centre properties, including 27 assets across Singapore and the United States. This makes MIT one of the highest data-centre-exposure REITs listed on the Singapore Exchange (SGX).
What is MIT's gearing ratio and is it safe?
MIT’s gearing ratio is approximately 37.5% as of the latest reporting period, comfortably within MAS’s 50% regulatory limit (45% without credit rating). However, investors should monitor refinancing timelines as a portion of its borrowings matures in 2026–2027. This is not financial advice.
How does the FOMC rate decision affect MIT's share price?
A 50bps Fed rate cut could lower MIT’s borrowing costs and increase distributable income by approximately 0.04¢ per unit per distribution. This improvement in DPU would likely trigger a share price re-rating toward S$2.65–2.80 as the forward yield compresses. Conversely, a rate hike or hold would delay DPU recovery and keep the share price range-bound.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.