Endowment Plan Cash Value Singapore 2026: What It Is & How to Use It
Your complete guide to guaranteed savings, policy loans, partial withdrawals and smart surrender decisionsAn endowment plan’s cash value is the amount your policy has accumulated at any point before maturity — made up of a guaranteed portion and, on participating plans, non-guaranteed bonuses. In Singapore, most plans start with zero cash value in years 1–2, building to roughly 60–90% of premiums paid by the midpoint of the policy term. You can access it via a policy loan, partial withdrawal, or full surrender — each with different implications for your coverage and future returns.
Not financial advice. All figures are illustrative examples for educational reference only. Data verified as at 4 November 2026.
📋 Table of Contents
Jump to a Section
What Is Cash Value in an Endowment Plan?
Cash value is the accumulated savings component of your endowment plan — the amount the insurer holds on your behalf at any given point during the policy term. It is distinct from the death benefit (the sum assured paid to your beneficiaries if you pass away) and from the maturity benefit (the full payout when the policy ends as scheduled).
Think of cash value as the “net worth” of your policy at a snapshot in time. If you needed to access your policy’s funds today, cash value is the pool you would be drawing from — subject to any applicable surrender charges or loan interest.
For participating (par) endowment plans, cash value has two layers:
- Guaranteed cash value — fixed amounts stated in your policy illustration, growing predictably year by year regardless of insurer performance
- Non-guaranteed reversionary bonuses — annual bonuses declared by the insurer’s par fund, added to the guaranteed base once declared. Once declared, they cannot be taken back; however, future undeclared bonuses are not guaranteed and are forfeited if you surrender early
For non-participating (non-par) endowment plans — common in short-term 1–3 year plans — cash value is purely the guaranteed accumulation with no bonus component.
Par vs Non-Par: How Cash Value Differs
| Feature | Participating (Par) Plan | Non-Participating (Non-Par) Plan |
|---|---|---|
| Guaranteed cash value? | ✅ Yes | ✅ Yes |
| Annual reversionary bonuses? | ✅ Non-guaranteed | ❌ No |
| Terminal bonus at maturity? | ✅ Non-guaranteed | ❌ No |
| Return certainty | Moderate (bonus uncertainty) | High (fully guaranteed) |
| Typical policy term | 10–25 years | 1–5 years |
Source: MAS-regulated product structures; compiled by The Kopi Notes, November 2026.
Cash Value vs Surrender Value vs Maturity Value: Key Differences
These three terms appear in every endowment plan illustration, and many policyholders use them interchangeably — incorrectly. Here is the precise distinction:
- Cash value — The total accumulated amount in your policy at a given point: guaranteed base plus any bonuses declared to date. This is the theoretical maximum you can access.
- Surrender value — The actual cash you receive if you cancel the policy before maturity. This equals cash value minus surrender charges (highest in years 1–5, tapering to zero near maturity on most plans).
- Maturity value — The full projected payout when the policy term ends naturally, including the terminal bonus declared at the end of the policy. For par plans, this is the highest projected value and includes non-guaranteed bonuses accumulated over the full term.
The relationship in simple terms: Surrender Value ≤ Cash Value ≤ Maturity Value.
Surrender charges are why early exit is so costly — insurers recover upfront distribution costs, underwriting expenses, and commission over the policy term. These charges are heaviest in the first five years and progressively reduce. By Year 10–12 on most 20-year plans, surrender charges are typically negligible. See our Surrender Value of Insurance Singapore guide for the full breakdown.
How Cash Value Builds Up Year by Year (Singapore Context)
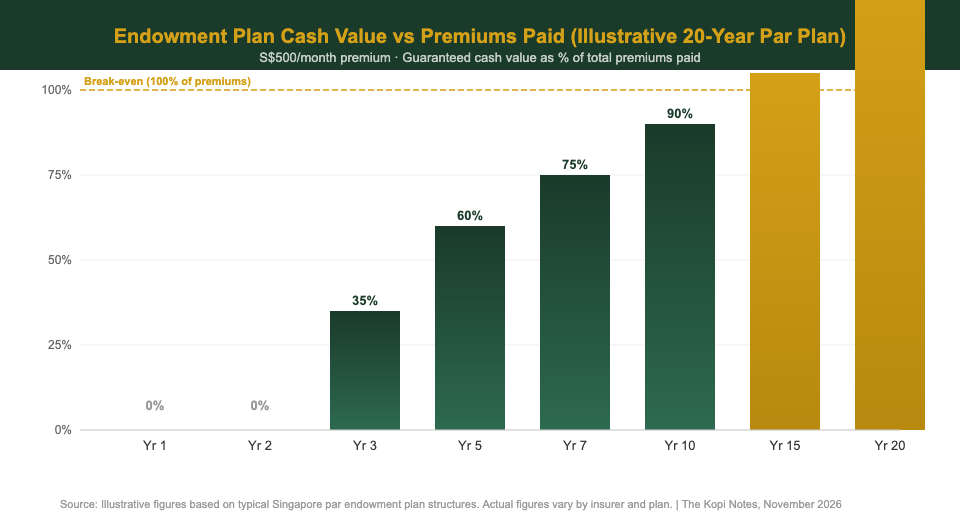
The cash value schedule varies by insurer, plan type, and premium amount. The table below illustrates a typical 20-year regular-premium par endowment plan at S$500/month (S$6,000/year). These are illustrative figures — your personalised policy illustration will show the exact guaranteed amounts.
| Year | Total Premiums Paid | Guaranteed Cash Value | % of Premiums | Approx. Surrender Value |
|---|---|---|---|---|
| Year 1 | S$6,000 | S$0 | 0% | S$0 |
| Year 2 | S$12,000 | S$0 | 0% | S$0 |
| Year 3 | S$18,000 | S$6,300 | 35% | S$4,500 |
| Year 5 | S$30,000 | S$18,000 | 60% | S$15,000 |
| Year 7 | S$42,000 | S$31,500 | 75% | S$29,400 |
| Year 10 | S$60,000 | S$54,000 | 90% | S$52,200 |
| Year 15 | S$90,000 | S$94,500 | 105% | S$93,600 |
| Year 20 (Maturity) | S$120,000 | S$158,400 + terminal bonus | 132%+ | S$158,400+ (no charges) |
Source: Illustrative figures based on typical Singapore participating endowment plan structures. Actual cash values vary by insurer, plan, and premium. Always verify against your personalised policy illustration. The Kopi Notes, November 2026.
Key insight: The guaranteed cash value on most 20-year par plans reaches 100% of premiums paid around Year 13–15. Non-guaranteed reversionary bonuses — if the par fund performs near historical averages — can pull the effective break-even forward to Year 10–12. The terminal bonus paid at maturity is typically the largest single return component but carries the highest uncertainty.
3 Ways to Access Your Endowment Plan Cash Value Before Maturity
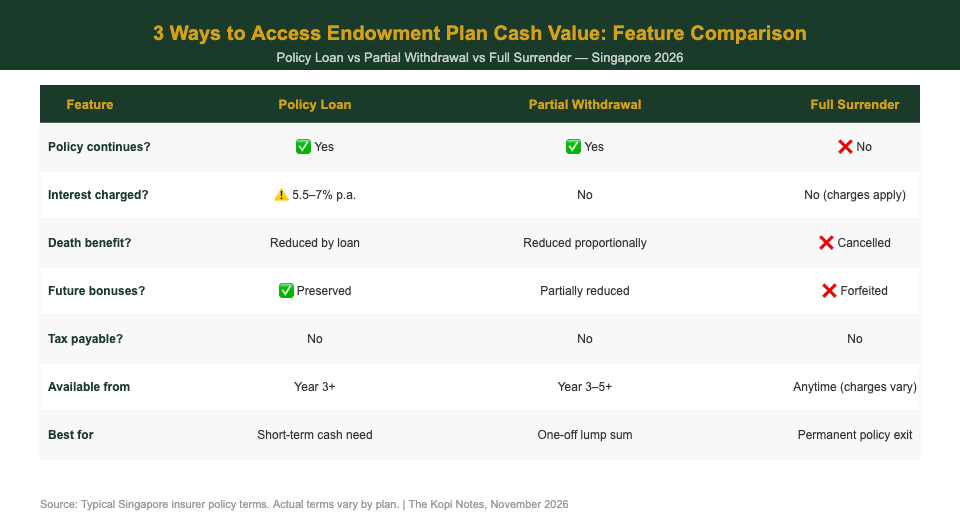
Once your policy has accumulated sufficient cash value (typically from Year 3–5 onwards), you have three ways to access funds without waiting until maturity. Each carries different implications for your policy, death benefit, and long-term returns.
Option 1: Policy Loan — Borrow Against Your Cash Value
A policy loan lets you borrow up to 80–92% of your policy’s current cash value (depending on the insurer) while keeping the policy fully active. The death benefit and future bonus accumulation continue — the outstanding loan is simply deducted from any future payout.
Interest rate: Most Singapore insurers charge 5.5% to 7.0% p.a. on policy loans, compounding annually against the policy’s cash value if not repaid.
Worked example: If your policy has S$50,000 in cash value and you borrow S$30,000 at 6.5% p.a., the annual interest charge is S$1,950. If unpaid after five years, the outstanding balance grows to approximately S$41,100 — significantly eroding your maturity payout.
Best for: Short-term cash needs where you expect to repay within 1–3 years. The policy continues accumulating and the death benefit remains largely intact. See our full Endowment Plan Policy Loan Singapore guide for worked repayment schedules.
Option 2: Partial Withdrawal — Access Funds Without Cancelling
Many Singapore endowment plans allow partial cash withdrawal once sufficient cash value has accumulated. This reduces the cash value and the future death or maturity benefit proportionally, but the policy continues running.
Key conditions: Most plans require a minimum remaining cash value post-withdrawal (typically S$5,000–S$10,000). The minimum withdrawal amount is usually S$1,000. Short-term non-par plans typically do not permit partial withdrawals. Tax treatment: proceeds are not subject to income tax in Singapore.
See our Endowment Plan Partial Withdrawal Singapore 2026 article for the step-by-step process and impact on projected returns.
Option 3: Full Surrender — Cancel the Policy and Receive Surrender Value
Full surrender terminates the policy entirely. You receive the surrender value — cash value minus surrender charges — and forfeit all future undeclared bonuses, including the terminal bonus, which often represents 15–30% of projected maturity value.
When surrender makes sense: You are past the break-even point (Year 12–15+ on a 20-year plan), you have a clearly higher-returning alternative use for the funds, or your financial circumstances have permanently changed. Run the numbers first with our Endowment Plan Break-Even Analysis guide.
When surrender is usually a mistake: Years 1–7 (surrender value far below premiums paid), when the need is short-term (use a policy loan instead), or when you are in good health and would need to re-apply for life coverage at higher premiums.
How to Check Your Endowment Plan’s Current Cash Value
Your endowment plan’s cash value at any point can be confirmed through several channels:
- Original policy illustration — Includes a guaranteed surrender value table showing the minimum cash value for each policy year. This is your most reliable reference for the guaranteed floor.
- Insurer’s digital portal or app — Major Singapore insurers (AIA, Prudential, NTUC Income, Great Eastern, Singlife, Manulife) show real-time cash value, declared bonuses, and projected maturity values in their apps.
- Annual policy statement — Sent each year at your policy anniversary, showing cash value as at a stated date including any reversionary bonuses declared that year.
- Formal surrender value quotation — Request from the insurer directly if you are seriously considering surrender or a policy loan. This gives the precise net surrender value after charges as at a specific date, typically valid for 30 days.
- Your financial adviser — Can pull a current valuation directly from the policy servicing system, often faster than calling the insurer.
Should You Access Your Endowment Plan Cash Value Early?
The answer depends on three factors: where you are in the policy term, what you need the money for, and what alternative returns are available.
Policy term position: Early surrender before Year 7–10 almost always results in a net financial loss relative to premiums paid. The longer you hold, the smaller the relative cost of exit — and beyond Year 15, holding to maturity to collect the terminal bonus is typically the rational choice.
Alternative use of funds: If surrender proceeds would be invested in higher-returning assets (e.g. globally diversified ETF portfolio with historical CAGR of 7–10%), the long-term outcome may exceed staying in the endowment, depending on time horizon. If funds would sit at 2–3% in a savings account, the endowment plan likely wins on a risk-adjusted basis. Use our Singapore Retirement Calculator to model your specific scenario.
Liquidity need vs structural exit: For short-term cash needs, a policy loan at 5.5–7% p.a. is almost always more efficient than surrender — it preserves the terminal bonus and maintains the death benefit. Full surrender should be reserved for permanent exits.
Also consider any riders attached to your policy — surrendering cancels these add-ons, and you may need to reapply for equivalent coverage at higher premiums if your health has changed. If you are exploring alternative passive income options, see our Syfe referral code page (use code SRPRFFFCD for a fee waiver) or browse our passive income Singapore guide.
Frequently Asked Questions: Endowment Plan Cash Value Singapore
Is endowment plan cash value taxable in Singapore?
How soon can I take a policy loan on my endowment plan?
What happens to my cash value if I die during the policy term?
Can I access cash value on a short-term endowment plan?
Does a policy loan reduce my death benefit?
How do I compare cash value schedules across different endowment plans?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.