How to Invest in Singapore: Tax-Efficient Strategies to Maximise Returns (2026)
Singapore investors have a powerful tax advantage most people never fully use. There is no capital gains tax here, CPF earns a guaranteed 2.5–4.0% tax-free, and the Supplementary Retirement Scheme (SRS) gives you an upfront income tax deduction. But your account type and ETF domicile determine how much you actually keep. This guide breaks down every tax-efficient strategy that matters for Singapore investors in 2026.
Not financial advice. All figures are for educational reference only. Data verified as at 6 September 2026 unless noted.
- Singapore has 0% capital gains tax — every dollar of profit from stocks, ETFs and REITs is yours to keep
- Choose UCITS ETFs (Ireland-domiciled, listed on the London Stock Exchange) to cut dividend withholding tax from 30% to 15%
- Maximise your SRS contribution (up to $15,300/year for citizens and PRs) for an immediate income tax deduction plus tax-deferred growth
Table of Contents
Why Tax Efficiency Matters When Investing in Singapore
Tax efficiency is about keeping more of what your investments earn. Most people focus on picking the right stock or ETF — but your account structure and ETF domicile can matter just as much.
Here is a concrete example. Invest $100,000 and it grows at 7% per year for 30 years:
- At 7% (no tax drag): $100,000 grows to $761,226
- At 6% (after 1% annual tax drag): $100,000 grows to $574,349
- The difference: $186,877 lost to avoidable tax drag
That gap is mostly avoidable. Singapore’s tax system is genuinely generous to long-term investors — but only if you structure things correctly. The three pillars are: zero capital gains tax, tax-free CPF compounding, and SRS tax deferral. Layer these on top of smart ETF domicile choices and you have one of the most tax-efficient investing setups available to retail investors anywhere in the world.
No Capital Gains Tax — Your Biggest Edge
Singapore does not tax capital gains. When you sell a stock, ETF, or REIT at a profit, you keep every dollar of that gain. Zero. Nil. None.
Compare this to what investors pay elsewhere:
| Country | Capital Gains Tax Rate | Notes |
|---|---|---|
| Singapore | 0% | No CGT for investors |
| United States | 0–20% | Long-term rate; short-term up to 37% |
| United Kingdom | Up to 24% | Depends on income band |
| Australia | Up to 23.5% | 50% discount if held over 12 months |
| Germany | 25% | Flat Abgeltungsteuer on capital gains |
Source: IRAS, IRS, HMRC, ATO (2026). CGT = Capital Gains Tax.
The practical implication: you never need to worry about “tax-loss harvesting” or timing your stock sales around a calendar year. Sell when it makes investment sense, not when taxes dictate.
One important caveat: IRAS may classify very frequent, systematic trading as a “trade” rather than investment, and tax the gains as income. If you are a genuine long-term investor holding stocks and ETFs for months or years, you are fine. If you day-trade as a primary activity, consult a qualified tax professional.
CPF: Your Tax-Free Compounding Machine
CPF is Singapore’s most underappreciated investment account. The interest it pays is completely tax-free — and the returns are guaranteed by the government. Here is what CPF pays in 2026:
- Ordinary Account (OA): 2.5% per year, guaranteed (confirmed for Q3 2026 by CPF Board)
- Special Account (SA): 4.0% per year, guaranteed (floor extended through 31 December 2026)
- MediSave and Retirement Accounts: 4.0% per year
- Bonus interest: An extra 1% on the first $60,000 of combined CPF balances (up to $20,000 from OA)
For a 35-year-old with $100,000 in CPF SA, that is $4,000 per year in tax-free, government-guaranteed returns. Try finding a Singapore bank deposit matching this.
You can also invest CPF OA savings through the CPF Investment Scheme (CPFIS-OA). The first $20,000 must remain in the OA as a set-aside. Anything above can be invested in approved stocks, ETFs, and unit trusts. However, given the guaranteed 2.5% floor, CPFIS-OA only makes sense if you genuinely expect your chosen investment to beat 2.5% after fees — and are willing to accept the risk of earning less.
For a full breakdown of CPFIS strategy including the 35% stock cap, see our CPF investment strategy guide.
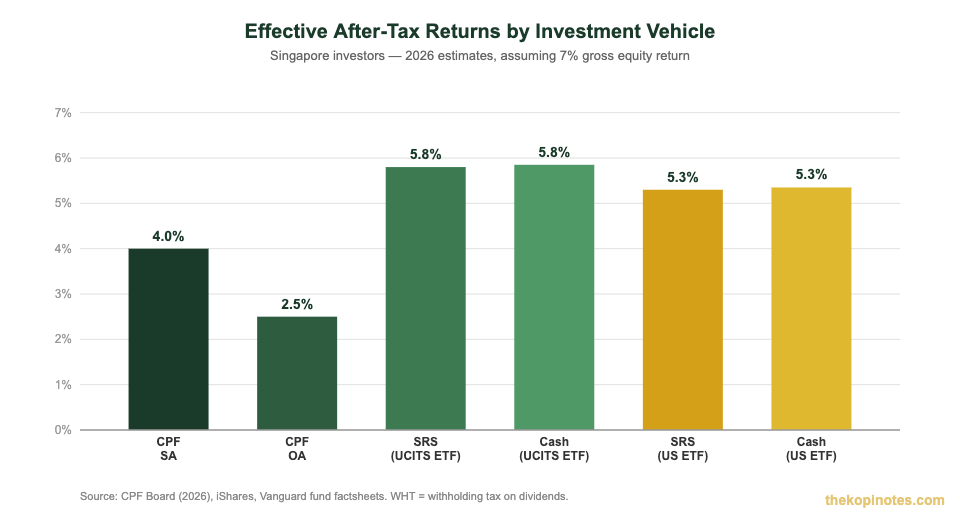
Source: CPF Board (2026), iShares, Vanguard fund factsheets. Equity return estimated at 7% gross. WHT = withholding tax.
SRS: Tax Deduction Today, Tax-Deferred Growth Tomorrow
The Supplementary Retirement Scheme (SRS) is Singapore’s tax-deferred retirement savings vehicle. It works in two ways: you get a tax deduction when you contribute, and your investments grow tax-deferred until you retire.
SRS contribution limits in 2026:
- Singapore citizens and PRs: up to SGD 15,300 per year
- Foreigners working in Singapore: up to SGD 35,700 per year
- Overall personal income tax relief cap: $80,000 (SRS counts toward this)
How the tax deduction works: Contributing $15,300 to SRS in the 11.5% tax bracket saves you $1,760 in income tax — immediately, that year. In the 15% bracket, you save $2,295. This is real money returned to you upfront.
What you can invest in via SRS:
- ETFs and stocks through SRS-enabled brokers: DBS Vickers, OCBC Securities, FSMOne (0% CPF platform fee, competitive SRS rates)
- Endowus for diversified ETF portfolios via SRS — flat 0.30% platform fee for SRS accounts
- Syfe referral code and sign-up bonus — managed portfolios with SRS support, fees from 0.25% to 0.65%
- Singapore Savings Bonds and T-bills via your bank SRS account
Withdrawal rules: After reaching the statutory retirement age (64 from 1 July 2026), only 50% of your SRS withdrawals are included in taxable income. Spread over a 10-year window, many retirees end up paying little or no income tax on their SRS savings. If you withdraw before retirement age, 100% is taxable and a 5% penalty applies — so treat SRS as a true long-term account.
Withholding Tax on Dividends — The Hidden Cost Most Investors Miss
Withholding tax (WHT) is a tax deducted at source before dividends reach you. You never see it — it is taken automatically. And it is the single most important tax consideration for Singapore investors buying global ETFs.
Here is the key fact: the country where an ETF is legally domiciled determines your WHT rate on dividends.
| ETF Domicile | Exchange | WHT on US Stock Dividends | Examples |
|---|---|---|---|
| Ireland (UCITS) | London Stock Exchange | 15% | CSPX, VWRA, SWRD, IWDA |
| United States | NYSE / Nasdaq | 30% | VOO, SPY, VT, QQQ |
| Singapore | SGX | 0% (SG dividends) | ES3 (STI ETF), LION-OCBC APAC |
Source: IRS, Ireland-Singapore Double Taxation Agreement, IRAS (2026). WHT = Withholding Tax.
Why this matters in dollars: Most global ETFs pay around 2% dividends per year. On a $100,000 portfolio:
- US-listed ETF (30% WHT on $2,000 dividend): you lose $600 per year
- UCITS ETF on LSE (15% WHT on $2,000 dividend): you lose $300 per year
- Annual saving from choosing UCITS: $300
Over 20 years with reinvestment, that $300/year difference compounds to over $12,000. This is entirely legal — you are simply choosing the more tax-efficient share class of the same underlying index.
The practical swap for Singapore investors:
- Instead of VOO (Vanguard S&P 500, US-listed) → use CSPX (iShares Core S&P 500 UCITS ETF, LSE)
- Instead of VT (Vanguard Total World, US-listed) → use VWRA (Vanguard FTSE All-World UCITS ETF, LSE)
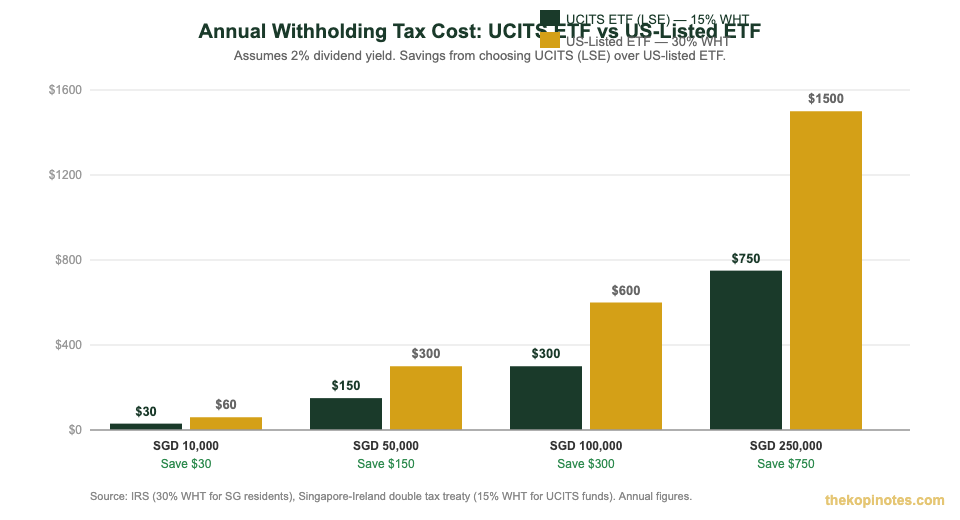
Source: IRS (30% WHT for Singapore residents), Singapore-Ireland Double Taxation Agreement (15% WHT for UCITS funds). Assumes 2% dividend yield. Annual figures.
Which Account to Use for Which Asset
Not all investments belong in all accounts. Here is a practical asset-location guide for Singapore investors:
CPF OA: Leave as cash at 2.5% guaranteed. Only invest via CPFIS if you have high conviction a fund will significantly beat 2.5% after fees and risk. Most investors are better served leaving OA untouched.
CPF SA: Leave as cash at 4.0% guaranteed. Do not transfer SA money to OA — you permanently lose the 1.5% rate advantage. Consider topping up via the Retirement Sum Topping-Up Scheme for up to $8,000/year tax relief.
SRS account: Ideal home for UCITS ETFs (CSPX, VWRA) via Endowus or FSMOne. Your SRS money is already tax-advantaged — compound it in your highest-growth assets.
Cash brokerage account: Also use UCITS ETFs on the London Stock Exchange. For competitive FX rates and low commissions on LSE trades, IBKR (referral: jianxiong368) is a popular choice among Singapore investors.
| Asset Type | Best Account | Reason |
|---|---|---|
| Singapore T-bills / SSBs | Cash or SRS | SRS gives tax deduction on risk-free returns |
| UCITS global ETFs (CSPX, VWRA) | SRS + Cash brokerage | 15% WHT, no CGT, best long-term growth |
| Singapore REITs (S-REITs) | Cash brokerage | 0% WHT on distributions for SG investors |
| Fixed deposits | SRS (via SRS account at bank) | SRS deduction offsets FD interest income |
| CPF OA (invest vs save) | Leave as cash (usually) | Guaranteed 2.5% beats most risk-adjusted alternatives |
Source: TKN analysis based on IRAS, CPF Board tax treatment rules (2026).
For our full guide on T-bills as a low-risk investment option, see Singapore T-bills 2026 guide.
Year-End Tax Moves Every Singapore Investor Should Make in 2026
Tax efficiency is not just about what you invest in — it is also about when you act. Here are four year-end moves that matter most:
1. Top up SRS before 31 December 2026. SRS contributions must be made by 31 December to count for Year of Assessment 2026. You can contribute right up to the last day of the year. Maximum $15,300 for citizens and PRs.
2. CPF Retirement Sum Top-Up (RSTU). Top up your own CPF SA or RA, or your parents’ CPF, by up to $8,000 each for income tax relief. This is separate from SRS — you can do both.
3. Review your CPF OA balance. If your OA has grown above the $20,000 set-aside, consider whether you want to invest the excess via CPFIS or leave it at 2.5%. Check your CPFIS eligibility at cpf.gov.sg.
4. Time your SRS contribution, not the market. SRS tax relief is based on the year of contribution — not on investment returns. Contributing $15,300 in December gives you the same deduction as contributing in January. But the sooner you contribute in the year, the longer your money has to compound inside SRS.
Want to see how these moves affect your retirement number? Use our Singapore retirement calculator to model different SRS and CPF contribution scenarios.
The Bottom Line on Tax-Efficient Investing in Singapore
Singapore’s tax system genuinely rewards long-term investors. You just need to know how to use it.
Start here: stop buying US-listed ETFs if you can access UCITS equivalents. The 15 percentage point WHT saving is real money over a 20-year horizon. Then maximise your SRS for the immediate tax deduction. Let CPF compound at its guaranteed rates. And hold your investments long-term — because in Singapore, there is no capital gains tax waiting to take a slice when you sell.
None of this is complicated. None of it requires a financial advisor. And all of it compounds, quietly, in your favour, year after year.
Frequently Asked Questions
Is there capital gains tax in Singapore?
What is withholding tax and how does it affect my ETF returns?
Should I prioritise SRS or CPF contributions?
Which ETFs are most tax-efficient for Singapore investors?
What is the deadline to top up SRS for tax relief in 2026?
Can I invest CPF money in stocks and ETFs?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.