UOB Fixed Deposit Rate (November 2026): 1.70% Promo — Is It Worth It?
UOB’s FD promo expires 30 November. Here’s how 1.70% stacks up against CIMB, OCBC, T-bills and your own UOB One Account.
UOB’s November 2026 fixed deposit promo gives you 1.70% p.a. for 12 months on a minimum S$10,000 placement of fresh funds via the TMRW app. The offer runs until 30 November 2026 — just days from now. That rate beats DBS’s board rate but trails CIMB (2.30%) and Hong Leong Finance (2.08%), making UOB FD a mid-tier choice for new-to-UOB customers who already use the TMRW ecosystem.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
UOB Fixed Deposit Rates (November 2026)
UOB runs a monthly fixed deposit promotion that resets at the start of each month. For November 2026, the promo rates apply to fresh funds only (money not already with UOB), placed exclusively via the UOB TMRW mobile app. Branch placements and internet banking placements are not eligible for the promo rate.
| Tenor | Promo Rate (p.a.) | Board Rate (p.a.) | Min. Deposit |
|---|---|---|---|
| 6 months | 1.60% | 0.65% | S$10,000 |
| 10 months | 1.65% | 0.90% | S$10,000 |
| 12 months | 1.70% | 1.00% | S$10,000 |
Source: fixeddepositrates.sg (via UOB’s published rates), checked 22 November 2026. Promo valid until 30 November 2026.
Three things to note before you place your deposit:
- Fresh funds rule: Existing UOB balances (savings, current, or other FDs) do not qualify for the promo rate. You must transfer in money from outside UOB.
- TMRW app only: The promo rate is not available at branches or via UOB internet banking. You need the TMRW app installed and an active account.
- Promo ends 30 November 2026: If you are reading this after that date, check UOB’s site directly — December rates may differ. We covered the UOB fixed deposit October 2026 article when the same 1.70% 12-month rate first launched.
UOB FD vs Other Banks Compared (November 2026)
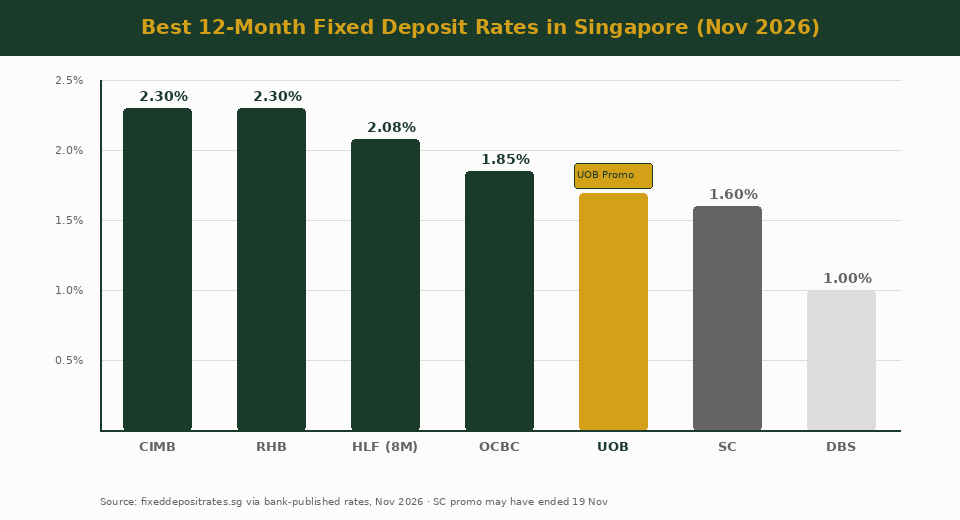
UOB’s 1.70% promo rate is not the highest available in Singapore right now. Here is how the major bank FD offers look for a 12-month placement as at November 2026.
| Bank | Best Rate (12M) | Min. Deposit | Key Conditions |
|---|---|---|---|
| CIMB | 2.30% | S$10,000 | Online placement, promo rate |
| RHB | 2.30% | S$20,000 | Online placement, promo rate |
| Hong Leong Finance | 2.08% (8M) 1.80% at 12M (open-to-all) |
S$20,000 | 2.08% for existing HLF customers online; 1.80% branch rate open to all |
| OCBC | 1.85% | S$20,000 | Fresh funds, online / OCBC app |
| UOB | 1.70% | S$10,000 | Fresh funds, TMRW app only, promo to 30 Nov 2026 |
| Standard Chartered | 1.60% | S$25,000 | Fresh funds, online; promo may have ended 19 Nov 2026 |
| DBS/POSB | 1.00% | S$1,000 | Board rate, no active promo; accessible from S$1,000 |
Source: fixeddepositrates.sg (aggregating bank-published rates), checked 22 November 2026. Rates subject to change.
The main takeaway: CIMB currently leads the market at 2.30% p.a. with a lower minimum than OCBC (S$10,000 vs S$20,000). If you are purely rate-chasing and do not have an existing relationship with UOB, CIMB is worth looking at — see our breakdown of the highest fixed deposit rates in Singapore for the full market picture including sub-12-month tenors.
UOB’s advantage over OCBC is the lower minimum deposit (S$10,000 vs S$20,000), which matters for savers who cannot tie up S$20,000 for a year.
UOB Fixed Deposit vs UOB One Account
If you already bank with UOB, the more important comparison is between a UOB fixed deposit and the UOB One Account interest rate, which can reach up to 7.60% p.a. — but only when you fulfil multiple bonus criteria.
Here is how the two products differ in practice for a Singapore salaried professional:
| Feature | UOB Fixed Deposit | UOB One Account |
|---|---|---|
| Best rate available | 1.70% p.a. | Up to 7.60% p.a. |
| Rate type | Guaranteed (locked in at placement) | Variable (depends on tier fulfilment each month) |
| Key requirements | S$10,000 fresh funds, TMRW app | Salary credit (S$2,000+), UOB credit card spend (S$500+/month) |
| Liquidity | None — funds locked for tenor | Full — withdraw anytime |
| Best for | Money you will not touch for 6–12 months | Working capital / emergency fund |
Source: TKN research. UOB One Account rates as per UOB’s November 2026 rate table.
The verdict: If you can fulfil the UOB One Account bonus tiers, the savings account pays far more than the FD. The FD makes sense only for money you are certain you will not need — for instance, a renovation fund you are accumulating before a planned project, or proceeds from a property sale parked while you search for the next one.
UOB Fixed Deposit vs Singapore T-Bills (November 2026)
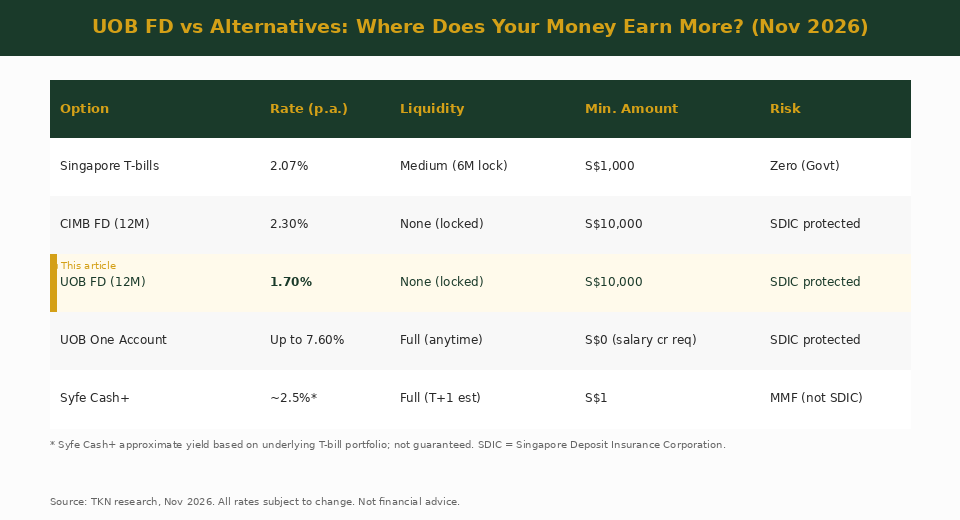
Singapore government T-bills are the most direct competitor to bank fixed deposits for risk-averse savers. In November 2026, the Singapore T-bill yield reached 2.07% — materially higher than UOB’s 1.70% promo.
| Factor | UOB FD (12M) | Singapore T-Bill (6M) |
|---|---|---|
| Rate (November 2026) | 1.70% p.a. | 2.07% p.a. |
| Minimum investment | S$10,000 | S$1,000 |
| Tenor | 12 months | 6 months (re-tender every auction) |
| Credit risk | Protected by SDIC up to S$100,000 | Singapore government (AAA-rated) |
| Rate certainty | Rate locked for full 12 months | Rate locked for 6 months; re-tender risk at maturity |
| CPF/SRS eligible | Yes (OA, SA, RA via approved banks) | Yes (OA and SRS) |
Source: MAS T-bill cut-off yield, November 2026 auction; UOB FD promo rate as of 22 November 2026.
At 2.07% vs 1.70%, T-bills currently pay 37 basis points more than UOB’s best FD. On S$50,000, that difference is roughly S$185 per year. The trade-off: T-bills mature every 6 months (re-tender risk), while UOB FD locks your rate for 12 months.
If you believe Singapore interest rates will fall in 2027, locking in UOB’s 12-month rate could make sense — but at a 37bp deficit to T-bills, the conviction needs to be strong.
How to Open a UOB Fixed Deposit via TMRW App
To capture the November 2026 promo rate, you must place via the TMRW app before 30 November 2026. Here is the step-by-step:
- Download the UOB TMRW app from the App Store (iOS) or Google Play (Android), if you have not already.
- Log in with your UOB internet banking credentials or create a new UOB account via the app.
- Tap “More” > “Invest & Insure” > “Fixed Deposit”.
- Select your desired tenor (6, 10, or 12 months) and confirm the placement amount (minimum S$10,000).
- Transfer fresh funds from an external bank account (not your existing UOB savings). The promo rate will be applied only if the funds are new to UOB.
- Review the rate displayed and confirm. Save the confirmation screen as proof of the promo rate applied.
If you are not an existing UOB customer, you will need to open a UOB account first — this can be done digitally via the TMRW app in roughly 10–15 minutes with your NRIC and SingPass.
Early withdrawal penalty: Breaking a UOB fixed deposit early forfeits all accrued interest. If you anticipate needing the funds before the tenor ends, consider a shorter 6-month placement or a liquid alternative.
Is UOB Fixed Deposit Worth It in November 2026?
UOB’s 1.70% p.a. is not the market leader, but it is competitive within the big-three bank universe (DBS, OCBC, UOB). Here is the decision framework:
| Your Situation | Recommended Option |
|---|---|
| Rate-chasing, flexible on bank | CIMB (2.30%), min S$10,000, online. See CIMB FastSaver interest rate. |
| Want UOB ecosystem, need liquidity | UOB One Account (up to 7.60% with salary credit + spend) |
| Want UOB FD, locking in for 12M | UOB promo at 1.70% — acceptable if you value UOB’s brand and prefer not to manage T-bill auctions |
| Prioritise safety + best rate | Singapore T-bills at 2.07% (backed by Singapore government, min S$1,000) |
| Want full liquidity with decent yield | Money market / cash management alternatives (e.g. Syfe referral code and sign-up bonus for Syfe Cash+, targeting ~2.5% based on underlying T-bill portfolio) |
Source: TKN analysis, November 2026. All rates subject to change.
The 30 November 2026 deadline gives you just days to act if you want the current promo rate. If you miss it, check back in December — UOB typically announces new monthly rates in the first few days of the month. For the full picture of every bank FD available right now, see our guide to the highest fixed deposit rates in Singapore.
Frequently Asked Questions
What is UOB's fixed deposit rate for November 2026?
UOB’s November 2026 promo fixed deposit rate is 1.70% p.a. for a 12-month tenor, 1.65% for 10 months, and 1.60% for 6 months. All promo rates require a minimum placement of S$10,000 in fresh funds (not previously held with UOB) placed via the TMRW app. The promo runs until 30 November 2026.
Is UOB fixed deposit rate the best in Singapore right now?
No. UOB’s 1.70% is competitive among the big three banks (DBS, OCBC, UOB) but not the market leader. As at November 2026, CIMB and RHB both offer 2.30% p.a. for 12 months, while Hong Leong Finance offers 2.08% for 8 months (existing customers). Singapore T-bills are also currently yielding around 2.07%.
Can I place a UOB fixed deposit using existing UOB savings?
No, not for the promo rate. The November 2026 UOB FD promo applies only to fresh funds — money transferred in from outside UOB. If you use existing UOB savings, you will receive the lower board rate (around 1.00% for 12 months), not the 1.70% promo rate.
What happens if I break my UOB fixed deposit early?
Breaking a UOB fixed deposit before it matures means you forfeit all accrued interest. You will only receive back your principal. There is typically no additional penalty beyond the lost interest. If liquidity is a concern, choose a shorter tenor or consider a high-interest savings account instead.
Is my UOB fixed deposit protected under SDIC?
Yes. Deposits at UOB, as a full bank licensed by MAS, are protected by the Singapore Deposit Insurance Corporation (SDIC) for up to S$100,000 per depositor per institution. This coverage includes fixed deposits. If you hold more than S$100,000 with UOB, only the first S$100,000 is covered. Consider spreading larger sums across different banks.
Can I use my CPF OA to fund a UOB fixed deposit?
Yes, CPF Ordinary Account (OA) funds can be invested in fixed deposits at approved banks, including UOB, under the CPF Investment Scheme (CPFIS). However, the CPF OA currently earns 2.5% p.a. guaranteed. With UOB FD at 1.70%, you would earn less by moving OA funds to UOB FD — it only makes sense if you use an approved CPFIS FD that offers a rate above 2.5%.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.