How to Invest in Singapore After the CPF Special Account Closure (2026 Update)
On 19 January 2025, the CPF Board closed the Special Account (SA) for all members aged 55 and above. For over 1.4 million Singaporeans, this meant losing a guaranteed 4% per annum interest-bearing account — with balances above the Full Retirement Sum ($220,400 in 2026) transferred to the Ordinary Account at a lower 2.5% rate. This guide explains what changed, what it means for your retirement, and five strategies to respond.
Not financial advice. All figures are for educational reference only. Data verified as at 15 November 2026.
What Changed on 19 January 2025?
The CPF Special Account (SA) was introduced in 1977 as a dedicated retirement savings account paying a higher interest rate than the Ordinary Account. For nearly five decades, it was the cornerstone of CPF retirement planning — earning at least 4% per annum, with the first S$60,000 of combined CPF balances (up to $20,000 from OA) earning an additional 1%, giving an effective rate of up to 5% per annum.
As part of the CPF Amendment Act 2024, Parliament passed legislation allowing the CPF Board to close all Special Accounts for members aged 55 and above. The closure took effect on 19 January 2025, affecting approximately 1.4 million members.
Why Did the Government Close the SA?
The stated rationale was to simplify the CPF system. Once a member turns 55, their retirement savings move to the Retirement Account (RA), which also earns 4% per annum. With both SA and RA earning the same interest rate, having two separate accounts served no additional purpose — the RA was already doing the same job as SA.
By consolidating SA funds into either RA or OA, the system became structurally simpler. For members whose SA balances fully covered the Full Retirement Sum (FRS), the closure was largely a paperwork change. For members with significant SA balances above the FRS, however, the financial impact was real and material.
Where Did CPF Special Account Savings Go?
The transfer followed a clear priority order:
Step 1: SA funds topped up your Retirement Account (RA) first. If your RA balance was below the Full Retirement Sum ($220,400 in 2026), SA funds were moved to your RA up to that threshold. RA still earns 4% per annum — so this portion is effectively unchanged.
Step 2: Any SA balance above the FRS threshold went to your Ordinary Account (OA). OA earns only 2.5% per annum — 1.5 percentage points lower than the SA rate. This is where the financial impact is felt most acutely.
Members who had made voluntary cash top-ups to SA for years, or who had transferred OA funds to SA to earn the higher rate, found that their carefully accumulated “SA surplus” above the FRS now sat in OA earning significantly less.
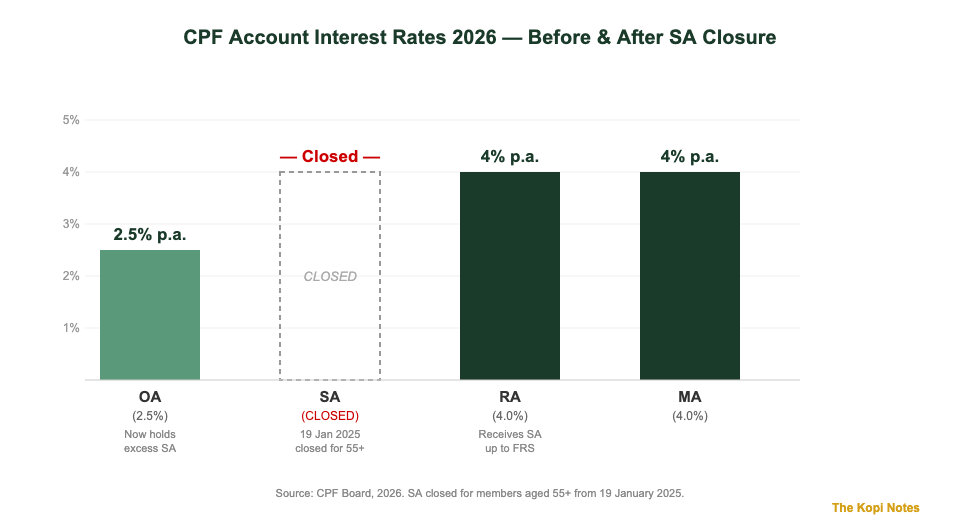
| CPF Account | Base Rate | Extra 1% (first $60k combined) | Status (2026) |
|---|---|---|---|
| Ordinary Account (OA) | 2.5% p.a. | Yes (up to $20k OA) | Active |
| Special Account (SA) | 4.0% p.a. | Yes (up to $60k combined) | Closed for members aged 55+ |
| Retirement Account (RA) | 4.0% p.a. | Yes (up to $60k) | Active |
| MediSave Account (MA) | 4.0% p.a. | Yes (up to $60k combined) | Active |
Source: CPF Board, 2026. First $20,000 of OA earns additional 1%; first $60,000 of combined OA/SA/MA/RA earns additional 1%. Floor rates; actual rates may be higher.
The Real Financial Cost of SA Closure
The numbers are stark. For a member who had $200,000 in SA above the FRS at the time of closure:
- Under the old SA: $200,000 × 4% = $8,000 per year in guaranteed interest
- In OA after closure: $200,000 × 2.5% = $5,000 per year
- Annual shortfall: $3,000 per year
Compounded over 10 years, that difference becomes substantial. The chart below shows the total interest accumulated on $200,000 at each rate over a decade.
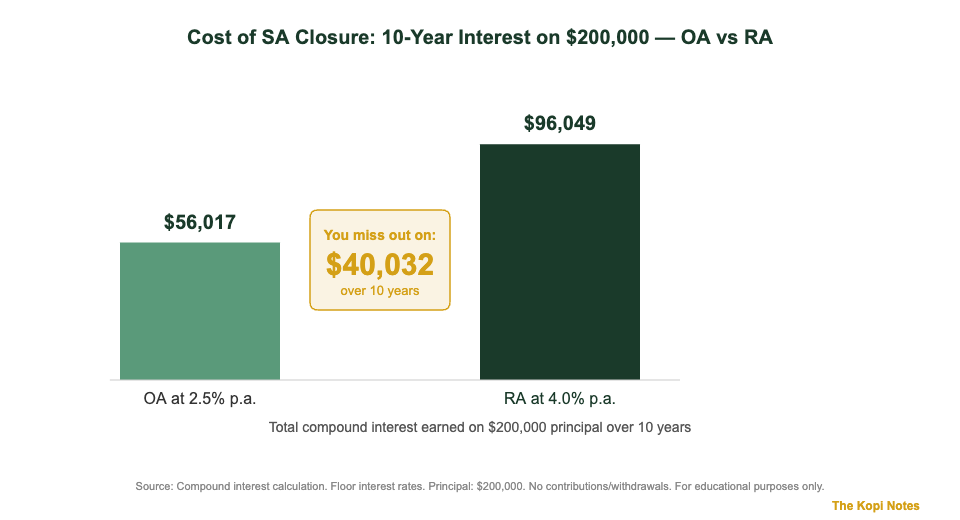
| Scenario | Rate | Year 1 Interest | 10-Year Total Interest |
|---|---|---|---|
| OA (excess SA funds now here) | 2.5% p.a. | $5,000 | ~$55,631 |
| RA (top-up to ERS) | 4.0% p.a. | $8,000 | ~$96,049 |
| Difference (OA vs RA) | −1.5% p.a. | −$3,000 | ~−$40,418 |
Source: Compound interest calculation on $200,000 principal. Floor interest rates (OA: 2.5%, RA: 4.0%). No additional contributions or withdrawals. For educational purposes only.
Impact on CPF LIFE Monthly Payouts
Your CPF LIFE monthly payout at age 65 is calculated based on your RA balance at the point of joining the scheme. Every dollar in RA — rather than OA — earns 4% compounding over your remaining working years, directly translating into a higher lifetime monthly payout. Use the Singapore retirement calculator to model different RA balance scenarios and their monthly CPF LIFE equivalents.
Before vs After: CPF Strategies That Changed
The SA closure changed the playbook for Singaporeans approaching and past age 55. Several strategies that were previously available no longer apply in the same way.
| Strategy | Before Jan 2025 | After Jan 2025 (for 55+) |
|---|---|---|
| OA → SA transfer (voluntary) | ✓ Available (under 55) | ✗ SA closed for 55+ |
| Cash top-up to SA (RSTU) | ✓ Available (under 55) | ✗ Redirect top-ups to RA instead |
| Cash top-up to RA (RSTU) | ✓ Available (all ages) | ✓ Available — now the primary vehicle |
| CPF-IS investments via SA | ✓ Available (under 55) | ✗ SA no longer exists for 55+ |
| CPF-IS investments via OA | ✓ Available | ✓ Still available (up to 35% of investable OA) |
| SRS contributions (cash) | ✓ Available — $15,300/yr | ✓ Now more important than ever |
Source: CPF Board, IRAS, 2026. RSTU = Retirement Sum Top-Up scheme. CPF-IS = CPF Investment Scheme. SRS = Supplementary Retirement Scheme.
For a deeper look at how to structure your overall CPF investment strategy in Singapore, including when to use OA vs RA top-ups and how CPFIS works, see our comprehensive guide.
5 Strategies to Protect Your Retirement After SA Closure
Losing the SA’s 4% return on excess balances is a real setback — but it is not irreversible. Here are the five most effective responses, in priority order for most Singaporeans aged 55 and above.
Strategy 1: Top Up Your RA to the Enhanced Retirement Sum (ERS)
The most direct response to SA closure is to shift excess OA funds into your Retirement Account via RSTU top-ups, up to the Enhanced Retirement Sum (ERS).
- ERS for 2026: $440,800 — that is double the Full Retirement Sum ($220,400)
- Funds in RA earn 4% per annum, the same rate the SA used to earn
- Topping up to ERS maximises your CPF LIFE monthly payout at 65
- Tax relief: cash top-ups to your own RA qualify for income tax relief up to $8,000 per year under the RSTU scheme
Key caveat: Once you transfer OA funds to RA, you cannot reverse the transfer. RA funds are locked in for retirement income and are not withdrawable as a lump sum above the Full Retirement Sum. Only do this if you do not need the OA funds for housing payments or other near-term needs.
Strategy 2: Maximize Your SRS Contributions
The Supplementary Retirement Scheme (SRS) is a voluntary account offered by the three local banks (DBS/POSB, UOB, OCBC) that lets you save and invest outside CPF with significant tax benefits.
- Annual SRS cap: $15,300 (Singapore citizens and PRs); $35,700 for foreigners
- Contributions reduce your taxable income dollar-for-dollar — a $15,300 contribution saves between $306 (2% bracket) and $4,131 (22% bracket) in income tax per year
- SRS funds must be invested to grow meaningfully — leaving them in cash earns only 0.05% p.a.
- Best approach: invest SRS in a low-cost globally diversified index fund through Endowus (referral code: 2V343) or manage it yourself via IBKR (code: jianxiong368)
At withdrawal (age 62 and above), only 50% of SRS withdrawals are taxable, making it a highly tax-efficient retirement vehicle alongside CPF.
Strategy 3: Invest Excess OA Funds via CPFIS
The CPF Investment Scheme (CPFIS) allows you to invest up to 35% of your investable OA savings in eligible instruments, including Singapore Government Securities and certain ETFs. Investing a portion of OA in a broadly diversified equity ETF has historically outperformed OA’s 2.5% floor over the long run — though this comes with market risk and volatility that the OA rate does not carry. Globally diversified equity ETFs are appropriate for a long investment horizon (10+ years) where short-term volatility can be weathered.
Strategy 4: Use T-Bills and Singapore Savings Bonds for OA Cash
If you prefer capital safety but want to avoid the OA → RA lock-in, investing in government securities through CPFIS is an option. However, at current yield levels (November 2026), this is less compelling:
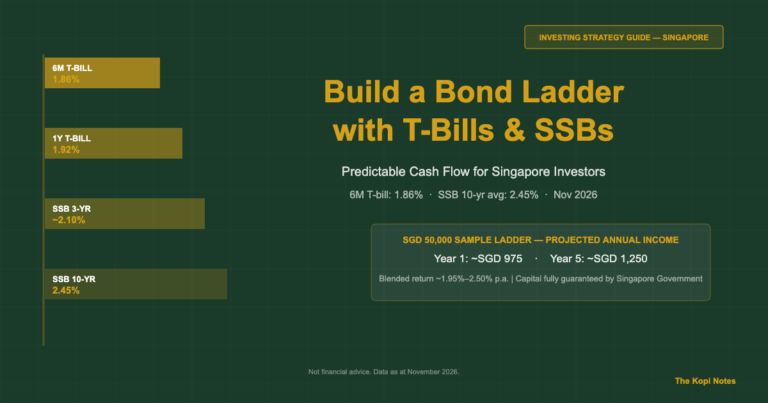
- Singapore T-bills (6-month): ~1.86% — below OA’s 2.5% floor, so not currently advantageous
- Singapore Savings Bonds (SSBs): ~2.45% (10-year average, Nov 2026) — also largely below the OA rate
At current rates, T-bills and SSBs offer lower guaranteed returns than the OA rate. See our Singapore T-bills 2026 guide and Singapore Savings Bonds guide for the most current yield data.
Strategy 5: Deploy Excess Cash Outside CPF into a Diversified Portfolio
For funds held outside CPF, the SA closure is an additional reason to invest excess cash productively rather than leaving it in a low-yield savings account. A broadly diversified, low-cost global equity portfolio has historically delivered annual returns well above the OA rate over 10+ year horizons, though with higher short-term volatility.
- Syfe (referral code: SRPRFFFCD): Managed equity portfolios and cash management (Syfe Cash+), with no minimum investment
- Endowus (code: 2V343): Manages CPF OA, SRS and cash in a unified interface, with access to institutional funds
- IBKR (code: jianxiong368): For self-directed investors who want to buy LSE-listed ETFs like CSPX or VWRA with the lowest commissions available to Singapore retail investors
- Use our Singapore retirement calculator to model different contribution and return scenarios
Frequently Asked Questions
What happened to my CPF Special Account when it closed?
Your SA balance was automatically transferred in a specific order. First, funds were moved to your Retirement Account (RA) up to the Full Retirement Sum — $220,400 in 2026. Any SA balance above that threshold was transferred to your Ordinary Account (OA). RA still earns 4% per annum; OA earns 2.5% per annum.
When exactly did the CPF Special Account close?
The CPF Board closed all Special Accounts for members aged 55 and above on 19 January 2025. This was part of changes introduced under the CPF Amendment Act 2024, as announced in Budget 2024. The closure happened simultaneously for all eligible members regardless of when they individually turned 55.
Can I transfer my OA funds to earn 4% interest after SA closure?
Yes — you can make top-up contributions to your Retirement Account up to the Enhanced Retirement Sum (ERS: $440,800 in 2026) under the Retirement Sum Top-Up (RSTU) scheme. RA earns 4% per annum, the same rate the SA earned. Note that once funds are in RA, they are locked in for retirement income purposes and cannot be withdrawn as a lump sum above the Full Retirement Sum.
Does the SA closure affect Singaporeans below age 55?
No — members below 55 still have an active Special Account. However, when you turn 55, your SA will also be closed automatically, and the same transfer rules apply: SA funds go to RA up to the FRS, and excess goes to OA. The key planning implication is that there is no longer a benefit to accumulating excess SA balances above the FRS if you plan to use those funds in retirement — better to direct contributions to RA top-ups or SRS instead.
How does the SA closure affect CPF LIFE monthly payouts?
Your CPF LIFE monthly payout is calculated based on your RA balance when you join the scheme (typically at age 65). A lower RA balance — because SA funds that would have compounded at 4% ended up in OA at 2.5% — means lower lifetime monthly income. The best mitigation is to top up your RA to the ERS before 65, which both maximises the RA balance and the resulting CPF LIFE payout.
Can I still invest CPF funds after the SA is closed?
Yes. You can still use CPF OA savings to invest through the CPF Investment Scheme (CPFIS). Eligible investments include certain Singapore-listed unit trusts, Singapore Government Securities (T-bills, SSBs), and ETFs. Keep in mind that OA funds not invested still earn 2.5% p.a. guaranteed — a risk-free baseline that is difficult to beat consistently. Globally diversified equity ETFs are suitable for a long horizon (10+ years) through CPFIS.
Disclaimer: The information in this article is for general educational purposes only and does not constitute financial, tax, or investment advice. CPF rules, retirement sums, and interest rates are subject to change. Please refer to the CPF Board’s official website at cpf.gov.sg for the most current information. Data verified as at 15 November 2026.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.