SRS Account Singapore for Foreigners & PRs: Contribution Limits & Tax Benefits (2026 Guide)
Retirement Planning | Updated October 2026
📋 Table of Contents
- What Is the Supplementary Retirement Scheme?
- SRS Contribution Limits: SC/PR vs Foreigners
- Tax Savings by Income Bracket
- How to Open an SRS Account in Singapore
- What to Invest Your SRS Money In
- SRS Withdrawal Rules & the 50% Concession
- What Happens to Your SRS When You Leave Singapore?
- Frequently Asked Questions
The Supplementary Retirement Scheme (SRS) is a voluntary savings scheme that lets Singapore residents — including Singapore Citizens, Permanent Residents, and foreigners — invest for retirement while enjoying immediate income tax relief. Foreigners and PRs can contribute up to $35,700 per year — 2.33× more than the $15,300 cap for Singapore Citizens — making SRS disproportionately powerful for expatriates and high-earning PRs seeking to cut their Singapore tax bill.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
What Is the Supplementary Retirement Scheme (SRS)?
The SRS is administered by the Ministry of Finance (MOF) and is designed to complement CPF savings. Unlike CPF, SRS contributions are entirely voluntary — you decide how much to put in each year, up to your annual cap. The tax incentive is straightforward: every dollar you contribute to SRS reduces your chargeable income by one dollar, resulting in immediate tax savings that reduce the net cost of your contribution.
SRS accounts are available only at three banks in Singapore: DBS, UOB, and OCBC. You can only hold one SRS account at a time. Once opened, you can invest your SRS funds across a wide range of approved products — from unit trusts and ETFs to Singapore Government Securities and insurance products.
The key attraction for expatriates and high-earning PRs is that the foreigner contribution cap of $35,700 per year is significantly higher than the Singapore Citizen cap of $15,300. This difference reflects the fact that foreigners and PRs are not eligible for CPF contributions on the same terms as citizens, and the higher SRS cap provides an equivalent pathway for long-term retirement savings.
SRS Contribution Limits: SC/PR vs Foreigners
The single most important fact for foreigners and PRs reading this guide: your SRS contribution cap is determined by your tax residency status at the time of contribution. Here’s the breakdown:
| Status | Annual SRS Cap | CPF Eligible? | Notes |
|---|---|---|---|
| Singapore Citizen | $15,300 | Yes | CPF supplements SRS; lower SRS cap reflects this |
| Permanent Resident (PR) | $15,300 | Yes (partial) | PRs receive CPF at same rates as citizens |
| Foreigner (EP, S Pass, etc.) | $35,700 | No | Higher cap compensates for no CPF access |
Source: Ministry of Finance, IRAS — SRS Contribution Limits, effective 2015 onwards (unchanged in 2026)
An important nuance: your cap is determined by your status when you make the contribution, not when you opened the account. This means if you are a foreigner when you open your SRS account and later obtain PR status, your cap drops to $15,300 in the year you become a PR. Conversely, you cannot “top up” to the higher foreigner cap in a year you hold PR status.
Also note that contributions must be made in Singapore dollars (SGD) and cannot exceed the cap in any calendar year. The cap applies per year and does not roll over — unused contribution room is forfeited.
Tax Savings by Income Bracket
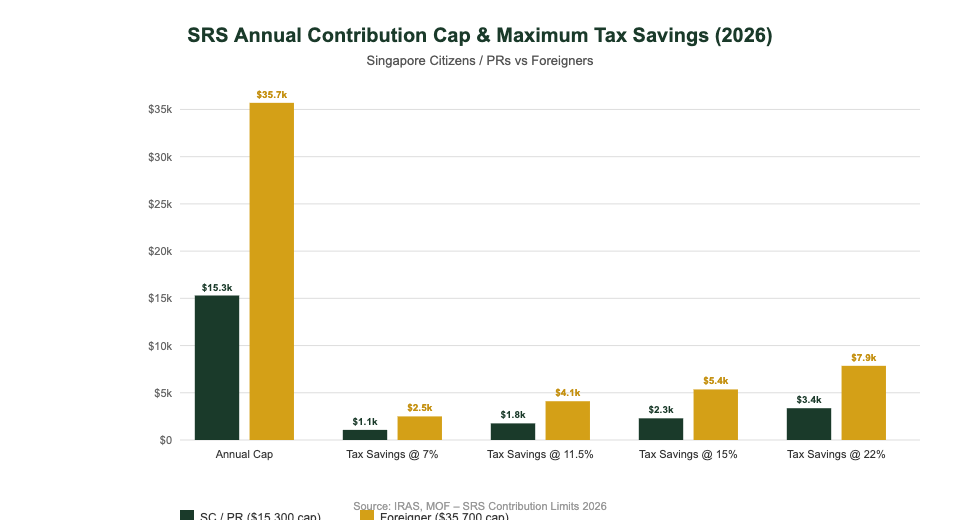
The tax savings from SRS depend on your marginal income tax rate. Singapore uses a progressive tax system — the higher your chargeable income, the higher your marginal rate, and thus the greater the benefit from each dollar of SRS contribution. The table below shows the maximum annual tax savings for both SC/PR ($15,300 cap) and foreigners ($35,700 cap) at each key tax bracket.
| Chargeable Income | Marginal Rate | SC/PR Tax Savings | Foreigner Tax Savings |
|---|---|---|---|
| $40,001 – $80,000 | 7% | $1,071 | $2,499 |
| $80,001 – $120,000 | 11.5% | $1,760 | $4,106 |
| $120,001 – $160,000 | 15% | $2,295 | $5,355 |
| $160,001 – $200,000 | 18% | $2,754 | $6,426 |
| $200,001 – $240,000 | 19% | $2,907 | $6,783 |
| Above $320,000 | 22% | $3,366 | $7,854 |
Source: IRAS Singapore Tax Rates 2026, The Kopi Notes calculations. Tax savings = SRS cap × marginal rate (simplified; actual savings depend on full income structure).
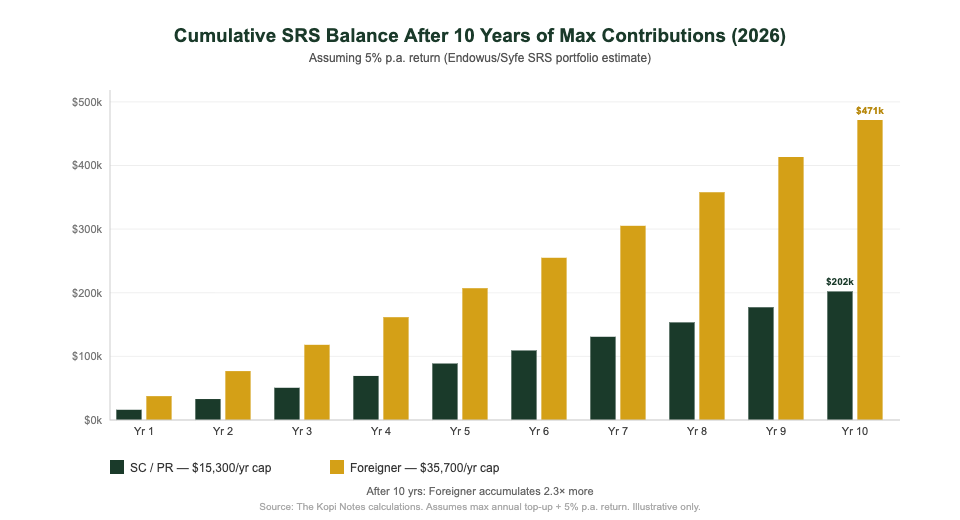
A foreigner on an Employment Pass earning $200,000/year who maxes out their SRS contribution ($35,700) saves $6,783 in taxes annually — that’s nearly 19% of the contributed amount returned immediately as tax savings. Over 10 years of maximum contributions and a 5% annual return, this translates to a retirement nest egg significantly larger than what most SC/PR investors can achieve through SRS alone.
To connect your SRS to a managed portfolio that aims for 5–6% annual returns, consider the Endowus referral code — Endowus is one of the few platforms fully integrated with SRS and offers globally diversified portfolios at institutional fund prices.
How to Open an SRS Account in Singapore
Any Singapore resident who is at least 18 years old, not an undischarged bankrupt, and holds a valid work pass (or is a SC/PR) can open an SRS account. The process is the same regardless of your nationality status:
Step 1: Choose Your SRS Bank
Only three banks offer SRS accounts in Singapore: DBS, UOB, and OCBC. Operationally, the accounts work identically — the same contribution caps and withdrawal rules apply at all three. The choice comes down to your primary banking relationship. If you bank mainly with DBS, open your SRS with DBS; it makes fund transfers simpler. Note: DBS SRS is the only one integrated with Endowus for managed portfolio investing, which is a practical consideration for foreigners who want a hands-off approach.
Step 2: Apply Online or In-Branch
All three banks allow online applications through their internet banking platforms. You’ll need your NRIC (for SC/PR), Passport + valid work pass (for foreigners), and your Singapore tax identification number (TIN). Processing typically takes 1–3 working days.
Step 3: Fund Your Account
Transfer funds from your regular bank account to your SRS account via internet banking. Contributions must be made by 31 December each year to count toward that year’s tax relief. IRAS does not allow backdated contributions — if you miss the deadline, the contribution counts for the following tax year.
Step 4: Invest Your SRS Funds
Cash sitting in your SRS account earns only 0.05% p.a. interest — this is intentionally low to encourage investment. You should invest your SRS funds as soon as they are deposited. See the next section for approved investment options.
What to Invest Your SRS Money In
SRS funds can be invested in a broad range of approved instruments. Unlike CPF-OA (which has restrictions on unit trusts and ETFs above the $20,000 threshold), SRS allows immediate full investment from day one. Here are the main options:
| Investment Type | Platform / Access | Expected Return | Risk Level |
|---|---|---|---|
| Robo-advisor managed portfolios | Endowus (DBS SRS only), Syfe | 4–7% p.a. | Medium |
| Unit trusts / ETFs | FSMOne, brokers | Varies by fund | Medium–High |
| Singapore Government Securities (T-bills, SSBs, SGS bonds) | Via SRS bank | 1.8–2.7% p.a. | Low |
| Singapore REITs & stocks (SGX-listed) | DBS/UOB/OCBC brokerage | 5–8% p.a. | Medium–High |
| Insurance endowments (SRS-eligible) | Banks, insurers | 2.5–4% p.a. | Low–Medium |
Source: Platform websites, MAS-approved SRS investment list 2026. Returns are indicative and not guaranteed.
For most foreigners and PRs who want a low-touch approach, routing SRS funds into a globally diversified robo-advisor portfolio (via Endowus or Syfe) is the most practical option. Syfe also accepts SRS funds and offers a range of portfolios from income-focused to growth-oriented — a good fit for foreigners who may not have the time to actively manage individual securities.
If you prefer to build your own ETF portfolio, FSMOne accepts SRS funds and gives you access to a wide selection of unit trusts and ETFs with competitive transaction fees. This works well for investors familiar with Singapore REIT ETFs and other diversified fund strategies.
For the more passive income-oriented SRS investor, look at the best S-REITs in Singapore 2026 — SGX-listed REITs that distribute regular dividends and are eligible SRS investments via standard brokerage accounts.
SRS Withdrawal Rules & the 50% Concession
Understanding withdrawal rules is critical before committing to SRS — especially for foreigners who may leave Singapore before retirement age. The scheme is designed for long-term retirement savings, with penalties for early withdrawal.
Normal Withdrawal (At or After Statutory Retirement Age)
The current statutory retirement age for SRS withdrawal purposes is 63 years old (for accounts opened or contributions made before 1 July 2022). Only 50% of each withdrawal is added to your chargeable income, creating a powerful tax concession. For example, if you withdraw $40,000 from your SRS in one year, only $20,000 is taxable. If your total chargeable income (including that $20,000) falls within the first $20,000 zero-tax band, you pay zero tax on that withdrawal.
This “50% concession” is particularly valuable for retirees who have no or low earned income — it means you can effectively draw down a substantial SRS balance with minimal or zero tax.
Premature Withdrawal (Before Statutory Retirement Age)
If you withdraw before age 63 without qualifying for an exemption, two penalties apply simultaneously:
- 5% early withdrawal penalty on the amount withdrawn
- 100% of the withdrawal is taxable (the 50% concession does not apply)
This makes early withdrawal economically painful — you lose 5% immediately and face full income tax on the rest. The only exemptions include terminal illness, death, and permanent departure from Singapore (see below).
Withdrawal Window
Once you reach statutory retirement age, you have a 10-year window to draw down your SRS balance. If funds remain after 10 years, the remaining balance is subject to full taxation (100% taxable, no 50% concession). Strategic withdrawal planning — spreading withdrawals across multiple years to stay in lower tax brackets — is therefore important for large SRS balances.
To model how your SRS balance might grow and when to withdraw optimally, the Singapore retirement calculator on TKN can help you plan withdrawal timing.
What Happens to Your SRS When You Leave Singapore?
This is the most common concern for foreign SRS account holders — and for good reason. If you leave Singapore permanently (your Employment Pass is cancelled and you do not intend to return), you may be eligible to close your SRS account early under the “permanent departure” exemption.
Permanent Departure Exemption
Foreigners (and PRs who have renounced their PR status) who leave Singapore permanently can close their SRS account without the 5% early withdrawal penalty. However, 100% of the balance is still taxable — there is no 50% concession for departure withdrawals. You will need to settle your outstanding Singapore income tax before IRAS will issue a tax clearance (IR21), which is required before the SRS bank will release the funds.
Key Steps for Departing Foreigners
- Notify your employer to file IR21 (tax clearance) with IRAS at least 1 month before your last day of employment.
- IRAS assesses your outstanding tax, including 100% of your SRS balance as income in your final year.
- After tax is settled, you can instruct your SRS bank to close the account and transfer funds.
- The 5% penalty is waived under the permanent departure exemption — confirm this with your SRS bank in writing.
If you are leaving Singapore temporarily (e.g., secondment abroad with intentions to return), do not close your SRS account — keep it open and invested. Your SRS funds continue to grow tax-deferred during your absence, and you can resume contributions when you return to Singapore.
For PRs Considering Renunciation
If you are a PR who has decided to renounce your PR status, seek advice on the SRS tax implications before proceeding. Your SRS balance could be a significant tax liability in the year of renunciation if withdrawn in full. Spreading withdrawals, if possible, before formal renunciation may reduce your effective tax rate.
Frequently Asked Questions
Can foreigners open an SRS account in Singapore?
What is the SRS contribution limit for PRs in 2026?
Is SRS tax relief in addition to other reliefs?
Can I contribute to SRS while working abroad?
What happens to my SRS if I become a Singapore Citizen after being a foreigner?
Is the SRS 5% penalty waived if I leave Singapore permanently?
Which SRS bank should I choose as a foreigner?
Can I hold SRS and CPF at the same time as a PR?
Bottom Line: SRS is a No-Brainer for Foreigners in Singapore
If you are a foreigner or high-earning PR working in Singapore, the SRS is one of the most powerful and under-utilised tax tools available to you. The $35,700 annual cap for foreigners represents a meaningful deduction — at a 22% tax bracket, you save $7,854 every year just by transferring money from your bank account to your SRS and investing it.
The key is to act: open the account before 31 December of the current tax year to lock in your contribution, invest immediately (do not leave cash sitting at 0.05%), and use a platform suited to your style — Endowus for managed diversified portfolios, Syfe for income or growth-focused options, or FSMOne if you prefer picking your own funds. For a full picture of your retirement needs beyond SRS, use the Singapore retirement planning calculator.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.