Endowment Plan CPF OA Singapore 2026: Can You Use CPFIS to Buy Endowment Policies?
A practical guide to CPFIS-approved endowment policies, the S$20,000 investment floor rule, real return comparisons, and why most Singaporeans are better off leaving their CPF OA untouched.
Yes — you can use your CPF Ordinary Account (OA) savings to buy certain endowment plans under the CPF Investment Scheme (CPFIS). However, there is a critical catch: the first S$20,000 in your OA must remain uninvested, very few insurers currently offer CPFIS-approved endowment policies, and the guaranteed returns on most CPFIS endowment plans are lower than what your OA earns passively at 2.5% p.a.
Not financial advice. All CPF interest rates are as at 1 July to 30 September 2026, per CPF Board. Data verified as at 9 October 2026. Verify current figures at cpf.gov.sg before making any investment decision.
Table of Contents
Contents — Click to expand
- What Is CPFIS and How Does It Apply to Endowment Plans?
- CPFIS Eligibility: The S$20,000 Floor Rule
- CPFIS Endowment vs Leaving Money in CPF OA
- Which Endowment Plans Qualify Under CPFIS?
- Step-by-Step: How to Use CPF OA for a CPFIS Endowment Plan
- Pros and Cons of CPFIS Endowment Plans
- Smarter Alternatives to CPFIS Endowment Plans
- Frequently Asked Questions
What Is CPFIS and How Does It Apply to Endowment Plans?
The CPF Investment Scheme (CPFIS) lets Singapore CPF members invest their Ordinary Account (OA) and Special Account (SA) savings in approved financial products — instead of leaving money to earn the standard 2.5% p.a. (OA) or 4% p.a. (SA) interest.
Endowment policies are explicitly listed as eligible under both CPFIS-OA and CPFIS-SA. In practice this means: if an insurer has submitted its endowment plan to the CPF Board and received approval, you can pay its premiums using your CPF OA (or SA) savings rather than cash.
CPFIS was introduced to give CPF members a chance to earn potentially higher returns than the guaranteed floor rates — but this comes with important trade-offs: capital is at risk, products vary widely in quality, and the CPF Board does not endorse any specific product.
What CPFIS-OA Allows
Under CPFIS-OA, you can invest in a broad range of approved assets, including:
- Unit trusts (managed funds)
- Investment-linked policies (ILPs)
- Annuities and endowment policies
- Singapore Government Securities and Treasury Bills
- Stocks, REITs and ETFs listed on SGX (subject to the 35% stock limit)
- Gold-related investments
Note: Shares, REITs, and non-gold ETFs are subject to a combined stock limit of 35% of your investable OA savings. Endowment policies do not fall under this stock limit.
CPFIS Eligibility: The S$20,000 Floor Rule
Before you can invest any CPF OA savings under CPFIS, you must meet a minimum balance threshold:
| Account | Minimum to Keep (Cannot Invest) | What You Can Invest |
|---|---|---|
| CPF OA | S$20,000 | OA balance minus S$20,000 |
| CPF SA | S$40,000 | SA balance minus S$40,000 |
Example: If your CPF OA has S$55,000, you can invest up to S$35,000 under CPFIS-OA. The first S$20,000 stays in OA, earning the standard 2.5% per annum guaranteed.
The Extra 1% Bonus Interest You’d Forgo
Here is a critical consideration that many articles overlook: the first S$20,000 in your OA currently earns 3.5% per annum (2.5% base + 1% extra interest for members under 55, on combined balances up to S$60,000 with up to S$20,000 from OA). When you invest OA savings above S$20,000 into a CPFIS endowment plan, those funds leave the CPF system — they no longer earn CPF interest.
For members aged 55 and above, the bonus structure is even more generous: an extra 2% on the first S$30,000 of combined CPF balances (with up to S$20,000 from OA), plus an extra 1% on the next S$30,000. This makes the opportunity cost of moving CPF savings into CPFIS even higher for older members.
Bottom line: To justify a CPFIS endowment plan, its total return (guaranteed + non-guaranteed) must consistently beat your CPF OA’s effective rate — after fees, over the full policy tenure. That is a high bar.
CPFIS Endowment vs Leaving Money in CPF OA: A Numbers Comparison
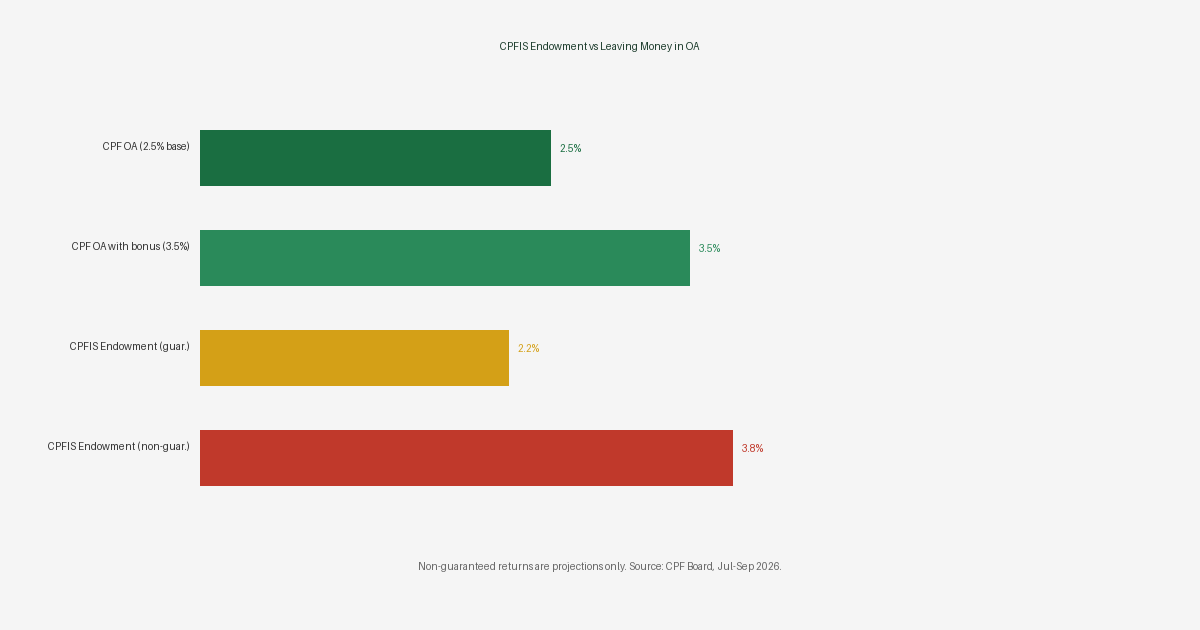
To make an informed decision, you need to compare what a CPFIS endowment plan could realistically return against the risk-free CPF rate. Here is a side-by-side analysis using a S$30,000 investment over 10 years:
| Scenario | Annual Rate | S$30k after 10 years | Risk Level |
|---|---|---|---|
| CPF OA (standard, under 55) | 2.5% guaranteed | S$38,391 | Zero |
| CPFIS Endowment (guaranteed only) | ~2.0–2.2% p.a.* | S$36,581–S$37,077 | Surrender penalty risk |
| CPFIS Endowment (incl. non-guar.) | ~3.0–3.8% p.a.* | S$40,318–S$43,175 | Non-guaranteed — varies |
| CPFIS Unit Trust / ETF (equity) | Market-dependent | Variable (potential ~6–8%)* | Market risk |
*Indicative only. Endowment guaranteed rates vary by insurer and tenure. Non-guaranteed returns are based on historical participating fund performance and are not a promise. Data for illustration only — not a recommendation to invest. Source: CPF Board (OA rate Jul–Sep 2026), insurer product summaries.
Key takeaway: On the guaranteed component alone, most CPFIS endowment plans underperform the CPF OA rate. The only scenario where CPFIS endowment plans make sense is if you have consistently high non-guaranteed bonus declarations from a top-rated insurer’s participating fund — and you are prepared to commit for the full term (typically 10–25 years).
Which Endowment Plans Qualify Under CPFIS?
Not all endowment plans are CPFIS-approved. Each insurer must individually apply to the CPF Board to have a specific product included on the approved product list. The CPF Board maintains a current list on its website — and this list changes as insurers add or remove products.
In practice, CPFIS-approved endowment plans have become increasingly rare. Many major Singapore insurers (AIA, Prudential, Great Eastern, Manulife) have shifted their focus to ILPs, non-par savings plans, or cash-premium endowment plans that are not designed to be funded by CPF. The reduced availability of CPFIS endowment plans is itself a signal that the market does not see them as a compelling product for most consumers.
How to Check If an Endowment Plan Is CPFIS-Approved
- Visit the CPF Board CPFIS page
- Download or view the current list of CPFIS-approved products (updated regularly)
- Filter by “Endowment Policies” under the insurance product category
- Contact the relevant insurer to confirm current availability and premium amounts
Do not rely on secondary sources (blogs, comparison sites) for the definitive list — always verify directly on the CPF Board website or call CPF at 1800-227-1188.
Step-by-Step: How to Use CPF OA for a CPFIS Endowment Plan
If you have identified a CPFIS-approved endowment plan and decided to proceed, here is the process:
- Open a CPF Investment Account (CPFIA) — You need a CPFIA before you can invest. Open one through DBS, OCBC, or UOB (the three CPFIS-authorised agent banks). There is typically a S$26.75 administrative fee to open the account.
- Confirm your investable amount — Log in to my.cpf.gov.sg and check your OA balance minus S$20,000. That is the maximum you can channel into CPFIS.
- Select the CPFIS-approved endowment plan — Get the Product Summary and Benefit Illustration from the insurer. The Benefit Illustration must show both guaranteed and non-guaranteed projections at the CPF Board’s prescribed rates (4.75% and 9% for non-par policies; insurer-specific for par policies).
- Apply through the insurer — Complete the application form with the insurer’s financial adviser. Specify that premiums will be funded via CPF OA.
- Authorise the CPF deduction — The insurer will instruct your agent bank (DBS/OCBC/UOB) to debit premiums from your CPFIA. This is typically done annually or at the start of each policy year.
- Track via my.cpf.gov.sg — CPFIS investments appear in your CPF dashboard under the Investments section. You can view the current surrender value and total premiums paid.
Important: If you surrender the endowment plan early, the surrender value (which may be less than premiums paid) is returned to your CPF OA — not to cash. Early surrender of most endowment plans results in a capital loss, especially in the first 3–5 years.
Pros and Cons of CPFIS Endowment Plans
Pros
- Capital preserved within CPF ecosystem: Surrender values return to CPF OA — your retirement savings stay protected even if the policy underperforms.
- Potential to beat the OA rate: If the insurer’s participating fund performs well, total return (guaranteed + bonuses) can exceed 2.5–3.5% p.a.
- Death and TPD coverage included: Most endowment plans include a sum assured payable on death or total permanent disability — using CPF to fund this gives you life coverage at no additional cash outlay.
- Disciplined savings: Premium payments from CPF are automatic, reducing the temptation to spend OA savings before retirement.
Cons
- Guaranteed return often beats nothing: The guaranteed component of most CPFIS endowment plans (typically 1.75–2.25% p.a.) is lower than the CPF OA rate of 2.5%. You are taking lock-up risk for potentially less guaranteed income.
- Very limited product choice: Few insurers maintain CPFIS-approved endowment plans in 2026. Your options are far narrower than cash-premium products.
- Illiquid for up to 25 years: Endowment plan tenures are long. Early surrender penalties — especially in years 1–5 — can wipe out 20–50% of premiums paid.
- Non-guaranteed returns are not promises: Bonus declarations depend on the insurer’s participating fund performance, which is not guaranteed and can be cut.
- S$26.75 CPFIA account fee: A small but real cost to open the investment account through an agent bank.
- Complexity and mis-selling risk: CPFIS endowment plans are more complex than leaving money in OA. Ensure any financial adviser presents the Product Summary and Benefit Illustration in full before you sign.
Smarter Alternatives to CPFIS Endowment Plans
Given the limited product choice and often-uncompetitive guaranteed returns, many Singaporeans find better risk-adjusted options within the CPFIS framework — or by simply leaving their OA untouched:
1. Leave CPF OA in the Account (2.5% + bonus interest)
For most members, the safest and simplest approach is doing nothing. Your CPF OA earns a guaranteed 2.5% p.a., plus 1% bonus interest on the first S$20,000 (effective 3.5% on that tranche). No fees, no lock-up risk, fully liquid within CPF rules. If you are saving for a first home, OA funds also remain available for housing.
2. CPFIS-Approved Unit Trusts and ETFs
Under CPFIS-OA, you can access a wider range of unit trusts and ETFs that have the potential for higher long-term returns. Platforms like Endowus (referral code: 2V343, valid for cash investments; CPF access via CPFIS-OA) and Syfe (code: SRPRFFFCD) offer low-cost diversified portfolio options. These carry market risk but offer better liquidity and lower fees than most endowment plans.
3. Cash-Premium Endowment Plans (Outside CPF)
If you want the guaranteed returns and capital protection of an endowment plan, consider buying one with cash instead of CPF. This frees your OA savings to earn CPF interest AND work towards your housing needs or retirement sum. Read our guide on the endowment plan laddering strategy for how to structure a cash-funded approach across multiple tenors.
4. CPF SA Top-Up (for Retirement Planning)
If your goal is retirement income rather than a specific payout date, topping up your CPF Special Account (SA) directly — rather than investing it via CPFIS — earns a guaranteed 4% p.a. floor rate with zero fees. Under the Enhanced Retirement Sum (ERS) rules, you can earn up to 6% p.a. effective interest on retirement accounts depending on your age and balance tier.
For a full comparison of your retirement savings options, see our Singapore Retirement Planning Calculator.
Frequently Asked Questions
Can I use CPF OA money to buy any endowment plan in Singapore?
No. Only endowment plans that have been specifically approved by the CPF Board under the CPF Investment Scheme (CPFIS) are eligible. The approved product list is maintained on cpf.gov.sg and is updated regularly. Many popular endowment plans sold in Singapore are not CPFIS-approved and must be purchased with cash.
How much CPF OA can I invest under CPFIS?
You can invest any amount above the first S$20,000 in your CPF OA. The S$20,000 floor must remain in your OA at all times and cannot be invested. For example, if your OA balance is S$50,000, you can invest up to S$30,000 under CPFIS. Check your investable amount via my.cpf.gov.sg under the Investments section.
What happens to my CPFIS endowment plan if I surrender it early?
If you surrender a CPFIS-funded endowment plan before maturity, the surrender value (which is typically lower than premiums paid in the early years) is returned to your CPF OA — not to cash. Early surrender penalties in the first 5 years can result in a significant capital loss. Always check the surrender value schedule in the Product Summary before committing.
Is it better to leave money in CPF OA or invest via CPFIS endowment plan?
For most Singaporeans, leaving money in CPF OA is the lower-risk choice. The OA earns a guaranteed 2.5% p.a. (with up to 3.5% on the first S$20,000 for members under 55), with zero fees, full liquidity within CPF, and no lock-up risk. The guaranteed component of most CPFIS endowment plans (typically 2.0–2.2% p.a.) is lower than this. A CPFIS endowment plan only makes sense if you have strong conviction in the insurer’s participating fund performance over a long horizon.
Do I need to open a special account to invest CPF via CPFIS?
Yes. You need to open a CPF Investment Account (CPFIA) through one of the three CPFIS agent banks: DBS, OCBC, or UOB. There is typically a S$26.75 one-time account opening fee. Once the CPFIA is open, all your CPFIS investments (endowment plans, unit trusts, shares, ETFs) are consolidated under this account and visible on my.cpf.gov.sg.
Can I use CPF SA (Special Account) to buy endowment plans too?
Yes — endowment policies are eligible under both CPFIS-OA and CPFIS-SA. However, using CPF SA for CPFIS is generally a worse idea than using OA, because CPF SA earns a guaranteed 4% p.a. (significantly higher than the OA’s 2.5%). The bar for a CPFIS-SA investment to beat the SA’s risk-free return is much higher. You must also keep at least S$40,000 in your SA before any of it can be invested.
Disclaimer: This article is for educational purposes only and does not constitute financial, insurance, or investment advice. CPF interest rates and CPFIS-approved product lists change — always verify current details on cpf.gov.sg or call CPF at 1800-227-1188. Past performance of participating funds is not indicative of future results. The Kopi Notes is not a licensed financial adviser under the Financial Advisers Act. Consult a MAS-licensed adviser before making decisions. Data verified as at 9 October 2026.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.