Term Life Insurance for Women in Singapore 2026: Maternity, Cancer & the Protection Gap
Table of Contents
- Why Women in Singapore Need Tailored Life Insurance
- The Cancer Risk Singapore Women Actually Face
- Premium Comparison: Women vs Men (What You Actually Pay)
- What to Look For in Your Term Life Policy
- Maternity Exclusions and Pre-Existing Conditions
- How Much Coverage Do Women in Singapore Need?
- Top Term Life Plans for Women 2026 Comparison
- Frequently Asked Questions
Term life insurance for women in Singapore works the same way as for men — you pay premiums for a fixed period, and your dependants receive a lump sum if you pass away during that term. But women in Singapore face distinct risks: a 1-in-10 lifetime breast cancer risk, higher rates of certain cancers, and career gaps that affect income protection needs. Choosing the right term life policy — with the right riders and coverage amount — requires understanding these unique factors, not just picking the cheapest premium. Data as at October 2026.
Not financial advice. All figures are for educational reference only. Speak with a licensed financial adviser before purchasing any insurance product. Data verified as at 7 October 2026.
Why Women in Singapore Need Tailored Life Insurance Coverage
The assumption that life insurance is primarily a concern for male breadwinners is dangerously outdated in Singapore. Today, life insurance for Singapore residents must account for dual-income households, single mothers, and women who are the primary financial providers for ageing parents.
Three factors make term life insurance planning different for women in Singapore:
1. Longer life expectancy creates a longer income-replacement window. Singapore women live to an average of approximately 87 years, compared to 83 for men (SingStat, 2024). This means your financial dependants — whether children or elderly parents — may rely on your income for longer. Your term life coverage period should account for this extended window.
2. Breast and reproductive cancers create specific critical illness (CI) needs. Breast cancer alone accounts for about 29% of all cancers in Singapore women (Singapore Cancer Registry, 2019–2023). Standard term life pays a lump sum only on death. If you survive a cancer diagnosis — which is increasingly likely — you may need a CI rider to cover treatment costs and income loss during recovery.
3. Career breaks affect income-based coverage calculations. Many women in Singapore take maternity leave or career breaks to care for children or elderly relatives. During these periods, income-replacement calculations change. It’s important to lock in your coverage before a health event (e.g. pregnancy complications) could make you uninsurable or attract premium loading.
The Cancer Risk Singapore Women Actually Face
Understanding your statistical health risks helps you decide whether a standalone term life policy is sufficient, or whether you need riders or a supplementary critical illness plan.
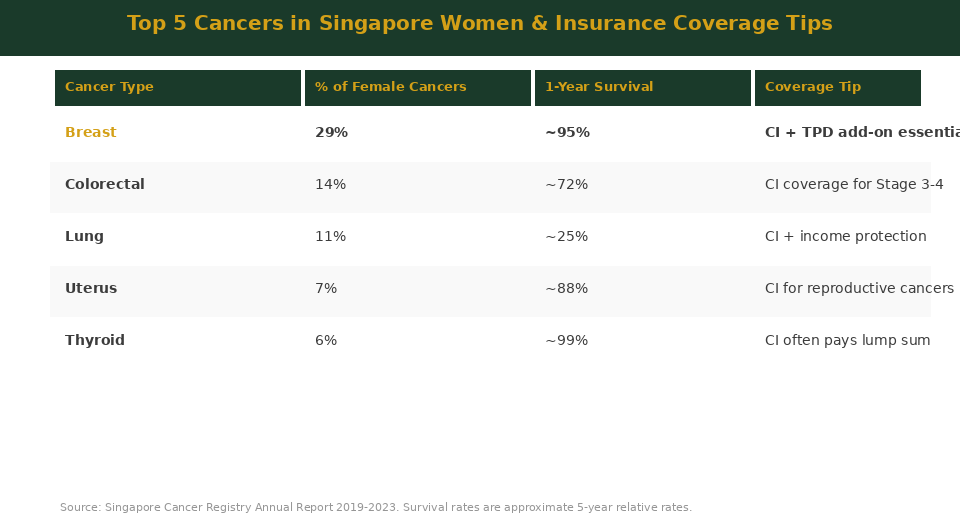
Source: Singapore Cancer Registry Annual Report 2019–2023. Survival rates are approximate 5-year relative rates. Not financial advice.
Key takeaways from the cancer data:
Breast cancer (29% of female cancers): Singapore’s breast cancer incidence rate is among the highest in Asia, at approximately 68 per 100,000 women per year (Age-Standardised Rate, SCR 2019–2023). The 5-year relative survival rate for early-stage (Stage I) breast cancer is around 95%, meaning most patients survive — but treatment costs can exceed SGD 80,000–150,000 even with MediShield Life. A critical illness insurance add-on pays a lump sum upon diagnosis, helping cover the income loss during recovery.
Colorectal and lung cancers tend to have lower survival rates, making CI coverage even more important for income replacement if you’re unable to work for months or years.
Thyroid cancer (common in younger women) has a very high survival rate but still requires time off work and treatment costs that a term life plan alone won’t cover.
Practical implication: Most financial planners in Singapore recommend that women pair a term life plan with a separate critical illness (CI) plan covering at least 36 LIA-defined conditions. This combination — term life + CI — provides both death benefit and living benefit coverage.
Premium Comparison: Women vs Men (What You Actually Pay)
Here’s the good news for women: term life insurance premiums in Singapore are generally lower for women than for men. Insurers base premiums on statistical mortality rates, and women in Singapore live longer on average, meaning the actuarial risk of a death claim during a 20-year term is lower.
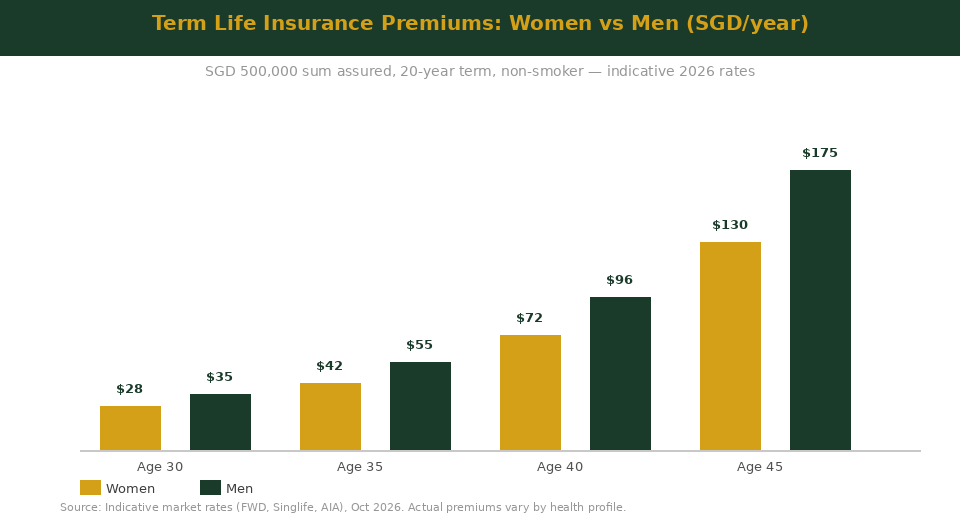
Source: Indicative market rates (FWD, Singlife, AIA), October 2026. SGD 500,000 sum assured, 20-year term, non-smoker. Actual premiums vary by health profile and insurer. Not financial advice.
| Age at Entry | Women (SGD/month) | Men (SGD/month) | Women Save |
|---|---|---|---|
| 30 | ~$28 | ~$35 | 20% less |
| 35 | ~$42 | ~$55 | 24% less |
| 40 | ~$72 | ~$96 | 25% less |
| 45 | ~$130 | ~$175 | 26% less |
Source: Indicative market rates based on FWD, Singlife, AIA offerings, October 2026. SGD 500,000 sum assured, 20-year term, non-smoker. These are indicative figures — get an actual quote from a licensed adviser.
The premium advantage shrinks with age, but at every entry age, women pay meaningfully less than men for identical coverage. If you’re considering purchasing term life, locking in now (at a younger, healthier age) is the most cost-effective strategy — regardless of gender.
Key decision point: A 30-year-old woman can get SGD 500,000 of term life coverage for approximately SGD 28/month. That’s SGD 336 per year — less than what many Singaporeans spend on a single month of dining out — for coverage that would protect a family’s financial future. You can also explore platforms like Syfe and Endowus for integrated wealth and protection planning.
What to Look For in Your Term Life Policy as a Woman
1. Waiver of Premium Rider
If you become totally and permanently disabled (TPD) or are diagnosed with a critical illness, a waiver of premium rider ensures your policy remains in force without you having to pay premiums. This is especially valuable for women who may face income interruption due to health issues during their reproductive years.
2. Total and Permanent Disability (TPD) Benefit
Standard term life pays only on death. A TPD benefit — either built-in or as a rider — pays the sum assured if you become permanently unable to work. Look for plans that define TPD broadly (not just “unable to perform any occupation ever”) to ensure you can make a successful claim.
3. Critical Illness Add-On or Standalone CI Plan
Given Singapore women’s elevated cancer risk, a CI rider that covers at least the 36 LIA-defined critical illnesses is highly recommended. Some policies offer female-specific CI coverage (FWD Female Protect, AIA Lady Protect) that specifically covers breast cancer, cervical cancer, uterine cancer, and ovarian cancer with a lump-sum payout.
4. Convertibility Option
Some term life plans allow you to convert to a whole life or endowment plan later, without a new medical underwriting process. This is useful if your health deteriorates and you want to extend coverage beyond the original term.
Maternity Exclusions and Pre-Existing Conditions: What to Watch For
One of the most common surprises for women purchasing term life insurance in Singapore: standard term life policies do not typically cover pregnancy-related death as a separate exclusion — in fact, death from pregnancy complications is generally covered under the life benefit. However, there are important nuances:
Pre-existing conditions declared at application: If you have been diagnosed with endometriosis, PCOS, cervical dysplasia, or other reproductive health conditions, the insurer may exclude specific pregnancy or reproductive cancer claims, or apply premium loading. Always declare all pre-existing conditions fully — non-disclosure can result in claim rejection.
Critical illness exclusions: If you add a CI rider, check whether it excludes CI claims arising from pregnancy-related complications. Some riders do exclude “pregnancy-related critical illness” — this can be a significant gap for women planning to start families.
Timing of purchase: You cannot purchase new life insurance during pregnancy in most cases — insurers defer applications until after delivery. If you’re planning to start a family, purchase your term life plan (and any CI riders) before you conceive. Once the policy is in force, death benefit coverage continues throughout pregnancy.
Loading for female-specific conditions: Conditions like BRCA1/BRCA2 genetic markers (elevated breast cancer risk) may result in premium loading or exclusions. Genetic testing results, if known, must typically be disclosed on application forms.
How Much Coverage Do Women in Singapore Need?
The most widely used rule of thumb in Singapore is 9–12 times your annual income. But for women, there are additional factors to consider:
The DIME formula adjusted for women:
| Component | What to Include | Women-Specific Note |
|---|---|---|
| D — Debt | Outstanding mortgage, car loan, PLUS loans in your name | Include joint loans even if co-borrower has their own coverage |
| I — Income replacement | 10 years of current gross income | If primary caregiver, include imputed value of caregiving (SGD 2,000–3,500/month replacement cost) |
| M — Mortgage payoff | Outstanding HDB or private loan balance | Separate from Debt column if jointly owned |
| E — Education | Future university/poly costs for children | SGD 40,000–120,000 per child (polytechnic to private university) |
Source: LIA Singapore financial planning guidelines; TKN calculations based on 2026 Singapore education and living costs.
A 35-year-old Singapore woman earning SGD 6,000/month, with a SGD 400,000 HDB mortgage, two young children, and elderly parents to support, would typically need SGD 800,000–1,200,000 in combined coverage. A standalone term life plan at SGD 500,000 plus a CI plan at SGD 300,000 would be a reasonable starting point.
Use our Singapore retirement planning calculator to model how much of your wealth building depends on your continued ability to earn income — and how much protection you need to backstop that plan.
Top Term Life Plans for Women in Singapore 2026 — What to Compare
When comparing term life insurance plans, look beyond headline premiums. The key variables are:
| Insurer | Entry Age | Max SA | Key Differentiator for Women |
|---|---|---|---|
| FWD Term Life | 18–65 | SGD 5M | FWD Female Protect CI rider available; direct purchase online |
| Singlife Term Life Protect | 18–60 | SGD 5M | Accelerated CI benefit option; competitive women’s rates at age 30–40 |
| AIA Secure Life | 18–70 | Unlimited | AIA Lady Protect CI rider; AIA Vitality health rewards programme |
| Great Eastern TERM Assure | 19–65 | SGD 10M | Optional CI, TPD, and waiver of premium riders |
| Etiqa i-Term | 20–60 | SGD 5M | Budget-friendly; online purchase; CI rider optional |
Source: Insurer product pages and policy documents, October 2026. Coverage limits, entry ages, and rider availability subject to change. Obtain a formal quote from a licensed financial adviser before purchase.
Where to compare and apply: Use a licensed financial comparison platform (such as FSMOne, which offers an insurance marketplace) or engage an independent financial adviser. You can also access Syfe’s financial planning tools to model how insurance fits within your overall wealth plan.
For broader context on protecting your financial future, see our guide on building passive income in Singapore — insurance protection is the foundation on which you build wealth, not the alternative to it.
Frequently Asked Questions
Do women pay less for term life insurance than men in Singapore?
Can I buy term life insurance while pregnant in Singapore?
Does term life insurance cover breast cancer in Singapore?
How much term life insurance should a Singapore woman buy?
What is a female-specific critical illness rider?
Should I get term life or whole life insurance as a woman in Singapore?
The Bottom Line
Women in Singapore benefit from lower term life premiums than men — but that advantage is only valuable if you use it to buy enough coverage. The combination of term life (death benefit) plus critical illness coverage (living benefit) addresses the two main financial risks Singapore women face: premature death and a serious illness that prevents you from working. Lock in your coverage early, before any health events change your insurability. If you need help selecting the right plan, an independent financial adviser can model your specific needs without being tied to any single insurer.
Data verified as at 7 October 2026. This article is for educational purposes only and does not constitute financial advice.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.