MariBank vs GXS Bank (2026): Savings Rates, Credit Cards & Which Digital Bank Wins
A Singapore head-to-head comparison: interest rates, Boost Pockets, cashback cards, fees and October 2026 promotions, with every number checked against the banks’ own websites.
MariBank vs GXS Bank comes down to how you save and spend. MariBank pays a flat 0.88% p.a. base (up to 1.48% with ShopeeVIP and salary crediting) with no lock-in. GXS Bank pays up to 1.75% p.a. if you lock cash in a 12-month Boost Pocket. For cards, Mari’s 1.5% no-minimum card suits light spenders; GXS’s 1.75% card needs S$500 a month.
Not financial advice. Data verified as at 7 October 2026 against the official MariBank and GXS Bank websites. Digital bank rates and promotions change often, so confirm the latest figures in each bank’s app before you deposit.
Table of Contents
Contents — Click to expand
- Quick Answer: MariBank or GXS?
- MariBank vs GXS: Key Differences at a Glance
- Savings Interest Rates Compared
- What S$10,000 and S$50,000 Actually Earn
- Mari Credit Card vs GXS Credit Card
- Fees, Transfers and Everyday Banking
- October 2026 Promotions
- Is Your Money Safe? SDIC and Licensing
- Who Should Pick Which?
- Frequently Asked Questions
Quick Answer: MariBank or GXS?
If you want one account where every dollar earns the same rate and you can withdraw any time, MariBank is the simpler pick. Its Mari Savings Account pays a 0.88% p.a. base on all balances, credited daily, with no minimum deposit, no salary crediting requirement and no fall-below fee. ShopeeVIP members add 0.40% p.a. and salary crediting adds 0.20% p.a., which takes an existing customer to 1.48% p.a.
If you are happy to set money aside for a fixed period, GXS Bank pays more. Its Boost Pockets combine the same 0.88% p.a. base with a bonus paid at maturity, reaching 1.75% p.a. on a 12-month tenure. GXS also runs a time-limited 1.2% p.a. rate on Saving Pockets, which have no lock-in.
On credit cards, the answer flips with your spending. The Mari Credit Card pays 1.5% unlimited cashback with no minimum spend and no annual fee. The GXS Credit Card (in beta) pays 1.75% on local non-Grab spend, but only once you charge S$500 in a billing cycle, and it carries a S$196.20 annual fee after the first year. Plenty of Singaporeans end up holding both: GXS for locked savings and Grab spend, MariBank for liquid cash and Shopee.
MariBank vs GXS: Key Differences at a Glance
| Feature | MariBank | GXS Bank |
|---|---|---|
| Backed by | Sea Group (Shopee’s parent) | Grab and Singtel consortium |
| Base savings rate | 0.88% p.a. on all balances | 0.88% p.a. (Main Account) |
| Highest headline rate | 3.08% p.a. (new user, first 30 days, with ShopeeVIP and salary) | 1.75% p.a. (12-month Boost Pocket) |
| Lock-in needed? | No | Only for Boost Pocket bonus |
| Interest credited | Daily | Daily (Boost bonus at maturity) |
| Minimum deposit / fall-below fee | None / None | None / None |
| Credit card cashback | 1.5% unlimited, no minimum spend | 1.75% unlimited with S$500 minimum; up to 10% in GrabCoins on Grab |
| Card annual fee | Free | S$196.20 (first year waived if approved by 31 Dec 2026) |
| Ecosystem perk | Shopee checkout, 1.5% Shopee Coins via Instant Checkout | Grab and Singtel rewards |
| SDIC deposit insurance | Up to S$100,000 per depositor | Up to S$100,000 per depositor |
Source: MariBank Interest Rates, Fees and Limits and GXS Savings Account page, verified 7 October 2026.
MariBank vs GXS Savings Interest Rates Compared
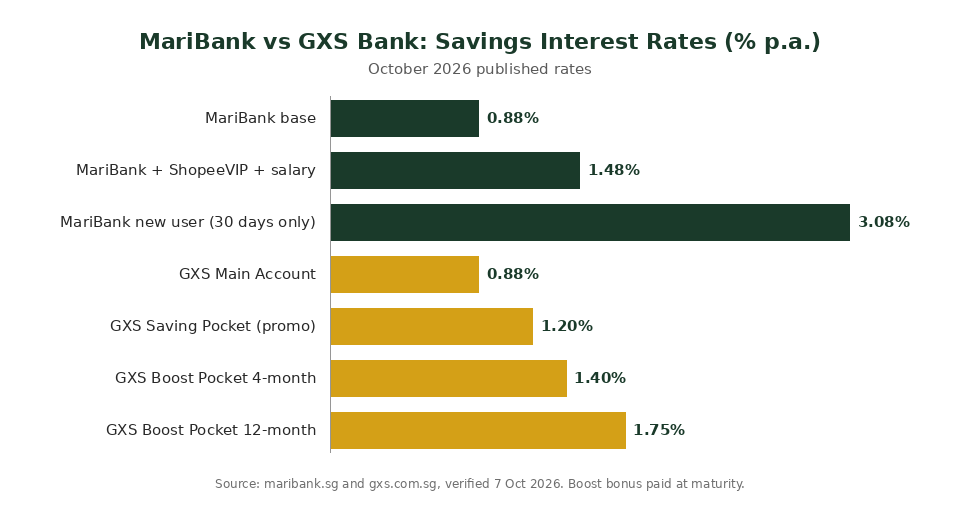
Both banks start at the same 0.88% p.a. base. Where they differ is how you climb above it. MariBank adds bonuses based on who you are (a new customer, a ShopeeVIP member, someone who credits salary). GXS adds bonuses based on how long you commit (the Boost Pocket tenure).
MariBank: one account, stackable bonuses
The Mari Savings Account pays 0.88% p.a. on all balances with no tiers or caps published. On top of that, the bank lists three bonuses under its Bonus Interest Promotion: a 1.60% p.a. welcome bonus for the first 30 days after a new account opens, 0.40% p.a. for ShopeeVIP subscribers, and 0.20% p.a. for crediting your salary. Stack all three and you get the 3.08% p.a. headline, but only for one month. After day 30, a fully qualified customer earns 1.48% p.a.; everyone else earns 0.88% p.a. We cover the full mechanics in our MariBank interest rate guide.
GXS Bank: three pocket types
GXS splits your money into a Main Account, up to eight Saving Pockets and up to eight Boost Pockets. The Main Account earns 0.88% p.a. Saving Pockets are currently on a limited-time 1.2% p.a. rate with no lock-in. Boost Pockets pay the 0.88% p.a. base daily, then a bonus when the pocket matures. Because the bonus is only credited at maturity, plan to leave the money in for the full tenure.
| GXS Boost Pocket tenure | Base (daily) | Bonus (at maturity) | Total rate |
|---|---|---|---|
| 1 month | 0.88% | 0.13% | 1.01% p.a. |
| 3 months | 0.88% | 0.34% | 1.22% p.a. |
| 4 months | 0.88% | 0.52% | 1.40% p.a. |
| 8 months | 0.88% | 0.42% | 1.30% p.a. |
| 12 months | 0.88% | 0.87% | 1.75% p.a. |
Source: GXS Bank, Boost Pocket rates, verified 7 October 2026.
Note the odd shape of the curve: the 4-month Boost Pocket (1.40% p.a.) currently pays more than the 8-month one (1.30% p.a.). If you don’t want to lock money up for a full year, the 4-month tenure is the sweet spot. GXS also caps how much you can hold in total; the limit is shown in your GXS app.
What S$10,000 and S$50,000 Actually Earn
Headline rates are easy to compare but hard to feel. Here is what a Singapore saver would earn over 12 months at each option, using simple interest (daily compounding adds a few cents to a few dollars more). The MariBank new-user line assumes the 1.60% p.a. welcome bonus applies for the first 30 days only, then 0.88% p.a. for the remaining 335 days.
| Option (12 months) | Rate | On S$10,000 | On S$50,000 |
|---|---|---|---|
| MariBank base | 0.88% | S$88.00 | S$440.00 |
| MariBank new user (bonus for first 30 days only) | 2.48% then 0.88% | S$101.15 | S$505.75 |
| MariBank with ShopeeVIP + salary | 1.48% | S$148.00 | S$740.00 |
| GXS Main Account | 0.88% | S$88.00 | S$440.00 |
| GXS Saving Pocket (promo rate held all year*) | 1.20% | S$120.00 | S$600.00 |
| GXS 12-month Boost Pocket | 1.75% | S$175.00 | S$875.00 |
Source: TKN calculation using rates published by MariBank and GXS Bank, verified 7 October 2026. *The GXS Saving Pocket rate is labelled a limited-time promotion and may not last 12 months. GXS deposit caps apply.
The gap is real but modest. On S$10,000, the GXS 12-month Boost Pocket earns about S$87.00 more than MariBank’s base rate over a year. A ShopeeVIP member who credits salary to MariBank narrows that to about S$27.00, and keeps full access to the cash. For larger sums you are willing to lock away, it is also worth comparing against Singapore T-bill yields in 2026 and bank fixed deposit rates before you decide.
Mari Credit Card vs GXS Credit Card
This is where the two banks look most different. MariBank’s card rewards simplicity. GXS’s card rewards commitment, and especially Grab users.
Mari Credit Card
The Mari Credit Card pays 1.5% unlimited cashback on eligible local SGD card spend with no minimum spend. Overseas, there are no FX fees and you earn 1.5% cashback on eligible foreign-currency spend up to S$1,500 a month (a promotion running till 31 December 2027). Shopee purchases via Mari Credit Card Instant Checkout earn 1.5% in Shopee Coins. There is no annual fee and no late fee, though late interest of 30.99% p.a. still applies; the standard rate on unpaid balances is 27.99% p.a. Applicants must be 21 or older. Our full Mari Credit Card review goes deeper on exclusions.
GXS Credit Card (beta)
The GXS Credit Card pays 1.75% unlimited cashback on eligible local non-Grab spend, but only in billing cycles where that spend reaches S$500. Below S$500 you earn nothing on it. Singtel bills earn 1.75% with no minimum. Grab spend earns GrabCoins: 3% with no minimum, 5% with S$500 to S$999.99 of Grab spend, and 10% with S$1,000 or more of Grab spend; both higher tiers also need S$500 of off-Grab spend. Overseas Grab spend earns a flat 10% in GrabCoins, and there are zero FX fees. The trade-offs: a S$196.20 annual fee (waived for the first year if approved by 31 December 2026), 29% p.a. interest, a S$100 late fee if you miss the minimum payment, and income requirements of S$30,000 for Singaporeans and PRs or S$60,000 for foreigners (age 21 to 65).
| Monthly local non-Grab spend | Mari Credit Card (1.5%) | GXS Credit Card (1.75%, min S$500) | Winner (year 1) |
|---|---|---|---|
| S$300 | S$4.50 | S$0.00 | Mari |
| S$500 | S$7.50 | S$8.75 | GXS |
| S$1,000 | S$15.00 | S$17.50 | GXS |
| S$2,000 | S$30.00 | S$35.00 | GXS |
Source: TKN calculation using cashback rates published by MariBank and GXS Bank, verified 7 October 2026. Excludes Grab and Singtel spend and ineligible transaction categories.
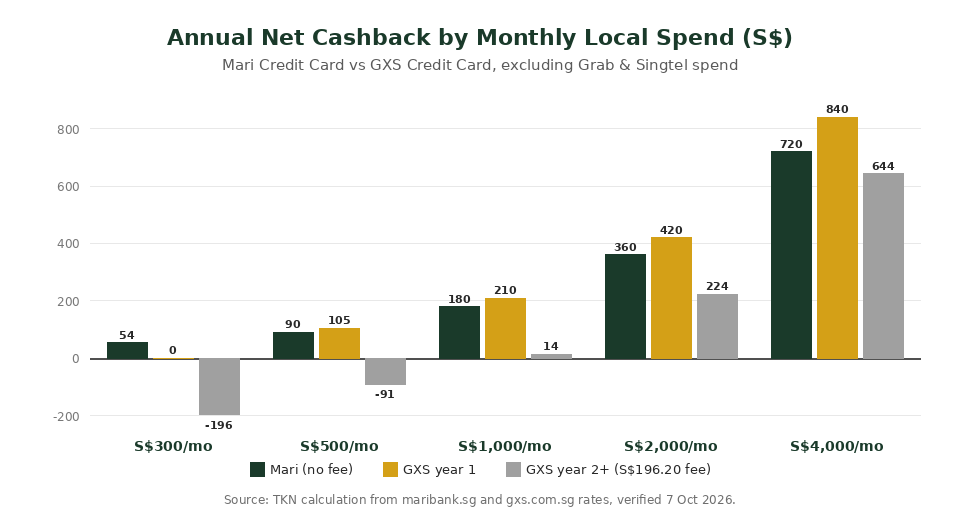
The year-two catch: once the GXS annual fee kicks in, the 0.25 percentage-point cashback edge has to cover S$196.20. That needs about S$78,480 a year (roughly S$6,540 a month) of eligible local spend just to break even with the Mari card. At S$1,000 a month, the Mari card earns S$180 a year against about S$13.80 net from GXS after the fee. The GXS card only pulls ahead for heavy Grab users, where 3% to 10% back in GrabCoins can easily outweigh the fee, or if GXS waives the fee again.
Fees, Transfers and Everyday Banking
Neither bank charges account fees. MariBank lists local transfers, fall-below fees and account opening all as free. GXS also advertises no minimum balance and no fees on its savings account. Both support PayNow and FAST transfers.
Overseas transfers favour MariBank. MariBank currently waives its overseas transfer fees under an “Unlimited $0 Transfers” promotion ending 31 December 2026, covering 21 currencies across more than 59 destinations, with instant transfers to China (Alipay, Weixin Pay, UnionPay), India, Thailand, Canada, Indonesia and the UK. If you send money home regularly, that is a meaningful saving.
Debit spending and Grab favour GXS. The GXS Debit Card gives an instant reward for every eligible spend of S$10 or more, charges no foreign transaction fees and adds no exchange-rate markup. Linking your GXS Savings Account to Grab earns up to 0.6% back in GrabCoins on eligible Grab payments. MariBank’s equivalent ecosystem tie-in is Shopee: you can check out or top up ShopeePay directly from your Mari Savings Account.
Overseas ATM withdrawals: the Mari Credit Card charges a 2% ATM withdrawal fee, but MariBank is waiving it on the first S$500 of overseas ATM withdrawals made between 14 October 2026 and 31 March 2027.
Eligibility is broad at both. MariBank accepts Singaporeans, PRs and foreigners with a valid pass aged 16 and above, with sign-up done via Singpass MyInfo. If you are also weighing Standard Chartered’s digital bank, see our Trust Bank vs MariBank comparison.
MariBank vs GXS: October 2026 Promotions
- GXS “Save + Invest” (ends 30 October 2026): deposit at least S$5,000 of fresh funds into a 4-month Boost Pocket named “BOOST4” and invest at least S$2,000 in a GXS Invest fund (excluding Cash Plus) to earn an effective 3% p.a. on the Boost Pocket. Invest S$10,000 or more and it rises to 3.2% p.a. The extra comes as cashback, capped at S$107 and S$300 respectively. You must hold the pocket to maturity and the investment till 28 February 2027, and your investment can lose value.
- GXS new-user “First Boost”: S$20 cashback when a new customer deposits S$5,000 into a 3-month Boost Pocket named “First Boost”, an effective 2.82% p.a. including the 1.22% p.a. Boost rate.
- GXS Credit Card Grab bundle (25 September to 31 October 2026): S$108 off Grab rides, food and groceries for new cardholders, while redemptions last.
- GXS referral: S$8 each for you and a friend when they open a GXS Savings Account and make a first S$500 deposit (ends 31 December 2026).
- MariBank welcome bonus: new Mari Savings Account users get an extra 1.60% p.a. for the first 30 days.
- MariBank overseas transfers: $0 transfer fees till 31 December 2026.
The GXS BOOST4 deal is the strongest headline in this comparison, but it is a savings-plus-investment bundle rather than a pure deposit rate. Treat the 3% as a bonus for money you were going to invest anyway, not as a reason to buy a fund.
Is Your Money Safe? SDIC and Licensing
Both are full digital banks licensed by the Monetary Authority of Singapore, and both are Deposit Insurance Scheme members. Singapore-dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation for up to S$100,000 in aggregate per depositor per Scheme member. Because MariBank and GXS are separate Scheme members, splitting cash between them gives up to S$200,000 of combined cover. Investment products (Mari Invest, GXS Invest) are not covered.
MariBank or GXS Bank: Who Should Pick Which?
Choose MariBank if you…
- Want one flexible account with no pockets to manage and no lock-in
- Already pay for ShopeeVIP or can credit your salary (1.48% p.a. with full liquidity)
- Spend under S$500 a month on a card, or want a no-annual-fee cashback card for life
- Send money overseas regularly
Choose GXS Bank if you…
- Have savings you will not touch for 4 to 12 months (1.40% to 1.75% p.a.)
- Are a heavy Grab user who can benefit from GrabCoins tiers
- Are already investing and can use the BOOST4 promotion before 30 October 2026
- Like organising goals into separate named pockets
For most people, the practical answer is both: an emergency fund at MariBank for instant access, and a GXS Boost Pocket ladder for money with a known date, such as an annual insurance premium or a holiday. Before you commit, run your numbers through our Singapore retirement planning calculator to see how much cash you really need to keep liquid. For the wider three-way picture including Trust Bank, read our guide to the best digital bank in Singapore, or go deeper on one bank with our complete GXS Bank guide.
Not financial advice. The Kopi Notes may earn a referral reward if you sign up with the codes on this page. Rates are verified as at 7 October 2026 and can change without notice.
Frequently Asked Questions
MariBank vs GXS: which is better for savings in 2026?
It depends on whether you need access to the money. As at 7 October 2026, MariBank pays 0.88% p.a. on all balances with no lock-in, or 1.48% p.a. if you are a ShopeeVIP member who credits salary. GXS Bank pays up to 1.75% p.a. on a 12-month Boost Pocket, but the bonus portion is only paid at maturity. For flexible cash, MariBank; for money you can lock away, GXS.
What is the GXS Boost Pocket interest rate?
GXS Boost Pockets pay a 0.88% p.a. base credited daily plus a bonus at maturity. As at 7 October 2026 the total rates are 1.01% p.a. (1 month), 1.22% (3 months), 1.40% (4 months), 1.30% (8 months) and 1.75% (12 months). You can open up to eight Boost Pockets.
How does MariBank reach 3.08% p.a.?
The 3.08% p.a. combines the 0.88% p.a. base, a 1.60% p.a. new-user bonus for the first 30 days, 0.40% p.a. for ShopeeVIP members and 0.20% p.a. for salary crediting. After the first 30 days, the most an existing customer can earn is 1.48% p.a.
Is my money safe in MariBank and GXS Bank?
Yes, within limits. Both are MAS-licensed digital banks and SDIC Deposit Insurance Scheme members, so Singapore-dollar deposits are insured up to S$100,000 per depositor at each bank. Holding money at both gives up to S$200,000 of combined cover. Investment products such as Mari Invest and GXS Invest are not insured.
Mari Credit Card or GXS Credit Card: which gives more cashback?
Below S$500 a month of local spend, the Mari Credit Card wins because the GXS card pays no base cashback until you hit S$500. Above S$500, GXS pays 1.75% versus Mari’s 1.5%, but from the second year the GXS card’s S$196.20 annual fee usually wipes out that edge unless you spend heavily on Grab, where GXS pays 3% to 10% in GrabCoins.
Can I open both a MariBank and a GXS account?
Yes. They are separate banks, so you can hold accounts at both. Many Singaporeans keep an emergency fund at MariBank for instant access and use GXS Boost Pockets for money set aside for a fixed date. Note that GXS lets each applicant hold either the GXS Credit Card or the GXS FlexiCard, not both.
Does the GXS Credit Card have an annual fee?
Yes. The GXS Credit Card’s annual fee is S$196.20 including GST, waived for the first year for customers approved by 31 December 2026. The Mari Credit Card has no annual fee.
Open Both and Let Each Do Its Job
Use MariBank referral code 2DCT80WQ or GXS Bank referral code YONG477 when you sign up. Check each page for the latest referral reward.
Disclaimer: This article was researched and drafted with AI assistance and reviewed against official MariBank and GXS Bank sources as at 7 October 2026. It is for general information only and does not constitute financial advice. Interest rates, cashback rates, fees and promotions are set by the banks and may change at any time. Always read the latest terms in the MariBank and GXS Bank apps before making a decision.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.