GXS Bank BOOST4 Promotion (October 2026): Earn Up to 3.2% p.a.
A limited-time “Save and Invest” campaign from Singapore’s GXS Bank — valid until October 30, 2026.
GXS Bank is running a “Save and Invest” promotion through October 30, 2026, where Singapore residents can earn up to 3.2% p.a. by creating a 4-month Boost Pocket named “BOOST4” (minimum S$5,000) and investing at least S$2,000 in GXS Invest funds. This is nearly double GXS’s standard 1.75% p.a. Boost Pocket rate — but it comes with conditions worth understanding before you switch.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
Table of Contents
What Is the GXS BOOST4 Promotion?
GXS Bank — Singapore’s digital bank backed by Grab and Singtel, and one of only three MAS-licensed digital full banks in Singapore — is running a “Save and Invest” campaign that significantly boosts the returns on its Boost Pocket savings feature.
Ordinarily, GXS’s Boost Pocket pays up to 1.75% p.a. when you lock in a 12-month fixed-term pocket, made up of a 0.88% p.a. base rate credited daily plus a bonus upon maturity. The standard main savings account earns just 0.88% p.a. — fully flexible, no minimum balance, no lock-in required.
The BOOST4 promotion changes the equation considerably. Through October 30, 2026, GXS is offering an effective rate of 3% to 3.2% p.a. when you combine a specific savings pocket with an investment in their GXS Invest platform. The mechanics are straightforward, but one rule is strict: you must name your pocket exactly “BOOST4” (all capitals, no spaces or punctuation) for the promotional rate to activate.
Crucially, the promotional interest rate is separate from any returns your GXS Invest funds generate. You earn both — the 3%+ promotional cashback on your Boost Pocket, plus whatever your chosen GXS Invest funds return (or lose). This means the effective total yield can exceed 3.2% if markets cooperate, but the 3.2% figure is what GXS guarantees on the savings pocket component alone.
For context on GXS Bank’s full product range — including its FlexiLoan and GXS+ Card — see the GXS Bank Singapore complete guide, which covers the bank’s standard features in depth. This article focuses specifically on the October 2026 BOOST4 promotion and whether it represents a genuine improvement for savers.
How to Set It Up (Step-by-Step)
Setting up the BOOST4 promotion takes about five minutes in the GXS app. Here is the exact process as at October 2026:
Step 1: Open the GXS app and go to Savings. Tap the “Savings” tab on the GXS home screen. You will see your main account balance and any existing Saving Pockets or Boost Pockets.
Step 2: Create a new Boost Pocket. Tap “Create Boost Pocket.” When prompted for tenure, select exactly 4 months. Other tenures (1, 3, 8, or 12 months) do not qualify for this promotion.
Step 3: Name it exactly “BOOST4”. In the name field, enter BOOST4 in capitals — no spaces, no lowercase letters, no punctuation. The GXS system uses this name as the promotion trigger. Any variation will default to the standard Boost Pocket rate.
Step 4: Deposit the minimum amount. Transfer a minimum of S$5,000 into the BOOST4 pocket. Depositing more may qualify you for the higher 3.2% p.a. tier (check the GXS app for current tier thresholds, which may be updated).
Step 5: Invest in GXS Invest. Navigate to “Invest” in the GXS app and invest at least S$2,000 in any GXS Invest fund, excluding the Cash Plus fund. This is the second qualifying condition for the promotional rate.
Step 6: Wait for pocket maturity. The promotional cashback is credited to your account upon pocket maturity at the 4-month mark. The base interest (0.88% p.a.) continues to be credited daily. Your GXS Invest holdings trade separately and can be redeemed per their fund terms.
Important: Both the BOOST4 pocket creation and the GXS Invest investment must be completed before October 30, 2026. The pocket itself can mature after the promotion end date, and the cashback will still be credited at maturity.
The 3% vs 3.2% Tiers Explained
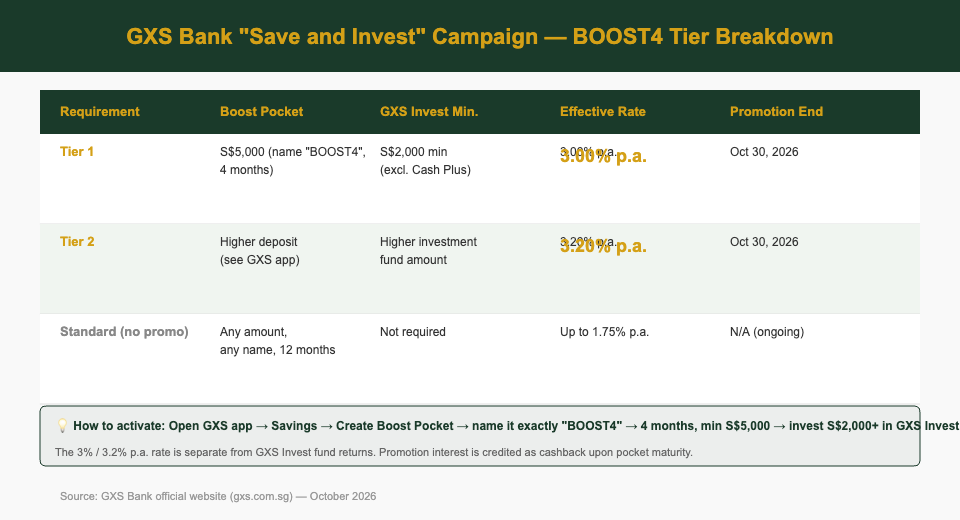
The BOOST4 promotion operates across two tiers. Here is the breakdown of each:
| Tier | Boost Pocket Min. | GXS Invest Min. | Effective Rate | Lock-in |
|---|---|---|---|---|
| Tier 1 | S$5,000 (name “BOOST4”, 4 months) | S$2,000 (excl. Cash Plus) | 3.00% p.a. | 4 months |
| Tier 2 | Higher deposit (see GXS app) | Higher investment amount | 3.20% p.a. | 4 months |
| Standard (no promo) | Any amount, any name | Not required | Up to 1.75% p.a. | 1–12 months |
Source: GXS Bank official website (gxs.com.sg), October 2026. Verify current tier thresholds in the GXS app before applying.
On a practical basis: Tier 1 (3% p.a.) is accessible for most savers with S$5,000 available for a 4-month commitment and S$2,000 for investment. To illustrate with a worked example — a Singapore saver deposits S$10,000 in a BOOST4 pocket at 3% p.a. for 4 months. The promotional interest earned is approximately S$100 (S$10,000 × 3% × 4/12), credited as cashback at maturity. Any GXS Invest returns on the S$2,000 are additional and separate.
Tier 2 (3.2% p.a.) adds a modest 0.2 percentage point uplift for those with larger deposits or investments. On S$20,000 at 3.2% for 4 months, the promotional return would be approximately S$213 — a meaningful sum for short-duration savings. Check the GXS app for the exact Tier 2 thresholds, as these are subject to update by GXS.
GXS BOOST4 vs MariBank vs Trust Bank: October 2026 Comparison
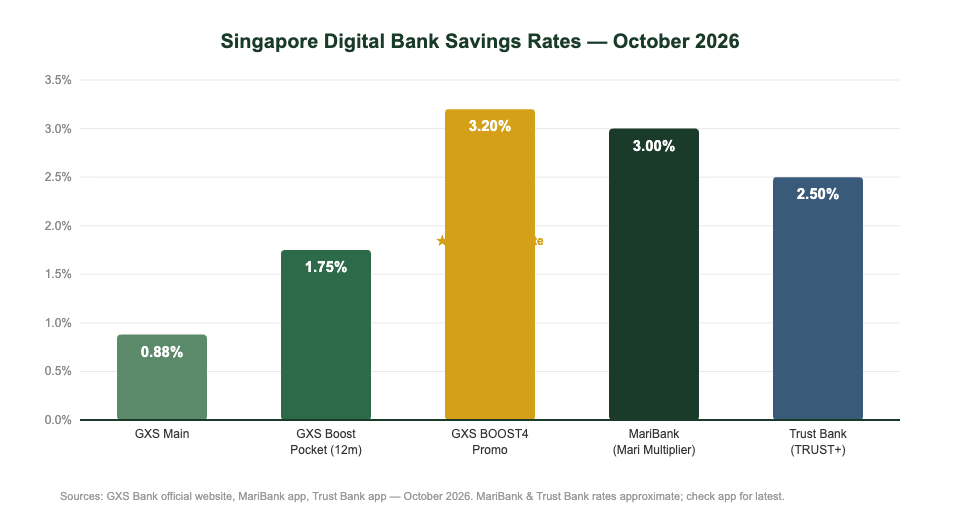
How does the BOOST4 rate compare to Singapore’s other MAS-licensed digital banks? The table below gives the key comparison for October 2026. For those who prefer government-backed returns instead, consider the Singapore T-bills 2026 guide and the Singapore Savings Bonds guide.
| Bank | Product | Rate (Oct 2026) | Conditions | Lock-In |
|---|---|---|---|---|
| GXS Bank | Main Savings | 0.88% p.a. | None — fully flexible | None |
| GXS Bank | Boost Pocket (12m, standard) | Up to 1.75% p.a. | 12-month term | 12 months |
| GXS Bank ★ | BOOST4 Promo (Oct 2026) | 3.00%–3.20% p.a. | Name pocket “BOOST4”, min S$5,000 + invest S$2,000 in GXS Invest | 4 months |
| MariBank | Mari Savings (Mari Multiplier) | Up to ~3.00% p.a. | Tiered multipliers based on eligible transactions | None |
| Trust Bank | TRUST+ Savings | Up to ~2.50% p.a. | Tiered based on spend and NTUC FairPrice transactions | None |
Sources: GXS Bank official website (gxs.com.sg); MariBank and Trust Bank rates are approximate as at October 2026 — verify in each bank’s app for the latest figures before switching.
Key insight: GXS BOOST4 at 3%–3.2% p.a. is the highest headline savings rate among Singapore’s digital banks in October 2026 — but it requires commitment (4-month lock-in) and an investment component. MariBank’s rate is comparable with no lock-in but requires active transaction behaviour to achieve. Trust Bank suits frequent NTUC shoppers. The “best” choice depends on your habits and flexibility needs.
If you are planning for longer-term wealth building, generating passive income in Singapore through REITs or ETFs alongside your digital bank savings can significantly improve total returns. Use our Singapore retirement calculator to see how different savings rates compound over time.
Is Your Money Safe? SDIC Insurance Explained
GXS Bank holds a full digital bank licence issued by the Monetary Authority of Singapore (MAS) — the highest tier of digital banking licence available in Singapore, which allows it to take deposits from the general public. As an MAS-licensed full bank, GXS is a member of the Singapore Deposit Insurance Corporation (SDIC).
Deposits in your GXS Savings Account and all Boost Pockets — including BOOST4 — are insured up to S$100,000 per depositor per scheme member. This is the same protection level you get at DBS, OCBC, or UOB. If GXS Bank were to fail, SDIC would reimburse your deposits up to S$100,000 — an extremely low-probability scenario given its MAS oversight and the financial backing of Grab and Singtel.
What SDIC does not cover: your GXS Invest fund units. Investment products are not deposits. They can fall in value and are not protected by deposit insurance. The 3%–3.2% promotional cashback itself is earned on the savings pocket (SDIC-protected), but your S$2,000 GXS Invest holding carries market risk.
| Component | SDIC Protected? | Notes |
|---|---|---|
| GXS Main Savings Account | Yes | Up to S$100,000 per depositor |
| GXS Boost Pocket (incl. BOOST4) | Yes | Included in the S$100,000 limit above |
| GXS Invest Fund Units | No | Investment product — not a deposit; market risk applies |
Source: Singapore Deposit Insurance Corporation (sdic.org.sg) and Monetary Authority of Singapore (mas.gov.sg), October 2026
Who Should Use the BOOST4 Promotion?
The BOOST4 promotion is genuinely attractive — but it is not the right fit for every saver. Here is a clear breakdown:
GXS BOOST4 is well-suited if you:
- Have at least S$5,000 of liquid savings you can comfortably lock away for 4 months (while keeping a separate emergency fund untouched)
- Are comfortable investing S$2,000 in unit trusts via GXS Invest and can tolerate some short-term market fluctuation on that investment component
- Already use GXS Bank or are open to signing up (referral code YONG477 for a sign-up bonus)
- Prefer a 4-month commitment over a 12-month lock-in — BOOST4 offers a shorter timeline than the standard peak-rate Boost Pocket
- Want a MAS-licensed, SDIC-protected digital bank with daily interest crediting and no fees
Consider alternatives if you:
- Need your savings fully accessible at all times — the 4-month lock-in means you forfeit the promotional cashback if you break early
- Are not comfortable with any investment risk and want a pure savings rate with no investment condition
- Have more than S$100,000 to place at a single institution — amounts above the SDIC limit should be spread across multiple banks
- Prefer government-guaranteed returns — Singapore T-bills and Singapore Savings Bonds offer capital security that digital bank promotions do not
For savers who want the best of both worlds — short-term liquidity and competitive returns — one practical approach is to split funds: put S$5,000–S$10,000 into the GXS BOOST4 pocket for the 4-month period, and keep remaining liquid savings in a no-lock-in account such as MariBank or a high-yield account at a traditional bank. Separately, consider whether S$2,000 invested in GXS Invest aligns with your broader investment strategy and risk appetite.
Frequently Asked Questions
What is the GXS Bank BOOST4 promotion?
The GXS Bank BOOST4 promotion is part of a “Save and Invest” campaign running through October 30, 2026. Create a 4-month Boost Pocket named exactly “BOOST4” with a minimum deposit of S$5,000, and invest at least S$2,000 in GXS Invest funds (excluding Cash Plus) — and GXS credits you with an effective 3.00% to 3.20% p.a. as cashback upon pocket maturity. The promotional rate is separate from any returns on your GXS Invest holdings.
Is GXS Bank covered by SDIC deposit insurance?
Yes. GXS Bank holds a full digital bank licence from MAS and is an SDIC member. Deposits in your GXS Savings Account and Boost Pockets (including BOOST4) are insured up to S$100,000 per depositor. Your GXS Invest fund holdings are not SDIC-protected — they are investment products subject to market risk.
What if I don’t name my pocket exactly ‘BOOST4’?
Any name other than the exact string “BOOST4” (capitals, no spaces) will give you the standard Boost Pocket rate for your chosen tenure — not the promotional 3%–3.2% rate. You cannot rename an existing pocket; you must create a new one with the correct name. Double-check before confirming your pocket creation in the GXS app.
Can I withdraw from my BOOST4 pocket early?
Breaking a Boost Pocket early typically forfeits the bonus interest. You would receive only the base rate (0.88% p.a.) credited daily up to the withdrawal date, and the promotional cashback would not be paid. For funds you may need urgently, keep a separate liquid buffer in your main GXS Savings Account or in another flexible account. Check the GXS app’s current terms for the precise early withdrawal policy, as GXS may update these conditions.
Which GXS Invest funds qualify? What about Cash Plus?
Any GXS Invest fund qualifies for the minimum S$2,000 investment condition, except the Cash Plus fund. Cash Plus is excluded because it functions similarly to a money market deposit rather than a true investment fund. You must invest in one of the standard unit trust options in GXS Invest. These carry market risk, so choose a fund that matches your risk appetite — the S$2,000 invested is at market risk, separate from your SDIC-protected Boost Pocket.
How does GXS BOOST4 compare to MariBank and Trust Bank in October 2026?
With the BOOST4 promotion, GXS Bank offers one of the highest short-term savings rates among Singapore’s digital banks in October 2026 (3.00%–3.20% p.a.) — but it requires locking in funds for 4 months and investing S$2,000 in GXS Invest. MariBank’s Mari Multiplier can reach approximately 3% p.a. with no lock-in, making it competitive for those who prefer flexibility. Trust Bank’s TRUST+ Savings offers around 2.5% p.a., suited to NTUC FairPrice shoppers. The best choice depends on your spending habits, risk tolerance, and whether you want lock-in flexibility.
When does the GXS BOOST4 promotion end? Can I still benefit after Oct 30?
The BOOST4 promotion requires both your pocket creation and your GXS Invest investment to be in place before October 30, 2026. However, since the pocket runs for 4 months, a pocket created in late October 2026 would mature in approximately late February 2027 — and the promotional cashback is still credited at maturity, even after the campaign end date. After October 30, check the GXS app for any new promotions GXS may launch.
Make Your Money Work Harder in Singapore
Explore digital bank rates, savings bonds, T-bills, and long-term investment strategies.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.