Mapletree Logistics Trust Share Price 2026: China Asset Recycling and India Expansion — DPU Impact Analysis
Mapletree Logistics Trust (SGX: M44U) is Singapore’s third-largest logistics REIT with 185 properties spanning eight Asia-Pacific countries. As at September 2026, MLT trades at approximately S$1.28 per unit, yielding around 5.67% based on FY2025/26 DPU of 7.262 Singapore cents. Management is actively recycling S$100–150 million in non-core China and Hong Kong SAR assets while targeting higher India allocation — a strategic pivot that could support DPU recovery through FY2026/27.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
Table of Contents
What Is Mapletree Logistics Trust (MLT)?
Mapletree Logistics Trust (SGX: M44U) was listed on the Singapore Exchange in August 2005 and is managed by Mapletree Investments Pte Ltd, a wholly-owned subsidiary of Temasek Holdings. MLT is Singapore’s first listed logistics REIT and one of Asia’s largest, with a portfolio spanning eight countries: Singapore, Australia, China, Japan, Hong Kong SAR, Malaysia, Vietnam, and India.
As at FY2025/26 (year ended 31 March 2026), MLT’s portfolio comprised 185 properties with an estimated gross floor area exceeding 11 million square metres. The trust’s assets under management (AUM) are estimated at approximately S$13.5 billion. MLT serves over 600 tenants including e-commerce platforms, third-party logistics providers, consumer goods companies, and manufacturers.
MLT offers Singapore investors exposure to Asia-Pacific logistics demand — a structural growth theme underpinned by e-commerce expansion, supply chain diversification, and infrastructure investment across the region. For investors building passive income in Singapore, MLT’s 5.67% indicative yield represents meaningful income at current prices.
| Metric | Value |
|---|---|
| SGX Ticker | M44U |
| Listing Year | 2005 |
| Number of Properties | 185 |
| Countries | 8 |
| Estimated AUM | ~S$13.5 billion |
| Portfolio Occupancy | 96.9% |
| Gearing | ~37–38% |
| Manager | Mapletree Investments Pte Ltd (Temasek) |
Source: Mapletree Logistics Trust, The Kopi Notes analysis, September 2026
MLT China Asset Recycling Plan: What the S$100–150 Million Divestment Means
In its FY2025/26 results briefing, MLT’s management identified S$100–150 million in non-core logistics assets for divestment — primarily concentrated in China’s second and third-tier cities and Hong Kong SAR. This recycling initiative is a deliberate strategic response to structural headwinds in the China logistics market.
Why Is MLT Divesting China Assets?
China’s logistics sector faces three converging pressures: (1) an oversupply of grade-B warehouse space in inland cities as post-pandemic construction outpaced demand, (2) a slower-than-expected consumer spending recovery, and (3) persistent negative rental reversions in select submarkets. While MLT’s China portfolio occupancy has remained resilient through active leasing, rental rates have been under pressure.
By divesting lower-yielding China and HK SAR assets, MLT achieves three strategic outcomes:
- Portfolio quality improvement — Exiting assets with soft rental reversions raises the blended reversion profile. Outside China, MLT achieved positive reversions of +4.2% in FY2025/26; removing the China drag accelerates the overall portfolio’s reversion recovery.
- Capital recycling to higher-growth markets — Divestment proceeds will fund acquisitions in India (highest organic logistics demand growth in Asia) and asset enhancement initiatives (AEIs) in Singapore’s premium logistics hubs.
- Gearing headroom for acquisitions — Asset sales reduce the existing portfolio base, allowing MLT to stay comfortably below MAS’s 50% aggregate leverage cap while pursuing accretive external growth.
The S$100–150 million divestment is modest relative to MLT’s estimated S$13.5 billion AUM (approximately 1%). If assets are recycled above book value — as has been the case in prior MLT divestments — any gains may be distributed to unitholders, providing a near-term DPU uplift.
See how this compares to other Singapore REIT strategies in our roundup of the best S-REITs in Singapore 2026.
India Expansion: MLT’s Next Growth Engine
India represents MLT’s single largest growth opportunity over the next three to five years. Three structural tailwinds are driving unprecedented demand for modern logistics facilities across the subcontinent.
Three Tailwinds Driving India Logistics Demand
1. Manufacturing “China+1” shift: Global companies accelerating supply chain diversification away from China have chosen India as a primary alternative. Apple, Samsung, and major electronics manufacturers have significantly expanded India production since 2023, driving demand for premium warehouse and logistics facilities near industrial clusters in Pune, Chennai, and Bengaluru.
2. E-commerce fulfilment boom: India’s e-commerce market is growing rapidly with platforms including Flipkart, Meesho, and Amazon India requiring extensive fulfilment and last-mile logistics infrastructure. Modern, grade-A warehouses with high-bay racking, dock levellers, and cold storage capability are in chronic undersupply across India’s Tier 1 and emerging Tier 2 cities.
3. Government infrastructure investment: India’s National Infrastructure Pipeline (NIP) is improving logistics connectivity across road, rail, and multimodal parks, materially reducing operating costs for logistics providers and enhancing the attractiveness of modern warehouse assets as long-term investments.
MLT’s India Target Allocation
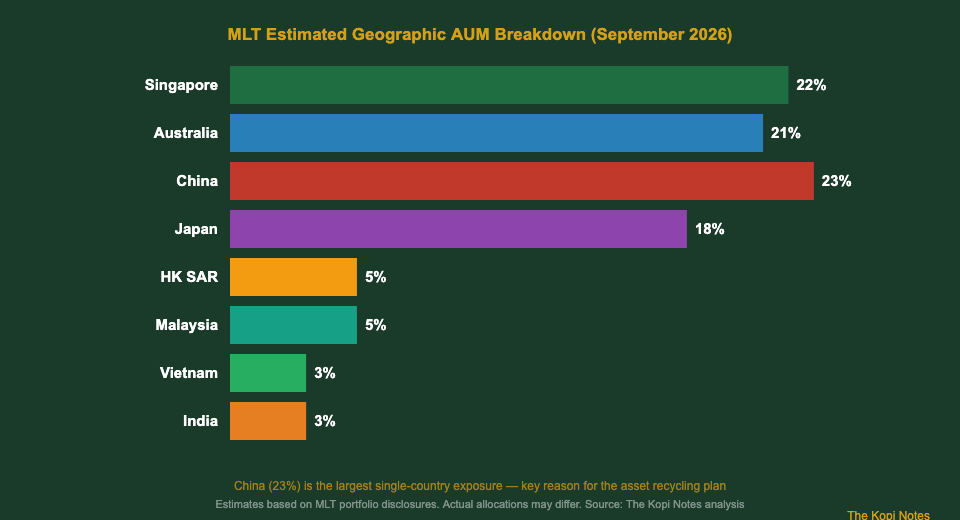
MLT currently holds approximately 3% of estimated AUM in India — a deliberately conservative starting position. Management has signalled a medium-term target to grow India’s share to potentially 8–10% of AUM. Based on an estimated current AUM of S$13.5 billion, this implies S$700 million to S$900 million in India-focused acquisitions over the medium term.
This India pivot differentiates MLT from peers in the Singapore REIT ETF universe and from other Singapore-listed logistics REITs. If executed successfully, India could become a meaningful DPU growth driver by FY2028/29. Investors interested in building long-term retirement income through S-REITs may find the India optionality compelling — see our Singapore retirement planning calculator to model projected REIT income scenarios.
FY2025/26 DPU Analysis: Is the Distribution Sustainable?
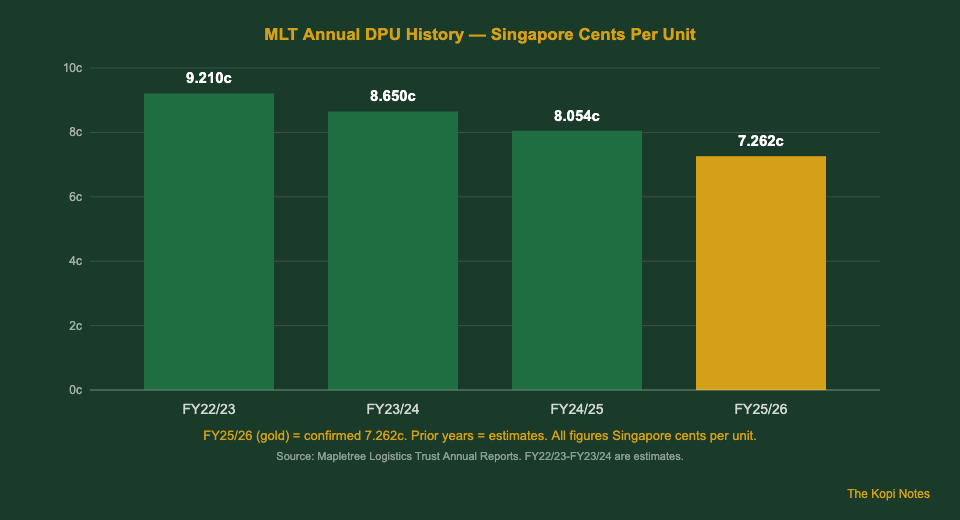
MLT reported FY2025/26 (year ended 31 March 2026) full-year DPU of 7.262 Singapore cents, a decline of 9.8% year-on-year. At face value this appears steep — but context is essential.
The FY2024/25 DPU included non-recurring divestment gains that inflated the prior year’s distribution. Stripping these out, operating DPU declined only 3.4% — reflecting broadly stable underlying performance from a 96.9%-occupied, 185-property portfolio. Quarterly DPU was stable quarter-on-quarter through FY2025/26 at approximately 1.82 cents per unit.
At approximately S$1.28 (September 2026), the FY2025/26 DPU of 7.262 cents implies a distribution yield of approximately 5.67% — a 375-basis-point premium over Singapore 6-month T-bills at 1.92%. For context on current T-bill rates, see our Singapore T-bills 2026 guide.
| Year | DPU (cents) | Notes |
|---|---|---|
| FY2022/23 | 9.21 (est.) | Near-peak logistics demand |
| FY2023/24 | 8.65 (est.) | China headwinds begin |
| FY2024/25 | ~8.054 (implied) | Includes one-off divestment gains |
| FY2025/26 | 7.262 (confirmed) | Operating DPU down 3.4% ex-gains; quarterly DPU stable |
Source: Mapletree Logistics Trust Annual Reports. FY22/23–FY23/24 figures are estimates. Past distributions are not indicative of future returns.
Portfolio Metrics: Occupancy, Reversions, and Gearing
Portfolio Occupancy: 96.9% — A high occupancy rate reflects healthy demand for MLT’s grade-A logistics facilities across Asia-Pacific. Outside China, occupancy is even stronger.
Rental Reversions: The reversion rate (change in rent on lease renewals) reveals MLT’s pricing power. In FY2025/26, ex-China reversions were a healthy +4.2%, while China reversions remained negative but showed a moderating trend — expected to turn flat to slightly positive in FY2026/27 as the market absorbs excess supply.
| Metric | Value | Context |
|---|---|---|
| Portfolio Occupancy | 96.9% | Q4 FY2025/26 |
| Rental Reversion (ex-China) | +4.2% | FY2025/26 full year |
| China Rental Reversion | Negative, moderating | Improving trend QoQ |
| Gearing | ~37–38% | MAS 50% regulatory limit |
| WALE | ~3.5 years | Weighted average lease expiry |
Source: Mapletree Logistics Trust FY2025/26 Results, The Kopi Notes
MLT Share Price and Valuation: Is It a Buy at S$1.28?
At approximately S$1.28 per unit (September 2026), MLT presents the following valuation profile:
| Metric | Value | Notes |
|---|---|---|
| Share Price | ~S$1.28 | As at September 2026 |
| FY25/26 DPU | 7.262 Singapore cents | Confirmed; operating DPU -3.4% ex-gains |
| Distribution Yield | ~5.67% | At S$1.28; indicative only |
| Estimated NAV/unit | S$1.40–1.45 | Estimate; varies by analyst |
| P/NAV | ~0.88–0.90x | Modest discount to book |
| vs. Singapore T-Bill Yield | +375 bps premium | T-bill at 1.92% (Sep 2026) |
Source: The Kopi Notes estimates. Past performance and historical distributions are not indicative of future results.
At 0.88–0.90x estimated NAV, MLT trades at a modest discount to book value — reflecting the market’s caution around China exposure and the pace of DPU recovery. In contrast, REITs with no China exposure or clear DPU growth visibility tend to trade at or above NAV. The discount creates a potential margin of safety for long-term investors, though execution of the China divestment plan and the India ramp-up remains key to unlocking value.
The 375-basis-point yield premium over Singapore T-bills (1.92% as of September 2026) is noteworthy. With Singapore T-bill rates declining through the rate-cut cycle, the relative attractiveness of a 5.67% REIT yield improves as the risk-free benchmark falls. Investors who need income and can accept the volatility inherent in listed REITs may find the risk-reward compelling at current levels.
Where to Buy Mapletree Logistics Trust (M44U) in Singapore
Singapore investors can access MLT directly on the SGX, or through managed platforms that include S-REIT exposure in diversified income portfolios. Below are three options worth considering:
Frequently Asked Questions About Mapletree Logistics Trust
What is Mapletree Logistics Trust (MLT)?
What is MLT's share price in September 2026?
What is MLT's DPU for FY2025/26?
Why is MLT selling China assets?
How does MLT's yield compare to Singapore T-bills?
What is MLT's gearing ratio?
Why is MLT expanding into India?
Can I invest in MLT through CPF or SRS?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.