Best Bank for Digital Banking Singapore (2026): GXS, MariBank & Trust Bank Compared
All three MAS-licensed digital banks compared — interest rates, conditions, SDIC coverage, and which one suits your lifestyle.
Singapore has three main digital banks you can use today: GXS Bank, MariBank, and Trust Bank. All three are MAS-licensed and covered by SDIC deposit insurance up to S$100,000. GXS Bank is best if you want hassle-free daily interest with no conditions. MariBank suits Shopee users who can stack welcome bonuses. Trust Bank rewards you most if you credit your salary and refer friends to their credit card.
Not financial advice. All figures are for educational reference only. Data verified as at 25 September 2026.
- GXS Bank earns 0.88% p.a. base with no salary or card conditions — good for no-fuss savers.
- MariBank earns up to 3.08% p.a. for new users stacking all bonuses, but the base is just 0.88% p.a. once promotions end.
- Trust Bank offers up to 2.40% p.a. but requires specific actions like referring a friend or investing S$20,000.
- All three are SDIC-insured up to S$100,000 — your money is as safe as it is in a traditional bank.
Table of Contents
Contents — Click to expand
- What Is a Digital Bank in Singapore?
- Savings Rates Compared: GXS vs MariBank vs Trust Bank
- GXS Bank: Best for No-Fuss Daily Interest
- MariBank: Best for Shopee Users
- Trust Bank: Best for Credit Card Rewards
- Which Digital Bank Should You Choose?
- Are Digital Banks Safe in Singapore?
- Frequently Asked Questions
What Is a Digital Bank in Singapore?
A digital bank operates entirely online — no physical branches, no over-the-counter service, and no queues. You open an account, deposit funds, and manage everything through a mobile app.
Singapore’s Monetary Authority of Singapore (MAS) first issued digital bank licences in 2020. Today, there are five MAS-approved digital banks. Three of them serve retail customers like you: GXS Bank, MariBank, and Trust Bank.
The other two — ANEXT Bank and Green Link Digital Bank — hold Digital Wholesale Bank licences and serve businesses only. So for everyday savings and personal banking, your real options are GXS, MariBank, and Trust Bank.
Here’s what makes digital banks different from traditional banks like DBS, OCBC, and UOB:
- No branch visits — everything is done through the app
- Lower overhead costs — which can translate into better savings rates
- Often tied to an ecosystem — GXS is linked to Grab and Singtel, MariBank to Shopee, Trust Bank to FairPrice and Standard Chartered
- Same SDIC protection — your deposits up to S$100,000 are insured, just like at a traditional bank
Savings Rates Compared: GXS vs MariBank vs Trust Bank
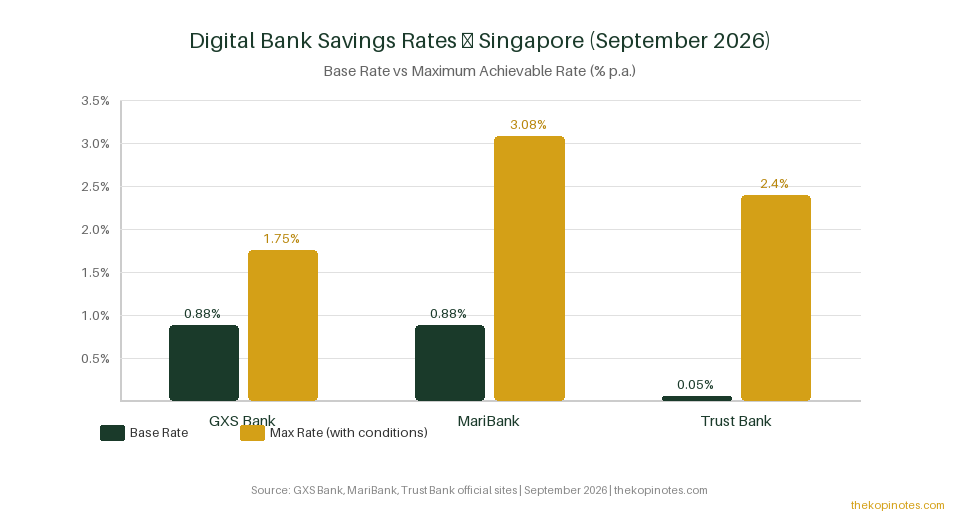
Let’s cut straight to the rates. Here’s how the three digital banks stack up as at September 2026:
| Bank | Base Rate | Max Rate | Key Conditions for Max |
|---|---|---|---|
| GXS Bank | 0.88% p.a. | 1.75% p.a. | Lock funds in Boost Pocket (1–12 months) |
| MariBank | 0.88% p.a. | 3.08% p.a.* | New user welcome bonus + ShopeeVIP + salary credit |
| Trust Bank | 0.05% p.a. | 2.40% p.a. | Refer credit card user + invest S$20K + salary credit |
*MariBank 3.08% p.a. for new users in first 30 days combining welcome bonus (+1.60%), ShopeeVIP bonus (+0.40%), and salary credit bonus (+0.20%). Standing rate after promotional period: 0.88% p.a. (or higher with ongoing ShopeeVIP and salary credit). Source: MariBank official rates, September 2026.
A few important things to understand about these numbers:
The base rate is what you earn without doing anything extra. For GXS and MariBank, that’s a tied 0.88% p.a. Trust Bank’s base is very low at just 0.05% p.a. — don’t rely on it if you can’t meet the bonus conditions.
The max rate requires specific actions. MariBank’s 3.08% is only for new users in the first 30 days. After that, the effective rate drops significantly unless you maintain ShopeeVIP status and credit your salary. For everyday users who don’t shop on Shopee, the long-term rate is closer to 0.88%–1.08%.
For a concrete example: if you park S$20,000 in a GXS Saving Pocket at 1.08% p.a., you’d earn roughly S$216 in interest over 12 months — with no conditions to meet. That’s S$18 a month just for letting your money sit there.
GXS Bank: Best for No-Fuss Daily Interest
GXS Bank is Singapore’s first digital full bank, backed by Grab and Singtel. It launched in 2022 and has been quietly growing its user base, particularly among Grab users and Singtel subscribers.
Here’s what makes GXS stand out: it doesn’t ask you to jump through hoops. No salary crediting. No minimum card spend. No referring friends. You just deposit money and earn daily interest, credited to your account every day.
The GXS account has two tiers:
- Main Account: 0.88% p.a. — your everyday wallet for spending and transfers
- Saving Pockets: 1.08% p.a. — set aside separate savings pools for specific goals
- Boost Pockets: Up to 1.75% p.a. — lock your money for a fixed tenure (1, 3, 4, 8, or 12 months)
GXS is a natural fit if you’re already a Grab or Singtel customer. The integration is seamless — top-up your GXS account from GrabPay, or use Singtel billing options. However, you don’t need to be a Grab or Singtel user to open an account.
Who GXS suits best: Anyone who wants simple, no-conditions daily interest without worrying about monthly requirements. Also ideal for people who want to park emergency funds they may need to access quickly — Boost Pockets can be broken early if needed.
Get started with the GXS Bank referral code YONG477 for sign-up bonuses on your first deposit.
MariBank: Best for Shopee Users
MariBank is Sea Group’s digital full bank — Sea is the parent company behind Shopee, SeaMoney, and Garena. If you’re a regular Shopee shopper, MariBank is probably the most rewarding digital bank for you.
MariBank’s rate structure is straightforward:
- Base rate: 0.88% p.a. — flat, no conditions
- ShopeeVIP bonus: +0.40% p.a. — if you’re a ShopeeVIP member
- Salary credit bonus: +0.20% p.a. — credit at least S$1,500 salary monthly
- Welcome bonus for new users: +1.60% p.a. — for the first 30 days after account opening
So as a new user who shops on Shopee and credits their salary, you’d earn 0.88% + 1.60% + 0.40% + 0.20% = 3.08% p.a. in your first month. After the welcome bonus expires, your ongoing rate is 1.48% p.a. (with ShopeeVIP and salary credit).
One unique MariBank feature: interest is calculated daily and credited the following day — not month-end. So you see your interest accumulate in real time. This is different from most banks where you wait until end of month.
MariBank also caps savings at S$100,000 per account — which aligns exactly with the SDIC limit. This cap means your entire balance is covered by deposit insurance at all times.
Use the MariBank referral code 2DCT80WQ when you sign up for a welcome bonus on your first deposit.
Trust Bank: Best for Credit Card Rewards
Trust Bank is a partnership between Standard Chartered and NTUC Enterprise. Unlike GXS and MariBank which hold Digital Full Bank licences, Trust Bank operates under a full bank licence — the same type as DBS and OCBC. In practice, this means Trust Bank has more regulatory flexibility and can offer a wider range of products.
Trust Bank’s savings product is called Trust+. Here’s how the bonus interest stacks:
- Base rate: 0.05% p.a.
- Refer a new Trust credit card customer: +1.20% p.a.
- Invest S$20,000 in TrustInvest: +0.70% p.a.
- Credit S$1,500 salary via GIRO: +0.45% p.a.
- Maximum total: 2.40% p.a.
Trust Bank’s big differentiator is its credit card. The Trust credit card offers cashback on FairPrice purchases and daily essentials, making it particularly useful for families who shop at FairPrice regularly. If you credit your salary to Trust Bank, you also benefit from the salary credit bonus.
However, the base rate of 0.05% p.a. is extremely low. If you’re parking money in Trust Bank and not meeting any bonus conditions, your money is essentially earning nothing. Trust Bank’s value comes from the full ecosystem — the credit card rewards combined with the savings account.
Sign up with the Trust Bank referral code HTWYQP95 for your sign-up rewards.
Which Digital Bank Should You Choose?
Here’s a quick decision framework based on your situation:
| If you… | Best choice | Why |
|---|---|---|
| Want simple interest, no conditions | GXS Bank | 0.88%–1.75% p.a. with no hoops |
| Shop on Shopee regularly | MariBank | ShopeeVIP bonus stacks on top of base rate |
| Shop at FairPrice, want credit card cashback | Trust Bank | Trust credit card + Trust+ savings work together |
| Are a new user maximising first-month returns | MariBank | Welcome bonus can push rate to 3.08% p.a. |
| Are a Grab user or Singtel subscriber | GXS Bank | Ecosystem integration, daily interest credits |
| Want to open ALL THREE for the welcome bonuses | All three | No rule against having multiple digital bank accounts |
Source: GXS Bank, MariBank, Trust Bank official websites | September 2026
One strategy worth considering: open all three digital bank accounts to capture all welcome bonuses, then consolidate to the one that suits your ongoing lifestyle. There’s no penalty for having multiple accounts, and the sign-up bonuses are essentially free money.
If you’re looking to put your savings to work beyond a savings account, you might also explore the Singapore retirement calculator to see how your savings rate compounds over time — and whether a slightly higher rate matters as much as you think over 10–20 years.
For savers who want higher fixed-income returns without salary conditions, the best savings accounts without salary credit guide compares digital banks alongside traditional bank options like OCBC 360 and UOB ONE.
Are Digital Banks Safe in Singapore?
Yes — all three digital banks are fully MAS-regulated and covered by the Singapore Deposit Insurance Corporation (SDIC). Your deposits of up to S$100,000 are protected by law, the same way they are at DBS, OCBC, or UOB.
GXS and MariBank hold Digital Full Bank licences issued by MAS in 2020. Trust Bank holds a full bank licence under its Standard Chartered parent. All three are subject to MAS’s core capital requirements, liquidity rules, and governance standards.
If any of these banks were to fail — an unlikely but non-zero event — the SDIC scheme guarantees your Singapore dollar deposits up to S$100,000 per depositor per institution. You don’t need to do anything; the protection is automatic.
A few practical safety tips:
- Don’t keep more than S$100,000 in any single digital bank account — the SDIC limit is per depositor per institution
- Enable all security features — 2FA, biometric login, and transaction alerts are available on all three apps
- Use official app stores only — download apps from the Apple App Store or Google Play, never from links in SMS or email
For a broader view of your savings strategy — including T-bills, Singapore Savings Bonds, and fixed deposits — the Singapore T-bills 2026 guide and Singapore Savings Bonds guide are useful references if you’re looking at alternatives to digital bank savings accounts.
Frequently Asked Questions
Which is the best digital bank in Singapore in 2026?
The best digital bank depends on your lifestyle. GXS Bank is best for simple, no-conditions daily interest (0.88%–1.75% p.a.). MariBank is best for Shopee users who can earn up to 3.08% p.a. as a new user stacking all bonuses. Trust Bank is best if you want credit card cashback at FairPrice alongside a savings account earning up to 2.40% p.a. Many Singaporeans open all three to capture welcome bonuses.
Are digital banks in Singapore safe?
Yes. GXS Bank, MariBank, and Trust Bank are all MAS-licensed and members of the Singapore Deposit Insurance Corporation (SDIC) scheme. Your Singapore dollar deposits are insured up to S$100,000 per depositor per institution — the same protection that applies to DBS, OCBC, and UOB. Digital Full Banks (GXS and MariBank) must meet the same core capital and liquidity requirements as traditional banks.
Can I have accounts at all three digital banks at the same time?
Yes, you can open accounts at GXS Bank, MariBank, and Trust Bank simultaneously. There is no restriction on having multiple digital bank accounts in Singapore. In fact, opening all three lets you capture every welcome bonus — which can add up to a meaningful amount depending on your initial deposit size. Just ensure you don’t keep more than S$100,000 in any single institution, as the SDIC limit is per bank.
What is the interest rate for digital banks in Singapore in 2026?
As at September 2026: GXS Bank offers 0.88% p.a. on the Main Account and 1.08% p.a. on Saving Pockets (up to 1.75% p.a. on Boost Pockets with a fixed lock-in). MariBank offers 0.88% p.a. as the base rate, rising to 3.08% p.a. for new users in the first 30 days with all bonuses stacked. Trust Bank’s base rate is 0.05% p.a., with a maximum of 2.40% p.a. if you meet all bonus criteria including a referral, investment in TrustInvest, and salary crediting.
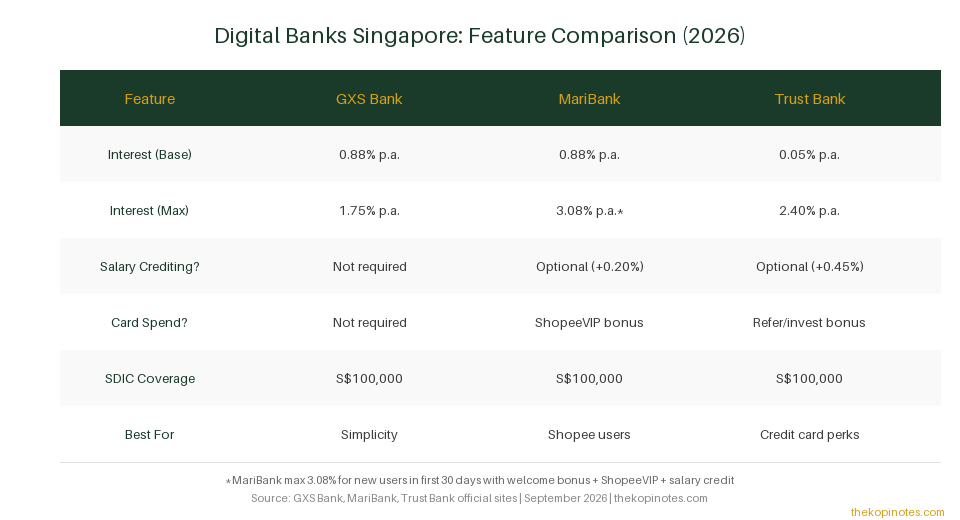
Do digital banks in Singapore require salary crediting?
GXS Bank does not require salary crediting for any tier of interest — you earn 0.88% p.a. regardless. MariBank offers an optional salary credit bonus of +0.20% p.a. if you credit at least S$1,500 per month, but the base rate of 0.88% p.a. is paid without conditions. Trust Bank offers a +0.45% p.a. salary credit bonus, but the base rate of 0.05% p.a. is so low that salary crediting is effectively necessary to earn a meaningful return.
How do I open a digital bank account in Singapore?
All three digital banks can be opened entirely via their mobile apps using Singpass MyInfo. The process typically takes 5–10 minutes. You’ll need a valid Singapore ID (NRIC for citizens and PRs, or FIN for pass holders), and the bank will verify your identity through Singpass. Once approved, you can fund your account via PayNow or bank transfer and start earning interest immediately. No physical documents or branch visits are required.
What is the deposit limit for Singapore digital banks?
MariBank caps savings at S$100,000 per account — which conveniently matches the SDIC insurance limit, meaning your entire balance is always fully covered. GXS Bank does not publish a strict deposit cap for personal accounts. Trust Bank, holding a full bank licence, has no special cap beyond standard banking limits. In all cases, keep in mind that SDIC insurance only covers S$100,000 per depositor per institution, so splitting large savings across multiple banks is prudent.
Open Your Digital Bank Account Today
Use these referral codes to get a welcome bonus when you sign up. All three are MAS-licensed and SDIC-insured.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.