MediSave Q4 2026 Checklist: 7 Things to Review Before December
A practical guide for Singaporeans — covering BHS, ISP riders, AWL limits, CareShield Life, and year-end tax relief.
Your MediSave Account earns a guaranteed 4% interest per year and pays for hospitalisation, your Integrated Shield Plan (ISP) premium, and approved outpatient treatments. The Basic Healthcare Sum (BHS) for 2026 is $79,000. Q4 is the best time to check your balance, review your ISP rider after the April 2026 rule changes, and decide whether to top up before December 31.
Not financial advice. All figures are for educational reference only. Data verified as at 11 September 2026.
- BHS 2026 is $79,000. If your MA is near the cap, contributions overflow to OA/SA from 1 January 2027.
- New ISP riders from April 2026 no longer cover your deductible — but premiums are ~30% cheaper.
- Voluntary MediSave top-ups by 31 December may qualify for CPF tax relief if you are in the 7%+ income bracket.
Table of Contents
Contents — Click to expand
- Why Q4 Matters for Your MediSave
- Check 1 — BHS Position ($79,000 in 2026)
- Check 2 — ISP Rider Review After April 2026
- Check 3 — AWL and ISP Premium Drawdown
- Check 4 — MediSave Top-Up for Tax Relief
- Check 5 — CareShield Life Premiums
- Check 6 — CDMP Outpatient MediSave
- Check 7 — MediSave for Dependants
- Q4 Summary Checklist Table
- Frequently Asked Questions
Why Q4 Matters for Your MediSave
Most Singaporeans set up their CPF GIRO and ISP deductions once, then forget them. That works most of the time. But Q4 is when the annual arithmetic actually matters.
ISP premiums reset on their anniversary date. CareShield Life runs on a calendar year. CPF voluntary contribution deadlines fall on 31 December. And the CDMP outpatient allowance expires if unused.
Taking 20 minutes in September or October to run through these seven checks can save money, close coverage gaps, and ensure your MediSave works as hard as it should. The complete MediSave Singapore 2026 guide covers the account in full — this article focuses on the year-end action items.
Check 1 — Your BHS Position ($79,000 in 2026)
The Basic Healthcare Sum (BHS) is the maximum balance your MediSave Account can hold. For 2026, the BHS is $79,000. Once your MA hits this level, further mandatory CPF contributions overflow to your OA or SA instead.
Why does this matter in Q4? Two reasons. First, if your MediSave is already near $79,000, your employer’s MediSave contributions are flowing elsewhere — so voluntary top-ups would also overflow. Second, if you turn 65 in 2026, your BHS locks permanently at $79,000. After that, it does not increase for your cohort.
Log in to cpf.gov.sg to check your current MA balance. The MediSave interest rate guide explains how your 4% p.a. interest compounds quietly in the background — a $79,000 balance grows by over $3,000 per year.
Check 2 — ISP Rider Review After April 2026 Changes
April 2026 brought the biggest change to ISP riders in years. You need to know what changed — and whether your current coverage still suits you.
What changed from 1 April 2026:
- New ISP riders no longer cover the minimum deductible set by MOH.
- The annual co-payment cap was raised from $3,000 to $6,000 per year.
- Premiums on new private hospital riders fell by approximately 30% on average.
- Existing riders bought before April 2026 are grandfathered until renewal or upgrade.
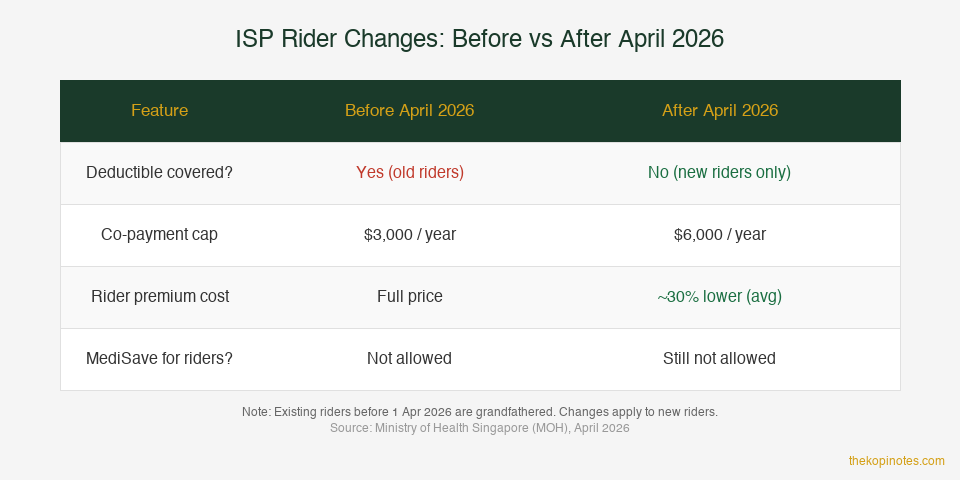
Source: Ministry of Health Singapore (MOH), April 2026. Chart: The Kopi Notes.
If you are on an old rider: your deductible is still covered, but renewal premiums may have risen. If you switch to a new rider: premiums drop ~30%, but the deductible comes out of pocket. The right choice depends on your health history and how often you claim.
Check 3 — Annual AWL and ISP Premium Drawdown
You can use MediSave to pay part of your ISP premium — but only up to the Additional Withdrawal Limit (AWL) set by MOH. This limit applies to the additional private insurance component only. Your MediShield Life base premium is handled separately by CPF Board.
One critical point: MediSave cannot pay your ISP rider premium. Rider premiums must be paid fully in cash, typically via GIRO.
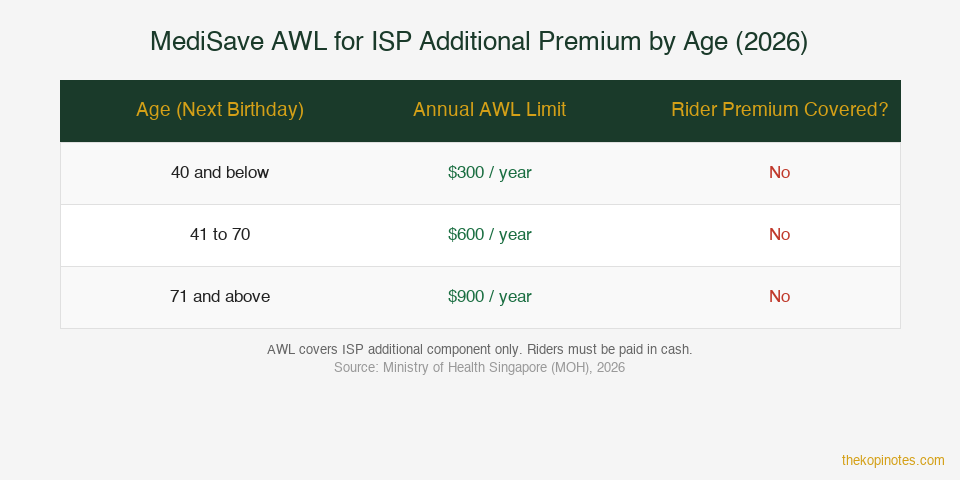
Source: Ministry of Health Singapore (MOH), 2026. Chart: The Kopi Notes.
| Age (Next Birthday) | Annual AWL for ISP | Covers Rider Premium? |
|---|---|---|
| 40 and below | $300 | No |
| 41 to 70 | $600 | No |
| 71 and above | $900 | No |
Source: Ministry of Health Singapore (MOH), 2026
Check your ISP premium notice to confirm how much MediSave is being applied each year. If your ISP premium exceeds the AWL, the remainder is charged to your cash account via GIRO.
Check 4 — MediSave Top-Up for Tax Relief
Voluntary cash top-ups to your MediSave Account may qualify for CPF Voluntary Contribution Tax Relief. To qualify, your top-up must be received by CPF before 31 December 2026. Allow 3–5 working days for processing — aim to submit by mid-December.
This is most useful if your chargeable income puts you in the 7% income tax bracket or above. For example, someone earning $80,000 a year who tops up $5,000 could save $350–$700 in income tax, depending on their bracket. The MediSave balance also earns 4% p.a. guaranteed interest after the top-up.
Read the MediSave top-up step-by-step guide for instructions on how to contribute via CPF e-Cashier or PayNow. Note: top-ups are subject to the annual CPF contribution ceiling and cannot exceed the BHS balance.
Check 5 — CareShield Life Premiums
CareShield Life premiums for those aged 30–67 are automatically deducted from MediSave each year. You generally do not need to do anything. However, in Q4 it is worth verifying the deduction occurred — especially if your MA was at or near the BHS and some contributions overflowed.
The CareShield Life Singapore guide explains how monthly payouts work and how supplement riders can top up the base benefit. If you hold a CareShield Life supplement or an ElderShield supplement, check whether your insurer has issued a renewal premium notice. These supplement premiums are not covered by MediSave — they are cash-only.
Check 6 — CDMP Outpatient MediSave Claims
MediSave covers approved outpatient treatments under the Chronic Disease Management Programme (CDMP). If you have a qualifying condition — such as diabetes, hypertension, high cholesterol, asthma, or stroke — your doctor can bill MediSave directly for up to $500 per patient per year under CDMP.
In Q4, check whether you have used your CDMP allowance. If not, schedule the relevant consultations before 31 December. Unused CDMP allowance does not carry forward to 2027.
For those aged 60 and above, Flexi-MediSave allows up to $200 per year for outpatient visits at approved clinics, even without a specific CDMP condition. Check your MediSave transaction history at cpf.gov.sg to see what has been drawn this year.
Check 7 — MediSave for Dependants
You can use your own MediSave to pay for immediate family members’ medical bills and ISP premiums — spouse, children, and parents. The AWL applied is based on your own age, not the dependant’s.
For children, MediSave grows slowly since they have no CPF contributions. Review your family’s ISP coverage in Q4 — especially if any child or elderly parent had health changes in 2026. The MediShield Life benefits guide explains what base MediShield Life covers for dependants.
Also consider whether your elderly parent’s ISP is still appropriate after the April 2026 rider changes. For an 80-year-old on a high-tier private hospital plan with an old rider, the grandfathered terms may be worth keeping — even if the renewal premium is higher than a new rider would cost.
Q4 MediSave Checklist Summary
| # | Check | Action | Deadline |
|---|---|---|---|
| 1 | BHS Position | Check MA balance at cpf.gov.sg | Any time |
| 2 | ISP Rider Review | Assess if rider still suits you post-Apr 2026 | Before renewal |
| 3 | AWL & ISP Drawdown | Verify GIRO deduction matches AWL cap | October |
| 4 | Top-Up for Tax Relief | Submit via CPF e-Cashier or PayNow | Mid-December |
| 5 | CareShield Life | Confirm premium deducted; check supplement | December |
| 6 | CDMP Outpatient | Use remaining CDMP MediSave ($500/yr) | 31 December |
| 7 | Dependant Coverage | Review family ISP and MA deductions | Any time |
Source: CPF Board, MOH Singapore, 2026. The Kopi Notes editorial team.
Frequently Asked Questions
What is the MediSave BHS for 2026?
The Basic Healthcare Sum (BHS) for 2026 is $79,000. This is the maximum amount that can sit in your MediSave Account. Once your MA reaches this level, further mandatory CPF contributions flow to your OA or SA instead. The BHS is reviewed annually. If you turn 65 in 2026, your BHS locks at $79,000 permanently for your cohort.
Can I use MediSave to pay my ISP rider premium?
No. MediSave cannot be used for ISP rider premiums. Only the additional private insurance component of your ISP base plan is covered by MediSave, up to the AWL: $300/year (age ≤40), $600/year (age 41–70), and $900/year (age 71+). Rider premiums must be paid entirely in cash, typically by GIRO.
What changed with ISP riders from April 2026?
From 1 April 2026, new ISP riders sold in Singapore no longer cover the minimum deductible set by MOH. The annual co-payment cap was also raised from $3,000 to $6,000. In exchange, new rider premiums are approximately 30% lower on average compared to old full-coverage riders. If you already had an old rider before April 2026, it stays grandfathered — but check what happens at your next renewal.
How do I top up my MediSave voluntarily?
Top up via CPF e-Cashier at cpf.gov.sg or PayNow using your CPF reference number. Top-ups must clear by 31 December to count toward your 2026 tax assessment. Allow 3–5 working days for processing — aim to submit by mid-December. Voluntary contributions may qualify for CPF Voluntary Contribution Tax Relief, subject to the annual CPF contribution ceiling and BHS cap.
What is the CDMP MediSave allowance and how do I use it?
The Chronic Disease Management Programme (CDMP) lets MediSave pay for outpatient treatments for 23 approved chronic conditions, including diabetes, hypertension, and asthma. You can use up to $500 per patient per year from MediSave under CDMP. Your doctor must be registered under CDMP to bill MediSave directly. Unused allowance does not carry forward to the next calendar year, so use it before 31 December.
Can I use my MediSave to pay for family members’ ISP premiums?
Yes. You can use your own MediSave to pay the ISP additional premium for your spouse, children, and parents, subject to your own AWL. For example, if you are 45, your AWL is $600/year. This applies whether you are paying for yourself or an immediate family member. Rider premiums for family members still cannot be paid from MediSave.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.