Mapletree Industrial Trust Share Price: DPU Sustainability & Occupancy Outlook (Q4 2026)
Mapletree Industrial Trust (SGX: ME8U) trades at around S$2.08, offering a trailing dividend yield of approximately 6.1% based on FY2026 DPU of 12.71 cents. With 136 properties across Singapore, North America, and Japan and data centres now making up 57% of its S$8.3 billion portfolio, MIT enters Q4 2026 as a rate-cut beneficiary with a gearing ratio of 37.5% and 73% of borrowings locked in at fixed rates.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
In This Article
- MIT at a Glance: Key Metrics Table
- Share Price Performance and Rate-Cut Tailwinds
- DPU Sustainability Analysis
- Portfolio Quality: Occupancy Rates and Tenant Mix
- Data Centre Exposure and AI Infrastructure Upside
- Valuation: Is MIT Cheap or Expensive?
- Risks to Consider
- Our Take and Verdict
- Frequently Asked Questions
MIT at a Glance: Key Metrics (Sep 2026)
Before diving into the analysis, here is a snapshot of the most important numbers for MIT at the time of writing. These figures combine FY2026 full-year results (ended March 2026) and Q1 FY2027 results (ended June 2026).
| Metric | Value | Notes |
|---|---|---|
| Share Price | ~S$2.08 | As at Sep 2026 |
| FY2026 Full-Year DPU | 12.71 cents | -6.3% YoY; year ended March 2026 |
| Q1 FY2027 DPU | 3.11 cents | Quarter ended June 2026; +0.6% QoQ |
| Trailing Dividend Yield | ~6.1% | Based on 12.71c at S$2.08 |
| Gearing Ratio | 37.5% | Q1 FY2027; MAS limit 50% |
| Fixed-Rate Borrowings | 73% | Protects DPU from rate volatility |
| Portfolio Occupancy | 91.2% | Overall; as at March 2026 |
| Assets Under Management | S$8.3 billion | 136 properties across 3 countries |
| Data Centre Share | ~57% | By portfolio value; 27 DC assets |
Source: Mapletree Industrial Trust FY2026 Annual Results, Q1 FY2027 Business Update, Sep 2026.
Share Price Performance and Rate-Cut Tailwinds
MIT is one of Singapore’s most rate-sensitive industrial REITs and that is now working in its favour. With the US Federal Reserve having entered a rate-cut cycle in late 2024 and the Monetary Authority of Singapore following suit with a more accommodative Singapore Dollar NEER stance, the financing cost tailwinds for leveraged assets like MIT are beginning to feed through.
The trust has been disciplined about refinancing. With 73% of its borrowings fixed, MIT is insulated from near-term rate swings while still positioned to benefit as floating-rate debt reprices lower over FY2027 and FY2028. This is in contrast to REITs with higher floating-rate exposure, which remain more vulnerable to policy reversals.
MIT’s share price has recovered from a trough of around S$1.80 in late 2023, when rate hike fears weighed heavily on the sector. The current level near S$2.08 reflects a partial re-rating, but the yield spread of approximately 4.2 percentage points above the current T-bill rate of 1.92% remains attractive by historical standards.
You can review our earlier Mapletree Industrial Trust share price forecast and data centre analysis to see how the thesis has evolved since early 2026.
For readers building long-term passive income in Singapore, MIT at current levels offers a combination of yield, defensive portfolio quality, and a credible data centre growth story.
DPU Sustainability Analysis
The most important question for MIT investors is whether the distribution per unit can be maintained and ideally grown over the next two to three years. The FY2026 full-year DPU of 12.71 cents was 6.3% lower than FY2025, primarily reflecting the impact of the US data centre divestment programme and softer industrial rents in Singapore’s flatted factory segment.
However, the Q1 FY2027 DPU of 3.11 cents showed a 0.6% quarter-on-quarter uptick. On an annualised basis, Q1 FY2027 implies a run rate of approximately 12.44 cents per unit, translating to a forward yield of roughly 5.98% at S$2.08.
MIT DPU History (FY2024 to Q1 FY2027)
| Period | DPU (cents) | YoY Change | Notes |
|---|---|---|---|
| FY2024 (Mar 2024) | 13.57 | -3.1% | Rate hike headwinds; stable SG segment |
| FY2025 (Mar 2025) | 13.56 | ~flat | Resilient; US DC income offset declines |
| FY2026 (Mar 2026) | 12.71 | -6.3% | Divestments reduced income; lower NPI |
| Q1 FY2027 (Jun 2026) | 3.11 | +0.6% QoQ | Early stabilisation signal; quarterly |
Source: MIT quarterly results announcements. FY2024/25 based on reported figures.
Three structural factors support DPU sustainability going forward. First, the Philadelphia Data Centre divestment (completed June 2026) reduced debt and simplified the portfolio. Second, 73% of borrowings are fixed, shielding distribution income from refinancing risk. Third, the Singapore data centre segment at near-100% occupancy provides a reliable income floor. The primary risk to DPU is continued softness in the flatted factory and business park segments.
Portfolio Quality: Occupancy Rates and Tenant Mix
MIT’s overall portfolio occupancy of 91.2% as at March 2026 masks an important bifurcation. The data centre segment operates at near-full utilisation (~99%), while traditional industrial assets face softer demand at 88% to 90%.
This bifurcation reflects a broader structural shift in Singapore’s industrial property market, where technology-adjacent facilities command premium rents while older-generation industrial space faces competition from newer stock. For MIT, this is manageable given that data centres represent 57% of portfolio value and are underpinned by long WALE tenants with investment-grade counterparties.
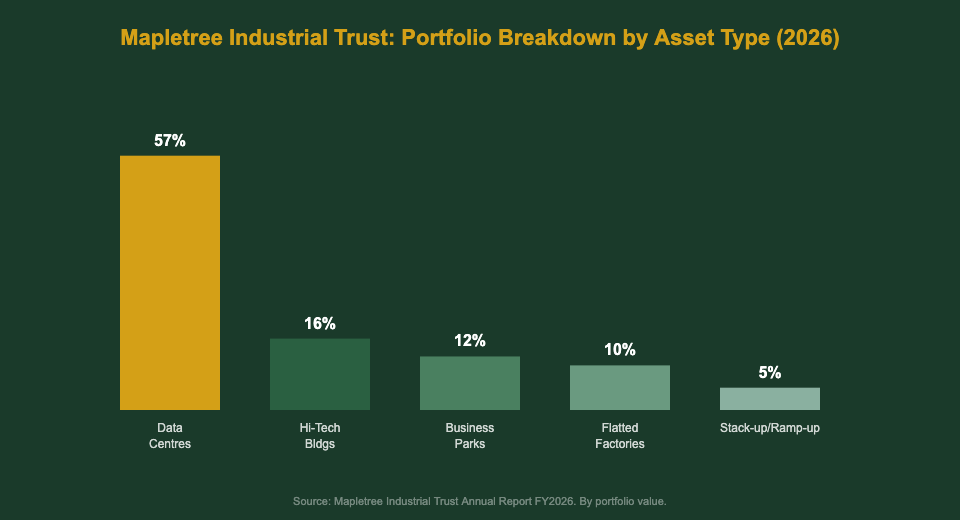
MIT portfolio by asset type. Data centres now comprise 57% by value. Source: MIT FY2026 Annual Report.
Occupancy by Asset Type (Estimated, 2026)
| Asset Type | Portfolio Weight | Occupancy | Outlook |
|---|---|---|---|
| Data Centres | ~57% | ~99% | Strong; AI demand underpins leases |
| Hi-Tech Buildings | ~16% | ~90% | Stable; R&D tenants retain space |
| Business Parks | ~12% | ~88% | Mixed; hybrid work compresses demand |
| Flatted Factories | ~10% | ~88% | Softer; older stock faces competition |
| Stack-up / Ramp-up | ~5% | ~90% | Steady; light industrial demand intact |
Source: MIT Q1 FY2027 Business Update, SGX filings. Sub-segment occupancy rates are estimates.
MIT’s Singapore data centre tenants include financial services firms, cloud providers, and enterprise IT clients with contractually predictable revenue streams. Leases typically run for five to ten years with staggered expiry, reducing rollover concentration risk in any single quarter.
Data Centre Exposure and AI Infrastructure Upside
MIT’s transformation from a Singapore industrial landlord into a data-centre-focused REIT is the defining story of the past five years. With 27 data centre assets across Singapore, the United States, and Japan now accounting for approximately 57% of the S$8.3 billion portfolio by value, MIT is the most accessible data-centre-weighted REIT for retail investors on SGX.
The AI infrastructure buildout is the key tailwind. Hyperscaler demand for colocation space in major data centre hubs including Singapore, Tokyo, and US secondary markets has kept vacancy rates near zero and rental growth elevated. MIT’s Singapore data centres, which sit in one of the world’s top data centre hubs by investment volume, are particularly well positioned.
The Philadelphia Data Centre divestment completed in June 2026 raised cash, reduced gearing, and simplified the US exposure. The remaining US assets serve enterprise and government tenants with stable demand patterns rather than relying solely on hyperscalers.
For a deeper examination of MIT’s data centre strategy, see our earlier article: Mapletree Industrial Trust data centre growth Singapore 2026.
The key watch item for Q4 2026 is lease renewal activity. New data centre leases signed at above-prior-passing rents would be a positive catalyst for DPU recovery. Any delays in expansion permits from Singapore’s Urban Redevelopment Authority could dampen the near-term pipeline.
Valuation: Is MIT Cheap or Expensive?
At S$2.08, MIT trades at a price-to-book ratio of approximately 1.09x based on an estimated net asset value of around S$1.90 per unit. This is below the historical peak of 1.4x to 1.5x before 2022 but above the 2023 trough near 0.95x, suggesting a mid-cycle valuation with room for further re-rating without being obviously cheap.
The more practical metric for income-focused investors is the yield spread above the risk-free rate. MIT currently offers approximately 4.2 percentage points above the T-bill rate of 1.92%, a historically generous spread that reflects the residual risk premium embedded in the sector since 2022. As T-bill rates drift lower, this spread compression typically drives REIT price appreciation.
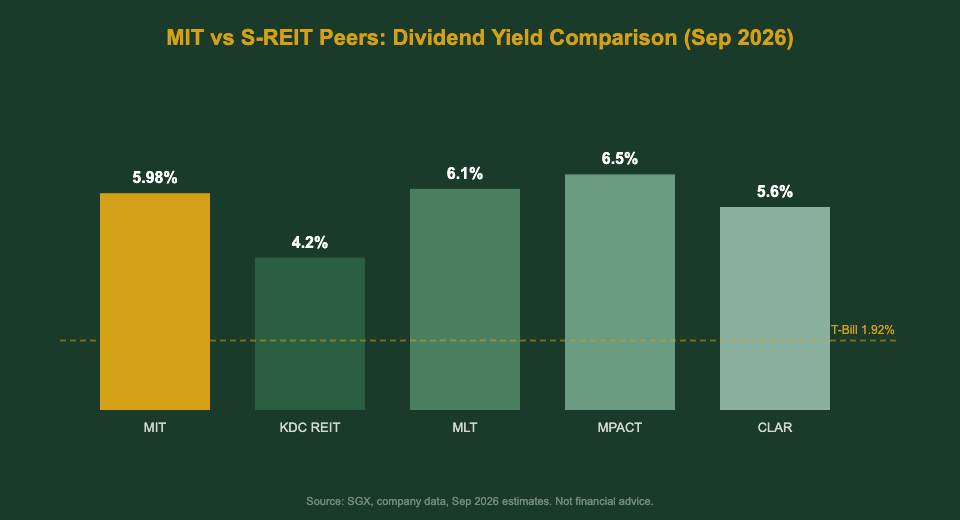
MIT yield vs S-REIT peers, Sep 2026. T-bill 1.92% reference line shown. Not financial advice.
MIT vs Selected S-REIT Peers (Sep 2026)
| REIT | Est. Yield | Gearing | Focus |
|---|---|---|---|
| MIT (ME8U) | ~6.0% | 37.5% | Data centres + industrial (SG/US/JP) |
| Keppel DC REIT (AJBU) | ~4.2% | ~36% | Pure-play data centres |
| Mapletree Logistics Trust (M44U) | ~6.1% | ~41% | Logistics / Asia-Pacific |
| Mapletree Pan Asia Commercial (N2IU) | ~6.5% | ~40% | Commercial / retail / office |
| CapitaLand Ascendas REIT (A17U) | ~5.6% | ~38% | Industrial / business parks / DC |
Source: SGX, company data, Sep 2026 estimates. Not financial advice.
For Singapore investors building a diversified REIT portfolio, see our guide to the best S-REITs in Singapore for 2026 to see how MIT ranks against the broader sector.
Risks to Consider
No investment analysis is complete without a clear-eyed look at the risks. For MIT in Q4 2026, four stand out.
1. Flatted factory and business park vacancy creep. If occupancy in these segments falls below 85%, it would weigh on NPI and put further downward pressure on DPU. A Singapore recession or a pullback in manufacturing activity could accelerate this.
2. US data centre concentration and geopolitical risk. MIT’s remaining US data centre assets are subject to regulatory scrutiny, especially in the context of US-China technology tensions that can affect foreign ownership of critical infrastructure. Any policy change affecting cross-border data centre ownership could complicate the US asset strategy.
3. Gearing at 37.5% after perpetual securities redemption. The trust redeemed S$300 million in perpetual securities in Q1 FY2027, funded by debt. While 37.5% is well below the 50% MAS limit, it leaves less headroom for debt-funded acquisitions without a dilutive equity fund raising.
4. Currency risk. With assets in the US and Japan, MIT’s SGD-denominated distributions are exposed to USD and JPY movements. A sharp depreciation of either currency versus the SGD would reduce translated income. The trust uses partial hedging, but currency risk cannot be entirely eliminated.
If you are thinking about how MIT fits into your overall retirement planning, our Singapore retirement planning calculator can help you estimate the income you need and how a position in MIT might contribute.
Our Take: MIT in Q4 2026
MIT is not a high-growth story. The FY2026 DPU decline of 6.3% is a genuine negative, and the softness in flatted factory and business park occupancy is a real drag. What MIT offers instead is quality and transition. It is a REIT that is methodically repositioning its portfolio toward the most structurally sound corner of the industrial property market while managing its balance sheet conservatively.
At S$2.08, the trailing yield of approximately 6.1% and the yield spread of 4.2 percentage points above the T-bill rate price in a reasonable amount of uncertainty. The Q1 FY2027 DPU stabilisation at 3.11 cents per quarter is an early signal that the worst of the distribution compression may be over. If rate cuts continue through 2027 and Singapore data centre demand remains robust, MIT is positioned to deliver steady, growing distributions from a portfolio of genuine infrastructure quality.
This article is for educational reference only. It is not a buy or sell recommendation. Always do your own research before making any investment decision.
Start Investing in S-REITs
If you are looking to invest in MIT or other S-REITs, here are the platforms we use for Singapore investors:
- Endowus (referral code 2V343) – for CPF, SRS, and cash investing in funds including REIT-focused portfolios.
- Syfe (referral code SRPRFFFCD) – for automated REIT+ portfolios and hands-off S-REIT exposure.
- FSMOne (referral code P0544985) – for direct SGX stock purchases including ME8U with competitive brokerage fees.
- Interactive Brokers (referral jianxiong368) – for the lowest brokerage rates on SGX and international market access.
These are referral links. We may receive a benefit if you sign up. All investment products carry risk. Not financial advice.
Frequently Asked Questions
What is Mapletree Industrial Trust current share price and yield?
Is MIT REIT DPU sustainable in 2026 and 2027?
What is MIT REIT portfolio occupancy rate?
How much data centre exposure does MIT REIT have?
What is MIT REIT gearing ratio and is it safe?
How does MIT compare to Keppel DC REIT for data centre exposure?
How do rate cuts benefit Mapletree Industrial Trust?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.