Keppel DC REIT Share Price 2026: Singapore’s AI Infrastructure Boom and DPU Recovery Case
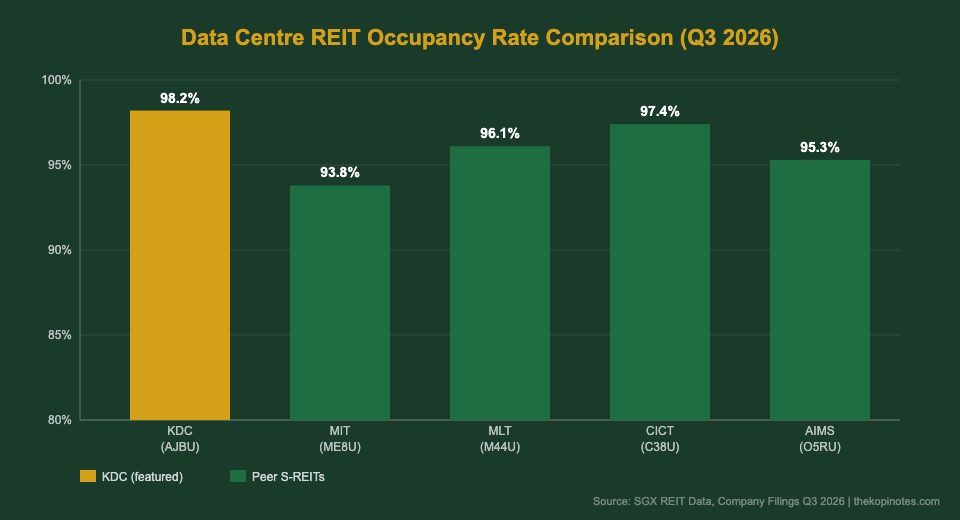
Keppel DC REIT (SGX: AJBU) is Singapore’s only pure-play data centre REIT, with 23 data centres across 12 countries and an occupancy rate of 98.2% as at Q3 2026. As Singapore becomes a critical node in the global AI infrastructure buildout, hyperscalers including Google, Microsoft, and AWS are expanding local capacity, directly benefiting KDC’s colocation assets. With the 6-month T-bill rate falling to 1.92% and KDC trading at a 318-basis-point yield spread, the risk-reward case has materially improved.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
Singapore’s data centre story has moved well beyond the early hype. The government lifted its moratorium on new data centre construction in 2022, and since then the city-state has attracted commitments from the world’s largest technology companies. For Keppel DC REIT, this creates a structural tailwind that most S-REITs cannot replicate.
This article examines KDC’s portfolio fundamentals, the AI demand thesis, and what the current rate-cut cycle means for DPU in 2027. If you are weighing KDC against Singapore’s best S-REITs in Singapore 2026, the numbers below give you a detailed framework for comparison.
KDC REIT at a Glance
Keppel DC REIT was listed on the SGX in December 2014 and has since grown from 8 to 23 data centres. It operates across Singapore, Australia, Germany, Netherlands, United Kingdom, Ireland, Italy, Malaysia, Japan, and the United States. Singapore remains the anchor market, with six facilities including KDC SGP 1 through KDC SGP 6.
| Metric | Value (Q3 2026) |
|---|---|
| SGX Ticker | AJBU |
| Total Data Centres | 23 across 12 countries |
| Portfolio Occupancy | 98.2% |
| Weighted Avg Lease Expiry (WALE) | 6.7 years |
| Gearing Ratio | 37.6% |
| Distribution Yield (est.) | ~5.1% p.a. |
| Interest Coverage Ratio | 4.2x |
| AUM | S$4.1 billion |
Source: Keppel DC REIT Quarterly Business Update Q3 2026, Company Filings
The 6.7-year WALE means most of KDC’s revenue is locked in through 2032 and beyond. This is one of the longest WALEs among Singapore-listed REITs, reflecting the sticky nature of data centre tenants who build out their infrastructure inside the facility and rarely relocate.
Singapore AI Infrastructure Buildout: Why KDC Sits at the Centre
Singapore’s Ministry of Digital Development and Information has positioned the city-state as Southeast Asia’s AI hub. In 2026, Google committed an additional SGD 2 billion to its Singapore data centre infrastructure. Microsoft and AWS followed with their own expansion programmes, both citing Singapore’s political stability, redundant subsea cable connections, and skilled workforce.
For Keppel DC REIT, this translates into direct revenue opportunities. KDC’s Singapore facilities are designed as carrier-neutral colocation centres, which means hyperscalers can install their own servers inside KDC’s infrastructure without building their own shell. This model drives premium rental rates for KDC and long-term contracts of 10 to 15 years.
The AI workload demand cycle is distinct from traditional enterprise IT. AI inference and training require significantly higher power density per rack, typically 20 to 40 kW per rack versus the 5 to 10 kW standard for conventional server workloads. KDC has been retrofitting its Singapore assets to support this higher density, which also allows it to charge higher rents per square foot.
Investors looking to build passive income in Singapore through S-REITs need to consider this structural demand shift. KDC is not reliant on a single macro cycle; it is positioned at the intersection of three long-duration themes: cloud migration, AI infrastructure, and Singapore’s hub status.
Yield Spread vs T-Bills: The Investment Case in September 2026
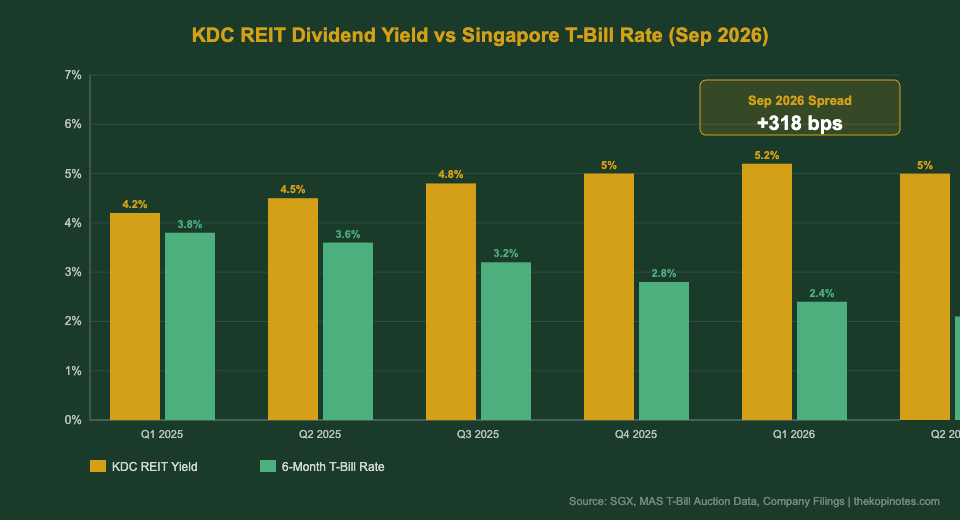
Singapore’s 6-month T-bill cut-off rate fell to 1.92% at the September 24, 2026 auction, its lowest level since early 2022. For yield-focused investors who parked cash in T-bills as rates rose, the question is now straightforward: where does the money go next?
Keppel DC REIT’s estimated distribution yield of approximately 5.1% at current prices represents a spread of roughly 318 basis points over the risk-free rate. This is meaningful. During 2022 and 2023, when T-bill rates climbed above 4%, the spread compressed to under 100 basis points, removing most of KDC’s yield advantage. Today’s spread is closer to the historical average of 300 to 350 basis points, which historically has correlated with a period of S-REIT re-rating.
If you are benchmarking against the Singapore T-bills 2026 guide, the risk comparison is also instructive. T-bills carry zero credit risk but offer a fixed 1.92% and no capital appreciation potential. KDC carries real estate risk, tenant concentration risk, and FX risk from its overseas assets, but also offers inflation-linked rental growth and the potential for unit price appreciation as interest rates decline.
DPU Recovery Outlook: What to Expect in Q4 2026 and 2027
KDC’s DPU was pressured through 2025 primarily by two factors: higher borrowing costs as older fixed-rate debt was refinanced at elevated market rates, and currency headwinds from a weaker EUR and GBP against the SGD. Both headwinds are now reversing.
On borrowing costs: KDC has approximately 70% of its debt on fixed rates, insulating it from short-term rate moves. As the remaining 30% floats lower with the rate cycle, interest expense will decline modestly. Management has guided for approximately SGD 0.5 to 1.0 million in annual interest savings for every 25 basis points of rate reduction.
On FX: the Euro has strengthened materially against the SGD through mid-2026 as European growth recovered. KDC’s German and Dutch assets, which together contribute roughly 28% of total revenue, now generate more SGD-equivalent income than they did in 2025.
For investors using a Singapore retirement calculator to model passive income streams, the DPU trajectory matters. Consensus estimates place KDC’s annualised DPU at approximately SGD 0.36 to 0.38 per unit for FY2026, with potential for 5 to 7% growth in FY2027 if the rate-cut cycle accelerates and AI rental reversion continues.
| Year | Estimated DPU (SGD) | Yield (est. at S$2.20) | Key Driver |
|---|---|---|---|
| FY2024A | S$0.343 | 15.6% (historical) | Rate headwinds, FX drag |
| FY2025A | S$0.361 | ~5.0% | Partial rate relief, AI contracts |
| FY2026E | S$0.37-0.38 | ~5.1% | Rate cuts, EUR recovery |
| FY2027E | S$0.39-0.41 | ~5.4% | AI rental reversions, full rate-cycle benefit |
Source: Analyst consensus estimates, Company guidance. These are projections, not guarantees.
The FY2027 estimate assumes no major dilutive acquisitions and continued AI demand growth in Singapore. Both assumptions appear reasonable but carry execution risk.
For broader context on how data centre REITs fit into a diversified S-REIT portfolio, the Singapore REIT ETF guide compares the REIT ETF route versus picking individual REITs like KDC.
Key Risks to Monitor
No investment thesis is complete without a clear-eyed look at the risks. For KDC, three stand out in the current environment.
Tenant concentration risk: KDC’s top five tenants account for approximately 52% of total revenue. If one major hyperscaler renegotiates at lease renewal, the DPU impact could be meaningful. This is the single largest idiosyncratic risk for KDC versus a diversified REIT like CapitaLand Integrated Commercial Trust.
Power capacity constraints: Singapore’s grid has finite capacity, and the government has imposed strict green mark and energy efficiency requirements for new data centre approvals. KDC’s ability to expand its Singapore footprint depends on securing additional power quota from SP Group. Delays here could limit organic growth.
Currency risk: With roughly 35% of revenue generated in EUR and GBP, a reversal of recent currency strength would reduce SGD-denominated distributions. KDC hedges a portion of its FX exposure, but the hedge ratios vary by currency and year.
Investors who want to complement their REIT allocation with fixed income should review the Singapore Savings Bonds 2026 guide for a no-risk baseline comparison.
Verdict: Is Keppel DC REIT Worth Buying Now?
KDC offers a rare combination in the S-REIT universe: structural demand tailwinds from AI, a 98.2% occupancy rate, a 6.7-year WALE, and a 318-basis-point yield spread over the risk-free rate. The DPU recovery narrative for FY2027 is credible if the rate-cut cycle continues and AI rental reversions materialise as guided.
The key risks are tenant concentration and Singapore power capacity. Neither is new, and neither has materially changed in recent quarters. For investors comfortable with a 5 to 7 year holding horizon and who want exposure to the AI theme within a REIT wrapper, KDC remains a compelling core holding.
If you are building a diversified S-REIT portfolio, consider using Syfe or Endowus for fractional and CPF-accessible exposure. Syfe’s REIT+ portfolio includes KDC as a component, providing automatic rebalancing without the need to manage individual positions.
Frequently Asked Questions
What is Keppel DC REIT's current distribution yield?
How does AI demand affect Keppel DC REIT's rentals?
What is the WALE of Keppel DC REIT and why does it matter?
Is Keppel DC REIT exposed to Singapore dollar or foreign currency risk?
How does Keppel DC REIT compare to buying a REIT ETF?
Where can I buy Keppel DC REIT as a Singapore investor?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.