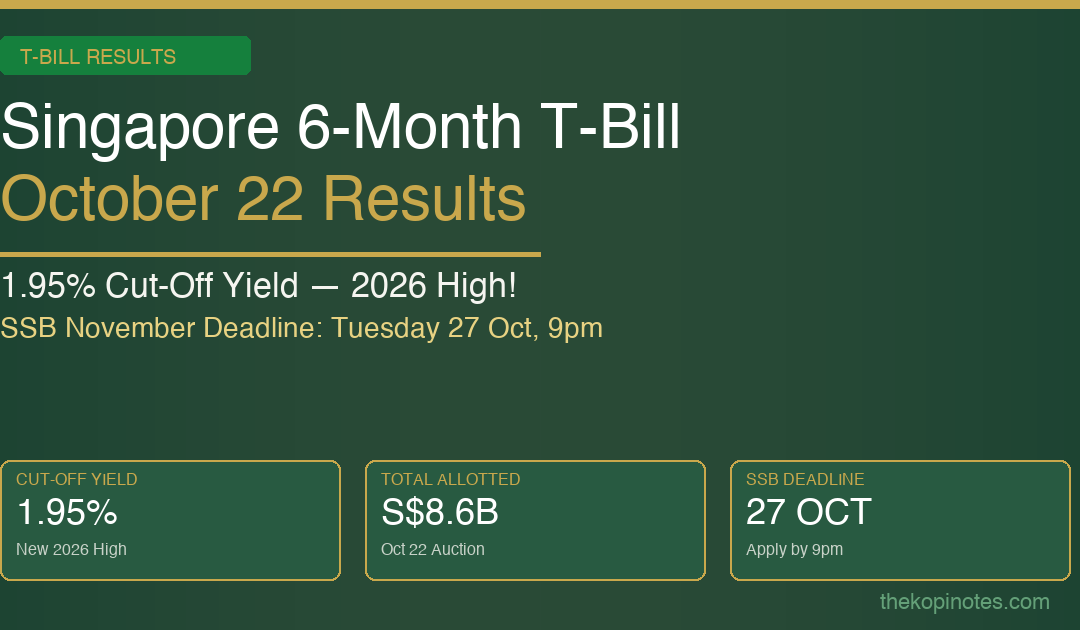
The Singapore 6-month T-bill cut-off yield surged to 1.95% per annum at the 22 October 2026 auction — the highest level seen all year. With yields rising and the SSB November 2026 (GX26110X) application window closing on 27 October at 9pm, now is the time to review where your short-term savings are working hardest. Here is the full breakdown of the latest T-bill results, what to make of the trend, and how the key cash instruments stack up.
October 22, 2026 T-Bill Auction Results
The Monetary Authority of Singapore (MAS) published the results for the 6-month Singapore Government Securities (SGS) T-bill auction that closed on 22 October 2026. The headline cut-off yield reached 1.95% per annum — a new high for 2026:
| Metric | Result |
|---|---|
| Cut-Off Yield | 1.95% p.a. — New 2026 High |
| Average Yield | 1.83% p.a. |
| Median Yield | 1.90% p.a. |
| Total Amount Allotted | S$8.6 billion |
| Instrument | 6-Month SGS T-Bill |
| Settlement Date | 24 October 2026 |
| Maturity Date | 23 April 2027 |
The 12-basis-point spread between the average yield (1.83%) and cut-off yield (1.95%) reflects competitive bidding in the institutional market. Retail investors who submitted non-competitive bids — the recommended approach for most individuals — received the cut-off yield of 1.95% in full.
2026 T-Bill Yield Trend: A Sharp Climb Since September
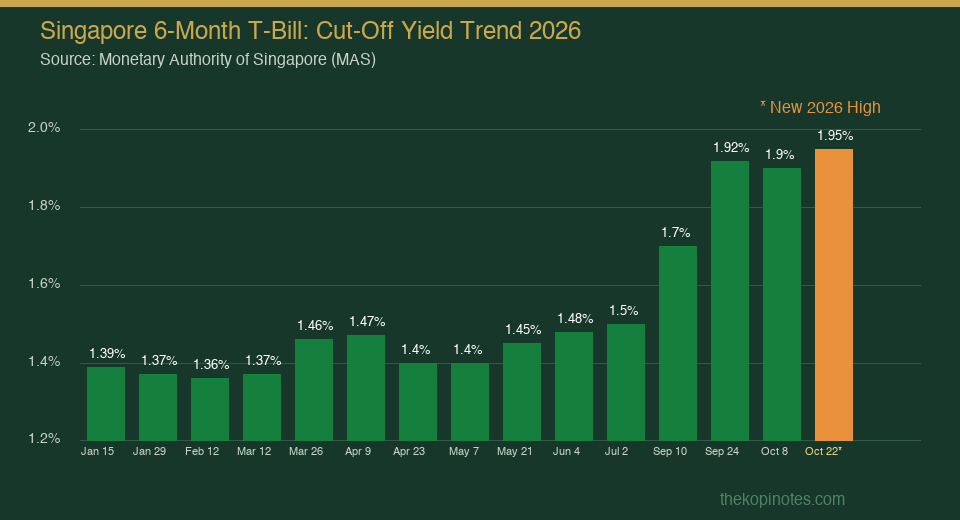
Looking at 2026 auction history, the October 22 result capped a sharp upward swing that began in September:
- January–August 2026: Yields hovered in a narrow 1.36–1.50% range — subdued by the low-rate environment that persisted into mid-year.
- September 10: A sharp jump to 1.70% signalled a definitive shift in market sentiment.
- September 24: Continued the surge to 1.92%, catching many observers off-guard.
- October 8: A slight dip to 1.90% — likely a brief cooling after the aggressive September run-up.
- October 22: Back on the upswing to 1.95%, eclipsing September’s high to set a new 2026 record.
The September–October surge likely reflects a combination of factors: global risk-off sentiment driving demand for capital-guaranteed short-duration instruments, and investor positioning ahead of any potential year-end rate commentary from major central banks. Whether yields will breach 2.00% in the November round remains to be seen.
SSB November 2026 (GX26110X): Deadline is Tuesday, 27 October at 9pm
If you want an alternative to the T-bill with more flexibility, the Singapore Savings Bond (SSB) November 2026 tranche (GX26110X) is your next window. Applications close in just four days — Tuesday, 27 October 2026 at 9pm.
Indicative rates for GX26110X:
| Holding Period | Interest Rate (p.a.) |
|---|---|
| Year 1 | 1.67% |
| Year 2 | ~2.10% (step-up) |
| Years 3–10 | Increasing step-up schedule |
| 10-Year Average | 2.45% p.a. |
The SSB’s Year 1 rate of 1.67% is lower than the current T-bill yield of 1.95%. However, the SSB offers two important advantages that the T-bill cannot match: (1) it is redeemable at any time with one month’s notice and no capital loss, making it ideal for emergency funds; and (2) its 10-year average yield of 2.45% p.a. is a solid long-term return for patient savers who do not need the money imminently.
How to apply for GX26110X: Via DBS/POSB iBanking, OCBC Online Banking, UOB Personal Internet Banking, or an ATM. Minimum S$500; individual cap S$200,000.
Singapore Cash Yield Comparison — October 2026
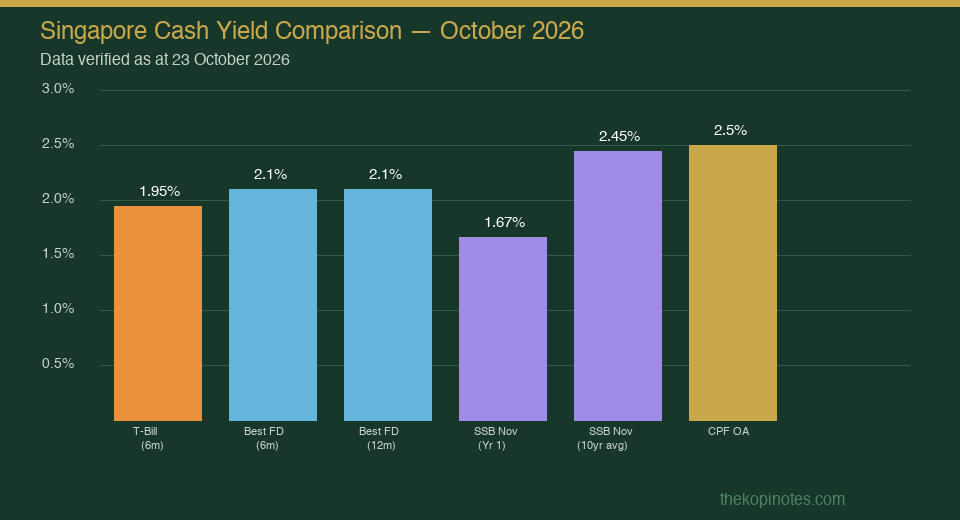
Here is how the key cash instruments stack up as of 23 October 2026:
| Instrument | Yield / Rate (p.a.) | Key Conditions |
|---|---|---|
| T-Bill (6m, Oct 22) | 1.95% | Min S$1,000; 6-month lock-in; next auction ~5 Nov |
| Best 6m Fixed Deposit | 2.10% (Maybank) | Min S$20,000; may require fresh/new funds |
| Best 12m Fixed Deposit | 2.10% (Maybank / RHB / CIMB) | Conditions apply per bank; 12-month lock-in |
| SSB Nov 2026 — Year 1 (GX26110X) | 1.67% | Flexible redemption; deadline 27 Oct, 9pm |
| SSB Nov 2026 — 10yr Average | 2.45% | Step-up rates; ideal for long-term savings |
| CPF Ordinary Account (OA) | 2.50% | CPF funds only; 2.50% floor guaranteed to end-2027 |
| CPF SA / MA / RA | 4.00% | CPF funds only; 4.00% floor guaranteed to end-2027 |
Important CPF note: Since CPF OA earns 2.50% and CPF SA/MA/RA earns 4.00% — both above the current T-bill yield of 1.95% — you should not withdraw your CPF funds to invest in T-bills or SSBs at current rates. Your CPF money already earns more where it is.
T-Bill vs SSB vs Fixed Deposit: How to Decide
With the next T-bill auction (expected ~5 November) and SSB November deadline (27 October) both imminent, here is a simple framework:
Choose the T-Bill (6-month) if you:
- Want the highest currently available risk-free yield (1.95% > SSB Year 1 of 1.67%)
- Can commit funds for 6 months without needing early access
- Are investing below S$20,000 (where high-yield FD minimums are out of reach)
- Prefer simplicity: apply once, receive the full yield at maturity
Choose the SSB (GX26110X) if you:
- Value flexibility and want the ability to redeem early without penalty
- Plan to hold for multiple years (the 10-year average of 2.45% is competitive)
- Want a portion of your savings in a very liquid, capital-guaranteed instrument
- Have not yet maximised your S$200,000 SSB individual cap
Choose a Fixed Deposit if you:
- Have S$20,000 or more in fresh funds that meet the bank’s conditions
- Can lock in for 6 or 12 months at 2.10% (Maybank) — which beats the T-bill
- Are already SDIC insured for amounts up to S$100,000 per bank
Frequently Asked Questions
What does the T-bill cut-off yield of 1.95% mean for retail investors?
If you submitted a non-competitive bid for the October 22 T-bill, you will receive a yield of 1.95% per annum on your investment amount for the 6-month tenor. This means a S$10,000 investment would earn approximately S$97.50 in interest at maturity (23 April 2027). Non-competitive bids are always fully allotted at the cut-off yield, so there is no risk of partial allotment for retail applicants.
How do I apply for the next T-bill?
The next 6-month SGS T-bill auction is expected around 5 November 2026. Application windows typically open about 5-7 days before auction day. Apply online via DBS/POSB, OCBC, or UOB internet banking, or at an ATM. Select “Non-Competitive Bid” for the automatic cut-off yield. Minimum investment is S$1,000 in multiples of S$1,000.
Is it safe to buy Singapore T-bills?
Yes. Singapore Government Securities (SGS), including T-bills, are backed by the full faith and credit of the Singapore Government, which holds a AAA credit rating. T-bills carry zero credit risk and are considered one of the safest investments available to retail investors globally. Your principal is fully returned at maturity.
Should I use my CPF OA to buy T-bills?
At current yields, no. CPF OA earns a guaranteed 2.50% per annum (with a floor maintained to end-2027), while the T-bill yield is 1.95%. Using CPF OA to buy T-bills would result in lower returns than simply leaving your money in CPF OA. The CPF CPFIS scheme allows T-bill purchases, but the mathematics do not favour it at this rate level.
What happens to the SSB November deadline if I apply late?
The SSB November 2026 (GX26110X) application window closes strictly at 27 October 2026, 9pm. There are no extensions. If you miss this tranche, the next SSB application window (December 2026) will open in early November. Interest rates for each tranche are set separately and may be higher or lower depending on prevailing SGS yields.
The Bottom Line
The October 22, 2026 T-bill cut-off yield of 1.95% per annum is a meaningful data point for Singapore savers — confirming that short-duration, risk-free yields continue to trend higher into the fourth quarter of 2026. Whether you are looking for a 6-month yield pick-up or flexible long-term savings, the current landscape offers solid options across T-bills, SSBs, and select fixed deposits.
For most retail savers with cash to deploy, the T-bill remains a compelling choice — especially for amounts below S$20,000 where the best FD rates are harder to access. If flexibility is paramount, lock in the SSB November tranche before the 27 October deadline at 9pm.
This week’s action checklist:
- ✅ SSB November (GX26110X) closes 27 October at 9pm — apply now via your bank’s internet banking
- 📅 Next T-bill application window opens around 29–30 October for the ~5 November auction
- 💡 Review your savings account rates — most pay far below 1.95%
- ⚠ Using CPF funds? T-bill at 1.95% is below CPF OA at 2.50% — keep CPF where it is
Data sourced from MAS, DBS, OCBC, UOB, Maybank, RHB, CIMB, and CPF Board. Rates verified as at 23 October 2026. T-bill yields are determined at auction and may differ for future rounds. This article is for informational purposes only and does not constitute financial advice.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.