Endowment Plan vs CPF LIFE Singapore 2026: Which Is Better for Retirement Income?
Last updated: 17 Oct 2026 | Category: Investment Insurance | 8 min read
An endowment plan is a savings-insurance hybrid that pays a lump sum or regular income at maturity, while CPF LIFE is Singapore’s national longevity annuity that pays lifelong monthly income from age 65. For most Singapore retirees, CPF LIFE offers stronger longevity protection, but a well-chosen endowment plan can complement it — especially for those who want to maximise SRS or leave a legacy. Here is the full comparison for 2026.
Not financial advice. All figures are for educational reference only. Data verified as at 17 Oct 2026.
Table of Contents
Jump to section
- What Is an Endowment Plan?
- What Is CPF LIFE?
- Key Differences: CPF LIFE vs Endowment Plan
- Monthly Income Comparison (BRS / FRS / ERS)
- Returns Comparison: Guaranteed vs Projected
- Who Should Choose What?
- Top Endowment Plans in Singapore 2026
- SRS Connection: Using Both Together
- The Verdict
- Frequently Asked Questions
What Is an Endowment Plan?
An endowment plan is a life insurance product that combines savings with a death benefit. You pay regular premiums over a fixed term (typically 5–25 years), and at maturity you receive a guaranteed payout plus non-guaranteed bonuses that depend on the insurer’s investment performance.
In Singapore, endowment plans are sold by insurers such as Prudential, AIA, NTUC Income, Great Eastern, and Manulife. They are a popular tool for:
- Forced savings — premium commitments prevent ad hoc withdrawals
- Capital preservation — guaranteed component protects principal
- SRS investment — many plans accept Supplementary Retirement Scheme (SRS) funds, deferring tax on contributions
- Legacy planning — death benefit ensures a payout to beneficiaries
The guaranteed portion typically earns 1.5–3.0% p.a., while the total projected return (guaranteed + bonuses) is around 3.0–4.5% p.a. at the Life Insurance Association Singapore (LIA) benchmark rates of 3.00% and 4.25% p.a. (as at Oct 2026).
What Is CPF LIFE?
CPF LIFE (Lifelong Income For the Elderly) is Singapore’s national longevity annuity. When you turn 65, funds in your CPF Retirement Account (RA) are used to buy an annuity that pays a monthly income for life — no matter how long you live.
There are three CPF LIFE plans, each trading monthly payout against bequest:
- Standard Plan: highest monthly payout, lower bequest — most popular choice
- Basic Plan: lower payout, higher bequest (remainder returned to heirs)
- Escalating Plan: starts lower but increases by 2% per year — best for inflation protection
Monthly payouts (Standard Plan, from age 65, 2026 figures from CPF Board):
| Retirement Sum | Amount (2026) | Monthly Payout (approx.) |
|---|---|---|
| Basic Retirement Sum (BRS) | $110,200 | ~$950/month |
| Full Retirement Sum (FRS) | $220,400 | ~$1,780/month |
| Enhanced Retirement Sum (ERS) | $440,800 | ~$3,440/month |
Source: CPF Board, CPF LIFE payout table (2026). Standard Plan payouts from age 65.
One powerful feature: deferring CPF LIFE payouts increases your monthly payout by approximately 6–7% for each year you delay (between age 65 and 70). A retiree who defers from 65 to 70 could receive 30–35% more per month for life.
Key Differences: CPF LIFE vs Endowment Plan
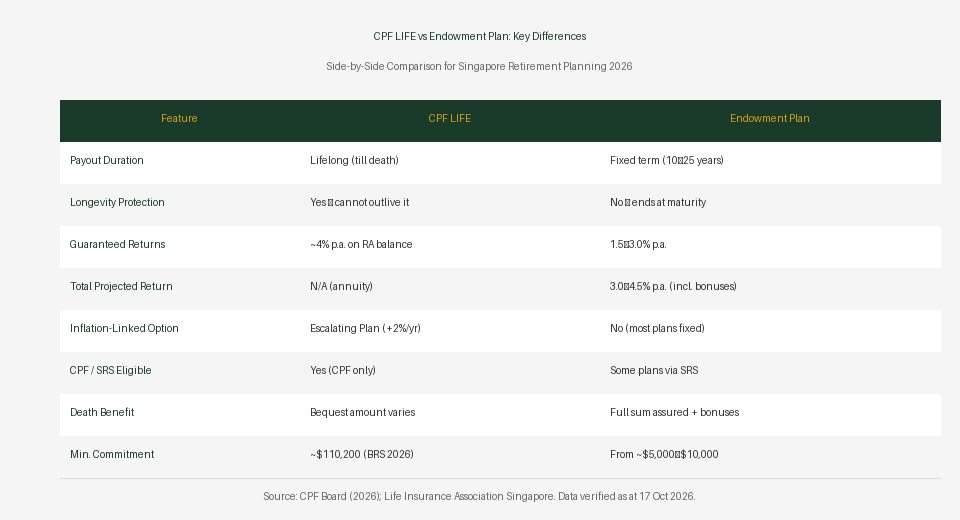
| Feature | CPF LIFE | Endowment Plan |
|---|---|---|
| Payout Duration | Lifelong (till death) | Fixed term (10–25 years) |
| Longevity Risk | Zero — cannot outlive it | High — payouts stop at maturity |
| Guaranteed Returns | ~4% p.a. on RA balance | 1.5–3.0% p.a. |
| Projected Return | N/A (annuity model) | 3.0–4.5% p.a. (incl. bonuses) |
| Inflation Protection | Escalating Plan (+2%/yr) | No (most plans fixed payout) |
| SRS Eligible | No (CPF only) | Yes (select plans) |
| Death Benefit | Bequest (varies by plan) | Sum assured + bonuses |
| Min. Commitment | ~$110,200 (BRS 2026) | From ~$5,000–$10,000 |
Source: CPF Board; Life Insurance Association Singapore (LIA). Data verified 17 Oct 2026.
Monthly Income Comparison: CPF LIFE vs Endowment (BRS / FRS / ERS)
The chart below compares the approximate monthly income a Singapore retiree can expect from CPF LIFE versus the equivalent income stream from an endowment plan (guaranteed portion, assuming 2.80% p.a. on lump sum amortised over 20 years).
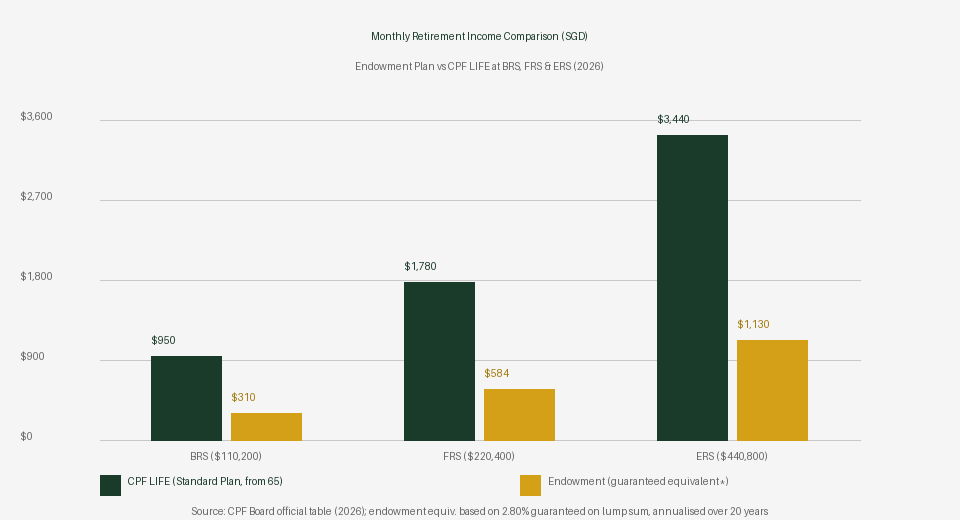
The gap is stark: CPF LIFE at FRS (~$1,780/mth) versus the guaranteed equivalent from an endowment plan on the same $220,400 (~$584/mth) shows a 3× advantage for CPF LIFE. The reason is simple — CPF LIFE pools longevity risk across all participants, so those who live longer subsidise the payout of everyone. An endowment plan must be fully self-funded.
That said, endowment plans shine when the goal is capital preservation with a known maturity date — for example, accumulating for a child’s education, a specific lump sum at 60, or a structured SRS drawdown strategy.
For a deeper dive into planning your retirement cashflows, try our Singapore retirement calculator to model CPF LIFE alongside other income streams.
Returns Comparison: Guaranteed vs Projected
LIA requires all Singapore insurers to illustrate endowment plan returns at two benchmark rates: 3.00% p.a. (low scenario) and 4.25% p.a. (high scenario). These are not guaranteed — only the guaranteed portion of the payout is contractual.
| Return Component | CPF LIFE (RA balance) | Endowment Plan (typical) |
|---|---|---|
| Guaranteed interest rate | 4.0% p.a. | 1.5–3.0% p.a. |
| Non-guaranteed bonuses | N/A | Variable (0–2.5% p.a.) |
| LIA projected total (low) | ~4% (RA grows) | 3.00% p.a. |
| LIA projected total (high) | ~4% (RA grows) | 4.25% p.a. |
Source: CPF Board (Retirement Account interest rates); Life Insurance Association Singapore (LIA benchmark rates Oct 2026).
CPF LIFE’s 4% return on the RA balance is risk-free and government-guaranteed, making it superior on a risk-adjusted basis. Endowment plans can match or exceed this at their high projection, but the non-guaranteed bonus is never contractually assured — it depends on the insurer’s investment performance.
Who Should Choose What?
Choose CPF LIFE if you:
- Want guaranteed lifelong income with zero longevity risk
- Are comfortable with CPF contributing to your retirement sum (OA/SA transfers)
- Want inflation protection (choose Escalating Plan)
- Are not heavily concerned about leaving a large estate
- Want the simplest, lowest-cost retirement income structure
Choose an Endowment Plan if you:
- Have significant SRS savings to deploy (tax-deductible premiums, tax-deferred growth)
- Want a lump-sum payout at a specific date (e.g., children’s education, business succession)
- Are already at the ERS and want additional retirement savings outside CPF
- Want to combine a death benefit with savings in a single product
- Prefer to diversify retirement income sources beyond CPF
For most Singapore residents, the optimal strategy is not either/or. Maximise CPF LIFE first (top up to FRS or ERS where possible), then use endowment plans or S-REITs for supplementary income. You can explore CPF investment strategy options to optimise your SA before 55, or consider passive income strategies in Singapore 2026 alongside your annuity.
Top Endowment Plans in Singapore 2026
Below is a snapshot of representative endowment plans available in Singapore as at Oct 2026. Always verify current rates directly with the insurer or your financial adviser.
| Insurer / Plan | Guaranteed Return | Projected (LIA High) | SRS Eligible |
|---|---|---|---|
| Prudential PRULink Save Plus | 2.0–2.5% p.a. | ~4.0% p.a. | Yes |
| AIA Guaranteed Protect Plus | 2.5–3.0% p.a. | ~4.25% p.a. | Yes |
| NTUC Income Gro Saver Flex Pro | 1.5–2.0% p.a. | ~3.5% p.a. | Select tenors |
| Great Eastern GREAT Flexi Plus | 1.8–2.3% p.a. | ~3.8% p.a. | Yes |
Source: Insurer product brochures (Oct 2026). Projected returns are at LIA benchmark 4.25% p.a. — not guaranteed.
When comparing plans, always look at the surrender value schedule — most endowment plans penalise early termination heavily in the first 3–5 years. Only commit what you can lock away for the full tenor.
SRS Connection: Using Both CPF LIFE and Endowment Together
One of the best ways to maximise both products is through the Supplementary Retirement Scheme (SRS). SRS contributions are tax-deductible (capped at $15,300 for Singaporeans/PRs per year), and withdrawals after age 63 are taxed at just 50% of the applicable rate.
A common retirement strategy for high-income Singaporeans:
- CPF LIFE (FRS or ERS): covers core living expenses from age 65 (lifelong, inflation-linked optional)
- SRS endowment plan: matures at age 63–65, providing a lump sum or income stream to bridge the gap before CPF LIFE kicks in
- S-REITs or dividend ETFs (taxable account): supplement for travel, healthcare, lifestyle
For the full picture on SRS allocation, read our guide on Singapore T-bills 2026 guide and the Singapore Savings Bonds guide to compare all low-risk fixed-income options.
To compare robo-advisers that handle SRS, look at Endowus (referral code 2V343) and Syfe (referral code SRPRFFFCD) — both support SRS accounts and offer managed endowment or income portfolios.
The Verdict: Which Should You Choose?
For the vast majority of Singapore retirees, CPF LIFE is the superior retirement income product. It offers lifelong payouts, a government-guaranteed 4% RA return, inflation-linked option, and zero longevity risk — all at no cost to the policyholder beyond their CPF contributions.
Endowment plans are best used as a complement to CPF LIFE, not a replacement — particularly for SRS deployment, legacy planning, or targeted savings goals with a fixed timeline.
The optimal retirement portfolio: maximise CPF LIFE (FRS or ERS) → use SRS endowment for bridge income and tax savings → supplement with S-REITs for dividend income or a robo-adviser portfolio via Endowus.
Frequently Asked Questions
Is CPF LIFE better than an endowment plan for retirement?
Can I use SRS to buy an endowment plan?
What happens to my CPF LIFE if I die early?
How do I choose between BRS, FRS, and ERS for CPF LIFE?
What are the risks of endowment plans?
Can I have both CPF LIFE and an endowment plan?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.