INTEGRATED SHIELD PLAN REVIEW · SINGAPORE 2026
PRUShield 2026 Review: Is It Worth It?
How PRUShield stacks up against AIA, Great Eastern and NTUC Income — and who should (and shouldn’t) buy it
By The Kopi Notes | Last updated: September 2026 | 📖 14 min read
TABLE OF CONTENTS
- TL;DR — The Verdict Up Front
- What Is PRUShield? Quick Overview
- PRUShield’s Strengths in 2026
- PRUShield’s Weaknesses: Honest Gaps
- PRUShield vs AIA HealthShield Gold Max
- PRUShield vs Great Eastern SupremeHealth
- PRUShield vs NTUC Enhanced IncomeShield
- Who Should Buy PRUShield (5 Scenarios)
- Who Should Look Elsewhere
- The Bottom Line
- Frequently Asked Questions
Not financial advice. All figures are for educational reference only. Speak to a MAS-licensed financial adviser before making any decisions about your Integrated Shield Plan.
TL;DR
- PRUShield is a solid, mid-market ISP with the fastest claims speed in Singapore (median 0 days, per MOH data)
- It is not the cheapest — NTUC Income’s Enhanced IncomeShield undercuts it significantly at most tiers
- Its annual limits (especially Premier at $1.2M base) are lower than AIA and Singlife at the private hospital tier
- The new PRUExtra Care Series riders (April 2026) cut premiums 30–45% but expose you to the deductible ($3,500) — a trade-off worth understanding
- Best for: people who value fast claims, use Prudential’s PRUPanel Connect network, or want the retrenchment waiver and critical illness benefit baked into their rider
What Is PRUShield? Quick Overview
PRUShield is Prudential’s Integrated Shield Plan (ISP) — one of seven ISPs approved by the Ministry of Health in Singapore. It sits on top of your mandatory MediShield Life coverage to give you access to higher ward classes and private hospitals, with more generous claim limits.
There are three plan tiers:
| Plan | Ward Coverage | Annual Limit | Premium (Age 31–35) |
|---|---|---|---|
| PRUShield Standard | B1 restructured | $200,000 | ~$63/yr |
| PRUShield Plus | Class A restructured | $600,000 | ~$119/yr |
| PRUShield Premier | Private hospital | $1.2M ($2M at panel) | ~$300/yr |
For full premium tables and a deep dive on plan mechanics, see our PRUShield Premium Guide 2026. This review focuses on the decision question: how does PRUShield actually compare to its rivals, and is it the right plan for you?
PRUShield’s Strengths in 2026
Before we dig into the comparisons, it’s worth understanding what PRUShield genuinely does well. These aren’t just marketing claims — they’re backed by data.
1. Fastest claims in the industry. MOH publishes median claims processing times for all ISPs. PRUShield’s median is 0 days — most claims are processed on the same day. The 75th percentile is 1 day. For context, some competitors take 3–7 days at the 75th percentile. When you’re in hospital and need a Letter of Guarantee (LOG) to avoid paying upfront, speed matters.
2. PRUPanel Connect network. Choosing panel specialists and hospitals boosts PRUShield Premier’s effective annual limit from $1.2M to $2M — a meaningful increase. It also allows PRUExtra Premier Care premiums to stay level at renewal if all claims are panel-based. The PRUPanel Connect network includes several major private hospitals and specialist clinics across Singapore.
3. Rider perks with the new PRUExtra Care Series. Since April 2026, the new riders include benefits old riders didn’t have: a Critical Illness benefit (up to $100,000 additional annual limit if hospitalised due to CI), a retrenchment waiver (12 months of rider premiums waived if you’re retrenched and remain unemployed for 6+ months), and PRUWell Reward (20% premium discount at renewal if issued clean and made no claims). For a detailed breakdown, see our PRUExtra Care Series review.
4. Claims-based pricing incentive. If all your PRUShield Premier claims are at panel specialists and hospitals, your PRUExtra Premier Care rider premium stays level at renewal — you’re not penalised for using your insurance, as long as you use it within the panel.
5. Strong financial backing. Prudential Assurance Company Singapore is part of the Prudential plc group. As an established insurer with a long Singapore history, PRUShield carries the reputational weight that comes with that.
PRUShield’s Weaknesses: Honest Gaps
No ISP is perfect, and PRUShield has genuine gaps you should weigh.
1. Not the cheapest at any tier. At Class A ward, NTUC Income’s Enhanced IncomeShield A Plus undercuts PRUShield Plus meaningfully. At the private hospital tier, Income Preferred is about $75 per year cheaper. Over a decade, that’s real money — especially before you factor in riders.
2. Lower annual limits at private hospital tier. PRUShield Premier’s base limit of $1.2M is below AIA HealthShield Gold Max A ($2M), Singlife MyShield Plan 1 ($2M), and NTUC Income Enhanced IncomeShield Preferred ($1.5M). While the $2M panel limit partially closes this gap, you need to stick to PRUPanel Connect providers to access it — which restricts your specialist choice.
3. PRUShield Standard has no pre/post-hospitalisation coverage. If you’re on the entry-level plan, you get no coverage for specialist consultations, physiotherapy, or follow-up scans before and after a hospital stay. That’s a real gap — those costs add up. Most competitors’ standard plans include at least some pre/post coverage.
4. April 2026 rider changes increased out-of-pocket exposure. The new PRUExtra Care riders no longer cover the deductible ($3,500 for private hospitals). Your annual co-payment cap also doubled from $3,000 to $6,000. While premiums dropped 30–45%, your worst-case annual out-of-pocket exposure is higher than before. This affects everyone who buys a new rider from April 2026 onwards.
5. Claims-based pricing for riders. If you make claims in a given year with providers outside the PRUPanel Connect network, your rider premium may rise at renewal. The panel lock-in to avoid premium increases can feel restrictive if your preferred specialists aren’t on the panel.
PRUShield vs AIA HealthShield Gold Max
AIA is one of PRUShield’s closest rivals. Both are established brands with wide networks. Here’s how they compare at the two most popular tiers — Class A and Private Hospital:
Class A Ward: PRUShield Plus vs AIA Gold Max B
| Feature | PRUShield Plus | AIA Gold Max B |
|---|---|---|
| Annual Premium (Age 31–35) | ~$119 | ~$138 |
| Annual Limit | $600,000 | $600,000 |
| Pre/Post Hospitalisation | 180 / 365 days | 13 mths / 13 mths |
| Median Claims Time (MOH) | 0 days | 1 day |
Verdict at Class A: PRUShield Plus is $19/yr cheaper with similar benefits. AIA’s 13-month post-hospitalisation coverage is longer than PRUShield’s 365 days (about the same) but AIA’s 13-month pre-hospitalisation window is longer than PRUShield’s 180 days. PRUShield’s faster claims processing is an edge. On pure value, PRUShield Plus wins narrowly.
Private Hospital: PRUShield Premier vs AIA Gold Max A
| Feature | PRUShield Premier | AIA Gold Max A |
|---|---|---|
| Annual Premium (Age 31–35) | ~$300 | ~$360 |
| Annual Limit (base) | $1.2M ($2M panel) | $2M |
| Pre/Post Hospitalisation | 180 / 365 days | 13 mths / 13 mths |
| Median Claims Time (MOH) | 0 days | 1 day |
| Annual Premium Difference | PRUShield $60/yr cheaper | |
Verdict at Private Hospital: PRUShield Premier is $60/yr cheaper. AIA offers a higher base annual limit ($2M vs $1.2M) and longer pre-hospitalisation coverage. PRUShield closes the limit gap to $2M if you use panel providers. If you’re willing to stay within PRUPanel Connect, PRUShield offers good value. If you want maximum flexibility with no panel restriction, AIA is the stronger choice.
For a full AIA review, see our AIA HealthShield Gold Max review.
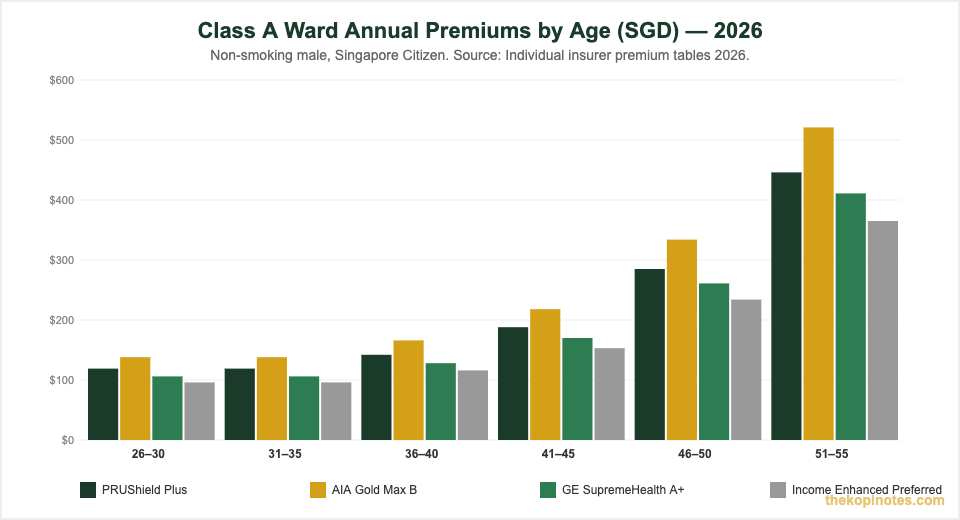
Annual premiums at Class A ward tier by age group 2026. Source: Individual insurer premium tables, effective May 2026. Data verified as at 12 September 2026.
PRUShield vs Great Eastern SupremeHealth
Great Eastern’s GREAT SupremeHealth is a popular choice, particularly its A Plus tier (Class A ward). Here’s how it stacks up against PRUShield:
Class A Ward: PRUShield Plus vs GE SupremeHealth A Plus
| Feature | PRUShield Plus | GE SupremeHealth A Plus |
|---|---|---|
| Annual Premium (Age 31–35) | ~$119 | ~$106–123 |
| Annual Limit | $600,000 | $1,000,000 |
| Pre/Post Hospitalisation | 180 / 365 days | 120 / 365 days |
| Median Claims Time (MOH) | 0 days | 3 days |
Verdict at Class A: Great Eastern’s A Plus offers a significantly higher annual limit ($1M vs $600K) at a similar or lower price point. That’s a material difference — if you end up with a complex illness requiring extended treatment, $600K can run out faster than you think. PRUShield’s faster claims processing (0 vs 3 days median) is an advantage, and its longer pre-hospitalisation coverage (180 vs 120 days) is useful. But on pure value, GE SupremeHealth A Plus edges PRUShield Plus on the limit-to-price ratio.
Private Hospital: PRUShield Premier vs GE SupremeHealth P Plus
At the private hospital tier, PRUShield Premier (~$300/yr) is slightly cheaper than GE P Plus (~$322/yr). PRUShield’s base limit of $1.2M is lower than GE’s $1.5M. PRUShield’s panel limit of $2M exceeds GE here. Claims speed remains PRUShield’s differentiator (0 vs ~3–5 days median).
For a full GE review, see our Great Eastern SupremeHealth guide.
PRUShield vs NTUC Enhanced IncomeShield
NTUC Income’s Enhanced IncomeShield is Singapore’s price leader among major ISPs. It consistently undercuts competitors at every tier, making it a strong consideration for cost-conscious buyers.
| Feature | PRUShield Premier | Income Enhanced Preferred |
|---|---|---|
| Annual Premium (Age 31–35) | ~$300 | ~$225 |
| Annual Limit | $1.2M ($2M panel) | $1.5M |
| Pre/Post Hospitalisation | 180 / 365 days | 180 / 365 days |
| Annual Premium Savings | Income is ~$75/yr cheaper | |
| Over 10 Years | $750+ in savings with Income | |
| Median Claims Time (MOH) | 0 days | ~7 days |
Verdict vs Income: NTUC Income is dramatically cheaper ($75/yr less at age 31–35 for private hospital) and offers a higher base annual limit. That’s a compelling value case. The significant trade-off is claims speed — Income’s median of 7 days at the 75th percentile vs PRUShield’s 0 days is a real operational difference when you’re in hospital needing a LOG. If speed of claims doesn’t matter to you and you want to keep premiums low, Income is hard to beat on pure economics.
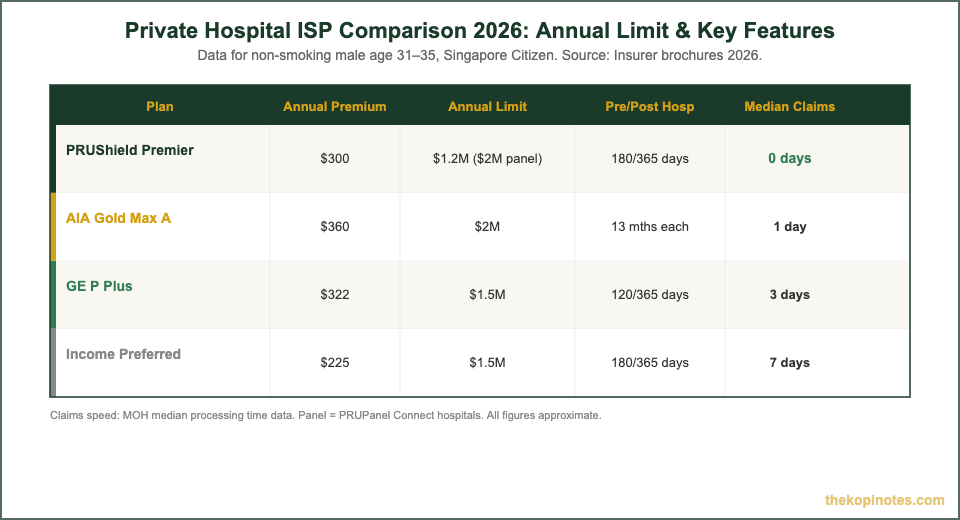
Private hospital ISP comparison 2026 — premium, annual limit, and claims speed. Sources: Individual insurer brochures and MOH ISP comparison data, 2026. Data verified as at 12 September 2026.
For a full ISP comparison across all 7 providers, see our Singapore integrated shield plan comparison 2026.
Who Should Buy PRUShield: 5 Scenarios
Instead of a one-size-fits-all recommendation, here are five specific scenarios where PRUShield is likely the right choice.
Scenario 1: You’ve had a claim experience where a slow LOG cost you money or stress. If you’ve been in hospital and waited days for the insurer to issue a Letter of Guarantee — leaving you to pay upfront or worry about whether your claim would be approved — PRUShield’s 0-day median claims processing directly solves this problem. This is the plan for people who’ve learned the hard way that claims speed matters.
Scenario 2: You already use PRUPanel Connect specialists. If your trusted cardiologist, oncologist, or GP is on the PRUPanel Connect network, PRUShield Premier becomes significantly more attractive — your effective annual limit jumps to $2M and your rider premiums can stay level at renewal. Check the panel list on the Prudential Singapore website before you decide.
Scenario 3: You’re worried about retrenchment. In an uncertain economic environment, the PRUExtra Premier Care and PRUExtra Preferred Care riders’ retrenchment waiver — 12 months of rider premiums waived if you’re retrenched and unemployed for 6+ consecutive months — is a meaningful safety net. No other major ISP rider currently includes this benefit.
Scenario 4: You have existing Prudential life coverage and want one adviser relationship. Managing your insurance through one adviser and one insurer simplifies the experience considerably — consolidated annual reviews, a single contact for claims, and a consistent relationship. If your current Prudential adviser has been reliable, PRUShield is a natural addition to your portfolio.
Scenario 5: You’re buying for a young family and want the CI benefit built into your rider. PRUExtra Care riders include an additional $100,000 annual policy limit if you’re hospitalised due to early, intermediate, or late-stage critical illness. For a parent or family breadwinner, having this CI safety net inside your ISP rider — without a separate CI policy — adds meaningful coverage depth.
Who Should Look Elsewhere
Price-first buyers. If your primary criterion is minimising annual premiums, NTUC Income Enhanced IncomeShield consistently wins. Over 20–30 years of premiums, the savings compound significantly — potentially enough to fund a significant portion of your deductible exposure several times over.
Those wanting maximum annual limits with no panel restriction. If you want a $2M annual limit and the freedom to choose any private specialist in Singapore without worrying about PRUPanel Connect membership, AIA HealthShield Gold Max A offers the highest base limit at a mid-range price and no panel requirement to access it.
Complex pre-existing conditions where GE’s products may better match your needs. GE SupremeHealth’s A Plus tier offers $1M annual limit at Class A prices comparable to PRUShield Plus — a stronger limit-to-price ratio for the Class A tier. If you’re primarily targeting restructured hospital Class A coverage rather than private hospital, GE deserves strong consideration.
Use our Insurance Gap Calculator to model how much coverage you actually need before choosing a plan tier.
The Bottom Line
PRUShield is a genuinely good ISP — but it’s not the best at everything, and the right choice depends on what you value most.
Our Summary Verdict
| Claims speed: | ✅ Best in class (0-day median) |
| Annual limits: | ⚠️ Lower than AIA at private hospital tier (unless panel) |
| Premiums: | ⚠️ Mid-market — not the cheapest (Income is cheaper) |
| Rider perks: | ✅ CI benefit + retrenchment waiver are unique differentiators |
| Out-of-pocket (post Apr 2026): | ⚠️ Higher deductible exposure ($3,500) with new riders |
| Overall: | Best for: fast claims, PRUPanel users, retrenchment risk |
Before you decide, speak to a MAS-licensed financial adviser who can model the full premium-plus-out-of-pocket picture for your age, health profile, and income. A good adviser will compare PRUShield against at least two alternatives before making a recommendation. This analysis is for educational reference only — not financial advice.
Data verified as at 12 September 2026. Premium figures are approximate based on publicly available insurer data effective May–September 2026. Always refer to official insurer brochures and MAS-regulated advisers for exact figures and personalised advice.
Frequently Asked Questions
Is PRUShield cheaper than AIA HealthShield?
At the private hospital tier, PRUShield Premier (~$300/yr for age 31–35) is about $60/yr cheaper than AIA HealthShield Gold Max A (~$360/yr). At Class A ward, PRUShield Plus (~$119/yr) is slightly cheaper than AIA Gold Max B (~$138/yr). However, NTUC Income’s Enhanced IncomeShield undercuts both — Enhanced Preferred (private hospital) is around $225/yr, making it the cheapest major private hospital ISP in Singapore.
What is PRUPanel Connect and do I need to use it?
PRUPanel Connect is Prudential’s network of approved specialist doctors and private hospitals in Singapore. You are not required to use it — PRUShield Premier covers you at any private hospital in Singapore. However, using panel providers gives you two key benefits: (1) your effective annual limit rises from $1.2M to $2M, and (2) your PRUExtra Premier Care rider premiums can remain level at renewal if all claims are panel-based. If your preferred specialists are on the panel, the benefits are meaningful.
How does PRUShield compare to Great Eastern SupremeHealth for Class A ward?
Great Eastern SupremeHealth A Plus offers a $1,000,000 annual limit at Class A ward — significantly higher than PRUShield Plus’s $600,000 limit — at a similar or slightly lower premium (~$106–123 vs ~$119/yr for age 31–35). PRUShield’s advantage is faster claims processing (0-day median vs GE’s ~3 days) and longer pre-hospitalisation coverage (180 vs 120 days). For pure limit-to-price value at Class A ward, GE SupremeHealth A Plus edges PRUShield Plus. For claims speed, PRUShield wins.
What happens to my PRUShield rider after the April 2026 changes?
If you had a PRUExtra CoPay rider before April 2026, it continues on its existing terms — you are not automatically switched. If you bought a rider between 27 November 2025 and 31 March 2026, you will transition to the new PRUExtra Care Series at your next renewal from 1 April 2028. New buyers from 1 April 2026 onward get the new PRUExtra Care Series, which is 30–45% cheaper but no longer covers the deductible. For a detailed breakdown of whether to switch, see our PRUExtra Care Series review.
Can I switch from PRUShield to another ISP?
Yes, you can switch ISPs at any time. However, if you have pre-existing conditions, a new insurer may apply exclusions for those conditions that your current PRUShield coverage may not have (since PRUShield would have covered you before those conditions developed). Switching ISPs as you age or develop health conditions carries real risk — the new insurer can underwrite you fresh. It’s recommended to speak to a MAS-licensed financial adviser before switching. If you’re healthy and young, switching is lower risk.
Which ISP has the fastest claims in Singapore?
According to MOH’s published ISP claims processing time data, PRUShield has the fastest median processing time — 0 days, meaning most claims are settled on the same day. Its 75th percentile is 1 day. NTUC Enhanced IncomeShield and some other ISPs have median times of 3–7 days. This matters most when you need a Letter of Guarantee (LOG) to avoid paying hospital bills upfront.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us. Not financial advice.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.