HSBC Life Shield Plan A Review 2026: Private Hospital Coverage, Premiums & Riders
Published: September 2026 · Category: Integrated Shield Plans
HSBC Life Shield Plan A is one of seven MOH-approved Integrated Shield Plans (ISPs) in Singapore — and the only one under the HSBC Life banner designed for private hospital access. With a S$2,500,000 annual limit and a standard room entitlement at private hospitals, Plan A sits at the top of the HSBC Life health insurance range. Add the Enhanced Care II rider and your out-of-pocket costs can drop to just 5% of eligible bills.
Not financial advice. All figures are for educational reference only. Data verified as at 22 September 2026. Source: HSBC Life official product page (correct as at 1 April 2026) and MOH ISP comparison (as at 1 June 2026).
- Plan A gives you S$2,500,000 annual coverage for private hospital standard rooms — the highest limit in the HSBC Life range
- Add the Enhanced Care II rider to cap your share of eligible bills at 5% (excluding the deductible)
- SavvyClaim Reward gives you up to 20% off premiums when you make smart healthcare choices
- Note: HSBC Life Singapore is being sold to Allianz (expected completion H1 2027) — your existing policy terms are unaffected
📋 In This Review
What Is HSBC Life Shield Plan A?
HSBC Life Shield is a MediSave-approved Integrated Shield Plan (ISP). It sits on top of your MediShield Life — the basic government health plan that every Singapore Citizen and PR has. An ISP extends your coverage to higher ward classes and private hospitals.
Plan A is the top-tier option within the HSBC Life Shield range. It covers you for a standard room at any private hospital in Singapore — think Mount Elizabeth, Gleneagles, Parkway East, Thomson Medical, and others. If you want the option of skipping public hospital queues and choosing your own specialist, Plan A is the one to look at.
That S$2.5 million annual limit resets every policy year. There is no lifetime cap, which means Plan A can keep covering you no matter how many times you need to claim — as long as each policy year’s bills don’t exceed S$2.5 million.
Plan A is available to Singapore Citizens and Permanent Residents between the ages of 15 days and 75 years (Age Next Birthday). Guaranteed renewability means HSBC Life cannot refuse to renew your plan as you age — so your coverage stays in place for life, subject to premium payments.
Plan A vs Plan B vs Standard Plan
HSBC Life Shield comes in three tiers. Here’s how they compare side by side:
| Feature | Plan A | Plan B | Standard |
|---|---|---|---|
| Maximum Annual Limit | S$2,500,000 | S$1,000,000 | S$200,000 |
| Ward Entitlement | Private hospital standard room | Class A (public) | Class B1 (public) |
| Major Organ Transplant | As charged | As charged | Not covered |
| Inpatient Pregnancy Complications | As charged | As charged | General benefit |
| Lifetime Limit | None | None | None |
| Enhanced Care II Rider Available? | ✅ Yes | ✅ Yes | ✅ Yes |
Source: HSBC Life Shield product page, correct as at 1 April 2026 (MOH-verified). MOH ISP Comparison as at 1 June 2026.
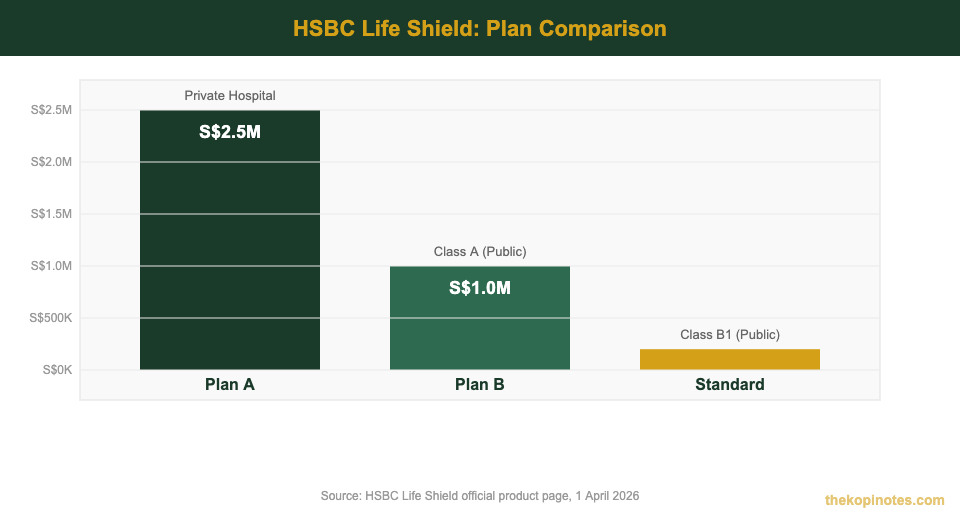
HSBC Life Shield plan annual limits. Source: HSBC Life Singapore, 2026.
From an MOH ISP comparison perspective, Plan A sits in the Private Hospital Plans category alongside six other plans from AIA, Great Eastern, Income, Prudential, Raffles Shield, and Singlife. If you’re comparing ISPs for private hospital coverage, these are the plans to look at together.
Premiums & MediSave Payments
HSBC Life Shield Plan A premiums are fully payable from your CPF MediSave account, up to the Additional Withdrawal Limits (AWLs) set by MOH. This means you typically don’t need to pay cash for the base plan premium if your MediSave balance is sufficient.
As a rough benchmark, premiums for Plan A for ages 31–35 are approximately S$292 per year. Like all ISPs, premiums increase as you age — the jump from your 50s into your 60s is the biggest one to plan for.
First-year discount: HSBC Life offers a 10% discount on your first-year premium (base plan and rider) as a new sign-up. If you’re a public officer, you get an additional 10% discount on the first-year base plan premium for yourself and your immediate family members. Terms apply — check the HSBC Life website for the latest conditions.
| Who You Are | First-Year Discount |
|---|---|
| New sign-up (any Singaporean/PR) | 10% off base plan + rider |
| Public officer | 10% + additional 10% off base plan |
Source: HSBC Life Shield product page, correct as at 1 April 2026. Terms & conditions apply.
For a complete premium breakdown by age, download the official HSBC Life Shield premium tables (PDF) from the HSBC Life Singapore website.
If you’re thinking about which ISP fits your budget, you might also find our ISP copayment guide for 2026 useful for comparing what you’d actually pay out of pocket across different plans.
Enhanced Care II Rider: What It Covers
The base HSBC Life Shield Plan A covers your hospitalisation bills — but after deductibles and coinsurance, you can still face a meaningful out-of-pocket amount. That’s where the HSBC Life Enhanced Care II rider comes in.
With the rider attached to Plan A, HSBC Life covers up to 95% of your eligible hospitalisation bills, after deducting the annual deductible. That means your share of an eligible hospital bill is just 5%.
The Enhanced Care II rider also bundles in a range of outpatient benefits:
- Outpatient dementia cover — up to S$500 per policy year for consultation and prescriptive medication (new benefit)
- Emergency outpatient treatment due to an accident
- Fractures, dislocations and sports injuries
- Dengue fever, HFMD, food poisoning
- Ambulance and taxi charges
- Accommodation charges for immediate family members
- Extensive outpatient cancer drug treatments and services
The rider is available for life assured aged 15 days to 75 years (ANB). As with all ISP riders from April 2026, the rider does not cover the annual deductible — you’re responsible for that portion each policy year.
If you want to understand more about how deductibles and rider changes work across all ISPs, see our full guide to ISP rider changes 2025–2026.
SavvyClaim Reward: How to Lower Your Premiums
One of the more distinctive features of HSBC Life Shield Plan A is the SavvyClaim Reward programme. This is a discount system built into the Enhanced Care II rider for Plan A — the idea is simple: make smart healthcare choices, and HSBC Life rewards you with lower premiums at renewal.
There are 5 reward levels. Your level moves up or down at each annual renewal depending on your claim behaviour during the review period:
| Reward Level | Premium Discount |
|---|---|
| Level 1 | 10% |
| Level 2 | 12% |
| Level 3 | 15% |
| Level 4 | 18% |
| Level 5 | 20% |
Source: HSBC Life SavvyClaim Reward FAQs, 2026.
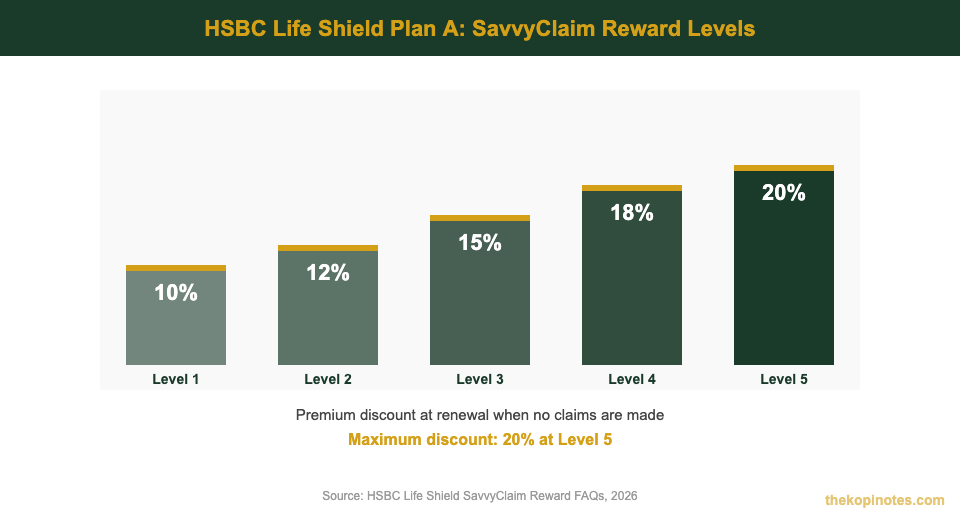
SavvyClaim Reward discount levels. Source: HSBC Life Shield, 2026.
Three practical tips to maintain or improve your reward level:
- Claim from your employer’s group policy first — if your company covers the bill, your HSBC Life plan gets a lower claim count
- Recover claims from HSBC Life after group insurance pays — HSBC Life has a claims recovery process that doesn’t penalise you for this
- Use restructured hospitals when possible — lower bills mean less impact on your claim score
For context on how ISP costs fit into your broader financial picture, our Singapore retirement planning calculator can help you project healthcare costs over a 30-year horizon.
What Plan A Does NOT Cover
Before you sign up, here’s what HSBC Life Shield Plan A excludes:
- Pre-existing conditions — unless specifically assessed and approved under their inclusive underwriting option
- Intentional self-inflicted injury or illness
- Drug or alcohol abuse
- STD, HIV or AIDS-related treatments
- Plastic surgery procedures
It’s also worth noting that the deductible applies every policy year, and the rider does not cover the deductible — that amount is always your responsibility. The annual deductible under Plan A is S$3,500 for policyholders aged 80 and below.
MOH data shows that 69% of IP claims that did not result in a payout were cases where the claim amount was less than or equal to the deductible. This is the single biggest reason claims don’t pay out — so plan accordingly if your bills are likely to be small.
HSBC Life + Allianz Sale: What It Means for You
In 2026, HSBC announced that it has agreed to sell HSBC Life Singapore to Allianz, one of the world’s largest global insurers. The transaction is expected to complete in the first half of 2027, subject to regulatory approval.
For existing HSBC Life Shield Plan A policyholders, the official position is clear: your existing policy terms, benefits, and premiums are unaffected by this announcement. HSBC Life continues to operate normally until the transaction completes.
What will likely happen after the acquisition:
- The insurer’s brand changes from HSBC Life to Allianz (or a rebranded entity)
- Policy conditions and benefits at point of acquisition are grandfathered
- Future premium pricing will be at Allianz’s discretion — but regulated by MAS
If you’re considering buying HSBC Life Shield Plan A now, this sale is worth monitoring — but it’s not a reason to avoid the plan today. All ISPs in Singapore are regulated by MAS and covered by the Policy Owners’ Protection Scheme administered by SDIC.
Our Verdict: Is HSBC Life Shield Plan A Worth It?
HSBC Life Shield Plan A is a solid private hospital ISP. The S$2,500,000 annual limit is among the highest available, the SavvyClaim Reward system is a genuinely useful incentive to be a smart healthcare consumer, and the same-day claims processing (MOH verified, median 0 days, Apr–Jun 2026) is best-in-class.
Who Plan A is best for:
- You want to access private hospitals without large upfront out-of-pocket costs
- You or your family have complex healthcare needs requiring specialist access
- You want the highest annual coverage limit available within the HSBC Life range
Who might look elsewhere:
- You’re comfortable with public hospital Class A wards — Plan B is sufficient and cheaper
- You want the largest possible insurer network in Singapore (AIA or Great Eastern have larger policyholder bases)
For a broader comparison across all seven ISPs, the MOH ISP comparison page is the definitive reference. And for a quick check on how much your MediSave can cover, see our MediSave AWL guide for ISP premiums.
Frequently Asked Questions
What is the annual limit for HSBC Life Shield Plan A?
Which hospitals does HSBC Life Shield Plan A cover?
Does HSBC Life Shield Plan A cover pre-existing conditions?
What is the deductible for HSBC Life Shield Plan A?
What is the SavvyClaim Reward and how does it work?
Will the Allianz acquisition affect my HSBC Life Shield Plan A policy?
Can I pay HSBC Life Shield Plan A premiums with MediSave?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.