Maybank Fixed Deposit Rate Promotion Singapore 2026: Bundle vs Standalone vs Fresh Funds Explained
Updated 5 November 2026 · 7 min read
Maybank Singapore’s fixed deposit promotions offer up to 2.40% p.a. on 12-month placements in November 2026 — one of the stronger rates from a traditional bank this year. There are three distinct products: the Deposits Bundle Promo (best rates, requires a 10% fund-earmarking arrangement alongside your deposit), the Standalone Time Deposit (no conditions, slightly lower rate), and the Fresh Funds Promo (for new money moving into Maybank). All three require a minimum of S$20,000.
Not financial advice. All figures are for educational reference only. Data verified as at 5 November 2026.
Maybank Fixed Deposit Rates in November 2026
Maybank Singapore currently runs three separate fixed deposit promotions. Here is a complete snapshot of all available rates as at 5 November 2026:
| Product | Tenor | Interest Rate p.a. | Min. Deposit | Condition |
|---|---|---|---|---|
| Deposits Bundle Promo | 9 months | 2.25% | S$20,000 | 10% fund-earmarking |
| Deposits Bundle Promo | 12 months | 2.40% ⭐ | S$20,000 | 10% fund-earmarking |
| Standalone Time Deposit | 6 months | 2.10% | S$20,000 | None |
| Standalone Time Deposit | 9 months | 1.90% | S$20,000 | None |
| Standalone Time Deposit | 12 months | 2.10% | S$20,000 | None |
| Fresh Funds Promo | Varies | Up to 2.20% | S$20,000 | Incremental ADB in fresh funds |
Source: Growbeansprout, StashAway, singpromos.com — data as at 2–5 November 2026. ⭐ = highest available rate. All products require an existing Maybank savings or current account with Maybank2u access for online placement. Rates are promotional and subject to change without notice.
One important note that many depositors overlook: when your Maybank FD matures, it auto-renews at the prevailing board rate — not the promotional rate. The board rate is significantly lower (often 0.1–0.5% p.a.). Set a calendar reminder close to your maturity date so you can manually renew at the promotional rate, or move your funds elsewhere.
If you are comparing Maybank against every other bank, see our full highest fixed deposit rate Singapore roundup, which is updated monthly.
Bundle Promo: What Is the 10% Fund-Earmarking Requirement?
The Deposits Bundle Promo gives you Maybank’s highest FD rate — 2.25% for 9 months and 2.40% for 12 months. However, it comes attached to a condition that some depositors find confusing: you must commit 10% of your time deposit amount into a fund-earmarking arrangement.
In practice, this means that for every S$100,000 you place in the Bundle FD, S$10,000 must simultaneously be placed into a Maybank investment fund (a unit trust or similar product offered by Maybank). The fund investment and the FD are bundled together as a single product.
Key things to know about the Bundle Promo:
- The minimum is S$20,000 for the FD component, meaning your 10% fund earmarking is at least S$2,000 invested in a qualifying fund.
- The fund investment portion is not protected under the Singapore Deposit Insurance Corporation (SDIC) scheme — only the FD portion is covered (up to S$100,000 per depositor per institution under SDIC).
- Investment funds carry market risk — the value of the earmarked fund can go up or down, unlike the FD principal.
- You cannot redeem or switch the fund during the FD lock-in period (9 or 12 months) without potentially affecting the promotional rate.
- The combined product requires a Maybank investment account in addition to your bank account.
Who is the Bundle Promo best suited for? Depositors who already hold (or are open to holding) Maybank investment products, want the highest possible rate, and are comfortable with a small portion of their capital in a fund. If you prefer to keep 100% of your savings in guaranteed, SDIC-protected products, the Standalone Time Deposit is a cleaner option.
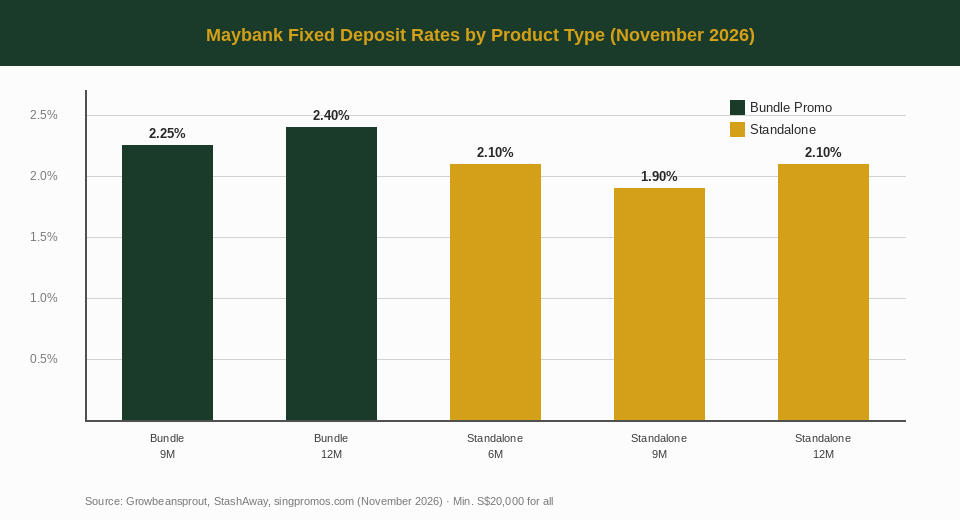
Maybank FD rates by product and tenor — Bundle Promo consistently pays 0.15–0.30% more than Standalone. Source: Growbeansprout, StashAway (November 2026).
Standalone Time Deposit: No Conditions, Straightforward
If the Bundle Promo’s fund-earmarking requirement doesn’t appeal to you, Maybank’s Standalone Time Deposit is the alternative. There are no bundled products, no investment accounts needed, and no additional conditions beyond having a Maybank savings or current account.
Current Standalone rates (November 2026): 2.10% for 6 months, 1.90% for 9 months, and 2.10% for 12 months. Interestingly, the 9-month rate (1.90%) is lower than both the 6-month and 12-month rates — this pricing is intentional, as Maybank incentivises shorter or longer lock-ins over the mid-tenor.
When Standalone makes more sense than Bundle:
- You want your entire deposit to be SDIC-insured (up to S$100,000).
- You don’t have an existing Maybank investment account and don’t want to open one.
- You’re depositing exactly S$20,000 (the minimum) and don’t want to split it between FD and a fund.
- You prefer simplicity — one product, one rate, one maturity date.
At 2.10% for 12 months on S$50,000, a Standalone FD earns you approximately S$1,050 in interest over the year. That’s a straightforward, predictable return with no moving parts.
For context, a 12-month Singapore Savings Bond (SSB) currently yields around 2.3–2.5% — slightly higher and also fully capital-guaranteed by the Singapore government (backed by MAS, not SDIC). SSBs are worth comparing if you have at least six months before needing the funds, though they have a S$200 minimum and a maximum per-person cap.
Fresh Funds Promo: For New Money Coming Into Maybank
Maybank’s Fresh Funds Promo is designed to attract new deposits from customers who don’t already hold significant balances with Maybank. It offers up to 2.20% p.a., which falls between the Standalone and Bundle rates.
The key requirement is that the deposited amount must come from outside Maybank — it must represent an incremental increase in your Average Daily Balance (ADB) at Maybank over the previous period. In other words, you cannot simply transfer existing Maybank funds from one account to another and qualify for the Fresh Funds rate.
What qualifies as fresh funds:
- Funds transferred in from another bank (DBS, OCBC, UOB, etc.)
- Salary credits from a new employer that weren’t previously going into Maybank
- Proceeds from maturing fixed deposits at other banks
- New cash deposits at the branch
Maybank will verify your ADB figures at the point of placement to confirm the funds qualify. If you’re consolidating funds from multiple banks or switching your savings relationship to Maybank, the Fresh Funds Promo is worth considering — the 2.20% rate beats the Standalone Time Deposit’s 12-month rate of 2.10% without the investment condition of the Bundle Promo.
Thinking more broadly about where to park your savings? Our passive income Singapore guide compares FDs, T-bills, SSBs, REITs, and dividend stocks to help you build a diversified savings and investment strategy.
How to Place a Maybank Fixed Deposit Online (Step-by-Step)
Maybank allows you to place fixed deposits online via Maybank2u — no branch visit required. Here is what you need and how the process works:
Prerequisites:
- An active Maybank savings or current account (you cannot place a FD without one)
- Maybank2u internet banking access (or the Maybank app)
- A minimum of S$20,000 available in your Maybank account to transfer into the FD
- For the Bundle Promo: a Maybank investment account as well
Step 1: Log in to Maybank2u
Visit www.maybank2u.com.sg and sign in with your username and PIN. If you have Multi-Factor Authentication (MFA) set up, approve the login request via your phone.
Step 2: Navigate to Fixed Deposits
In the main menu, look for “Save & Invest” or “Products”, then select “Time Deposit / Fixed Deposit”. Alternatively, some versions of Maybank2u show it directly under “Accounts”.
Step 3: Select the Promotional Rate
Choose between the Deposits Bundle Promo, Standalone Time Deposit, or Fresh Funds Promo. Select your preferred tenor (6, 9, or 12 months) and confirm the displayed interest rate matches what you expect.
Step 4: Enter Deposit Amount and Debit Account
Key in the amount (minimum S$20,000) and select which Maybank account the funds should be debited from. The system will show your projected interest at maturity.
Step 5: Review Maturity Instructions
You can choose what happens at maturity: “Renew principal only”, “Renew principal and interest”, or “Credit to account”. Important: if you leave it on auto-renew, it renews at the board rate — not the promotional rate. Set an alert to come back and re-price at maturity.
Step 6: Confirm and Receive Confirmation
Review the summary screen, enter your OTP when prompted, and submit. You will receive an email confirmation and can view the placement under “Accounts → Time Deposits” in Maybank2u.
If you are placing the Fresh Funds Promo, you may need to visit the branch or call Maybank’s customer service to confirm that your funds qualify as incremental ADB — the online portal may not always process this automatically.
Need help figuring out how much your fixed deposit earns over time? Use our Singapore retirement planning calculator to model how compounding interest from FDs, T-bills, and other instruments adds up toward your financial goals.
Maybank vs Other Banks: 12-Month FD Rates in November 2026
How does Maybank stack up against the rest of the market? Here is a comparison of the best available 12-month fixed deposit rates from major Singapore banks and finance companies as at November 2026:
| Bank / Institution | Best 12M Rate p.a. | Min. Deposit | Condition |
|---|---|---|---|
| Maybank (Bundle Promo) | 2.40% | S$20,000 | 10% fund-earmarking |
| RHB Premier | 2.20% | S$50,000 | Premier account required |
| Maybank (Fresh Funds Promo) | Up to 2.20% | S$20,000 | Fresh/incremental funds only |
| CIMB | 2.15% | S$1,000 | None (online placement) |
| Hong Leong Finance | 1.90% | S$20,000 | None |
| OCBC | 1.85% | S$5,000 | None (12M promo) |
| UOB | 1.70% | S$10,000 | Fresh funds preferred |
| MariBank | 1.48% | S$100 | None — digital bank |
| DBS/POSB | 1.00% | S$1,000 | None |
Source: Bank websites, Growbeansprout (November 2026). Rates shown are the best available 12-month rate from each institution — not all accounts may qualify. Always verify current rates directly with the bank before placing a deposit.
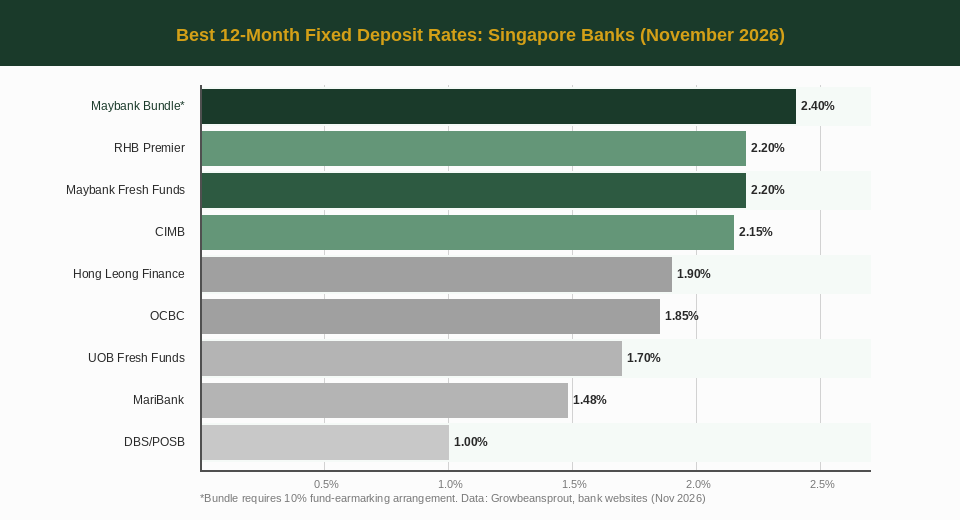
Maybank Bundle leads Singapore bank 12-month FD rates in November 2026 at 2.40% p.a. CIMB’s rate is notable for having no conditions and a low S$1,000 minimum. Source: Growbeansprout, bank websites (November 2026).
A few things stand out from this comparison. CIMB is worth highlighting: at 2.15% for 12 months with no conditions and a S$1,000 minimum, it offers the best combination of accessibility and rate for depositors who cannot meet Maybank’s S$20,000 minimum. For a comprehensive view of all Singapore bank rates, see our Singapore bank fixed deposit rate 2026 comparison.
If you’re considering whether fixed deposits are the right tool at all — versus Singapore T-bills (currently yielding around 1.95% at the last auction), SSBs, or money market funds — the answer depends on your time horizon and flexibility needs. FDs lock your money in; T-bills can be liquidated in the secondary market; SSBs allow early redemption with no penalty.
Who Should Use Maybank FD (and Who Shouldn’t)?
✅ Maybank FD makes sense if:
- You have at least S$20,000 to lock away for 6–12 months
- You already bank with Maybank and have Maybank2u set up
- You want to maximise your return and are comfortable with the Bundle Promo’s fund earmarking
- You’re bringing in fresh funds from another bank and qualify for the Fresh Funds Promo
- You want a traditional bank (not a digital bank) with an established branch network
⚠️ Consider alternatives if:
- You have less than S$20,000 — CIMB (S$1,000 min), MariBank (S$100 min), or SSBs (S$200 min) are more accessible
- You need flexibility to access your money before maturity — T-bills and SSBs allow this; FDs typically involve a penalty for early withdrawal
- You want the absolute best risk-free rate without conditions — SSBs may edge out the Standalone FD at 2.10–2.40% with higher government backing
- You don’t have a Maybank account and don’t want to open one — the account opening process adds friction
- Your deposit exceeds S$100,000 — only the first S$100,000 is SDIC-insured; consider spreading deposits across institutions
Fixed deposits work best as one component of a broader savings and investment strategy. Use our highest fixed deposit rate Singapore comparison to benchmark Maybank’s current rates against the latest market data before committing.
Frequently Asked Questions
What is the highest Maybank fixed deposit rate in November 2026?
Does Maybank FD require a minimum deposit?
Is Maybank fixed deposit covered by SDIC?
What happens to my Maybank FD when it matures?
Can I withdraw a Maybank FD before maturity?
Do I need a Maybank account to open a Maybank FD?
How does Maybank Bundle Promo compare to just doing a Standalone FD?
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice. Fixed deposit rates change frequently — always verify current rates directly with Maybank or your bank of choice before placing a deposit. The Kopi Notes does not receive any referral fees from Maybank for this article. All rate data was verified against third-party aggregators as at 5 November 2026. Singapore Deposit Insurance Corporation (SDIC) coverage limits and terms are subject to change — refer to www.sdic.org.sg for the latest information.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.