GXS Credit Card Review 2026: Who the 1.75% Cashback Card Suits (and Who Should Skip It)
GXS Bank’s new Grab and Singtel card, worked through with real spending numbers: where it beats Mari and Trust, and where the S$500 minimum and annual fee bite.
The GXS Credit Card, launched in August 2026, pays 1.75% uncapped cashback on local spending once you spend S$500 a month, 1.75% on Singtel bills, and 3% to 10% back in GrabCoins on Grab. It shines for heavy Grab users and overseas Grab rides. For most others, the S$500 minimum and the S$196.20 annual fee from year two make the no-fee Mari or Trust cards the simpler choice.
Not financial advice. Figures are for educational reference only. Data as at October 2026 unless noted. TKN may earn a referral reward if you sign up with our code.
Table of Contents
Contents (click to expand)
What is the GXS Credit Card?
GXS Bank is the digital bank owned by Grab and Singtel. On 17 August 2026 it launched the GXS Credit Card, a Visa card built around those two brands, according to GXS’s launch announcement.
It is a different product from GXS’s older FlexiCard, which has a fixed S$500 limit and no income requirement. The new card is a full credit card with a S$30,000 income requirement, uncapped cashback and an annual fee after the first year.
GXS Credit Card key facts
| Feature | GXS Credit Card |
|---|---|
| Launched | 17 August 2026 |
| Network | Visa |
| Local cashback | 1.75%, uncapped, if you spend at least S$500 a month on eligible non-Grab spend |
| Singtel bills | 1.75%, uncapped, no minimum spend |
| Grab in Singapore | 3% to 10% in GrabCoins, tiered (see below) |
| Grab overseas | 10% in GrabCoins, no minimum spend |
| Other overseas spend | No FX fee, but no cashback |
| Annual fee | S$196.20 (incl. GST); first year waived if approved by 31 Dec 2026 |
| Minimum income | S$30,000 a year (Singaporeans and PRs); S$120,000 for eligible foreigners |
| Interest rate | 29% a year |
| Late payment fee | S$100 |
Source: GXS Bank press release (17 Aug 2026); MoneySmart and MileLion reviews (Aug 2026). As at October 2026
How the cashback and GrabCoins work
The card has three reward streams: cashback on local spending, cashback on Singtel bills, and GrabCoins on Grab. Each has its own rules.
| Spend category | Rate | Condition |
|---|---|---|
| Local spend (non-Grab) | 1.75% cashback | At least S$500 eligible non-Grab spend in the statement month; nothing below that |
| Singtel bills | 1.75% cashback | None |
| Grab in Singapore: first S$499.99 | 3% GrabCoins | None |
| Grab in Singapore: next S$499.99 | 5% GrabCoins | Must also hit S$500 non-Grab spend |
| Grab in Singapore: from S$1,000 | 10% GrabCoins | Must also hit S$500 non-Grab spend |
| Grab overseas | 10% GrabCoins | None |
| Other overseas / foreign-currency spend | No cashback | No FX fee either |
Source: MoneySmart GXS Credit Card review (Aug 2026) and MileLion (Aug 2026); rates confirmed against GXS’s launch release where stated
The S$500 rule is the one to watch. Grab spending and foreign-currency spending do not count towards it, and neither do common exclusions such as insurance premiums, government payments, utilities, education, hospitals and e-wallet top-ups. Spend S$499 of eligible local spend in a month and you earn no 1.75% cashback at all.
The Grab tiers are also less generous than “up to 10%” suggests. The rates are marginal, so only spend above S$1,000 in a month earns 10%. MileLion worked out that someone spending S$1,000 a month on Grab averages about 4%.
The standout is overseas Grab: a flat 10% in GrabCoins with no minimum spend and no FX fee. For Grab rides and food in Bangkok, Kuala Lumpur or Jakarta, that is hard to beat.
What you really earn: GXS vs Mari
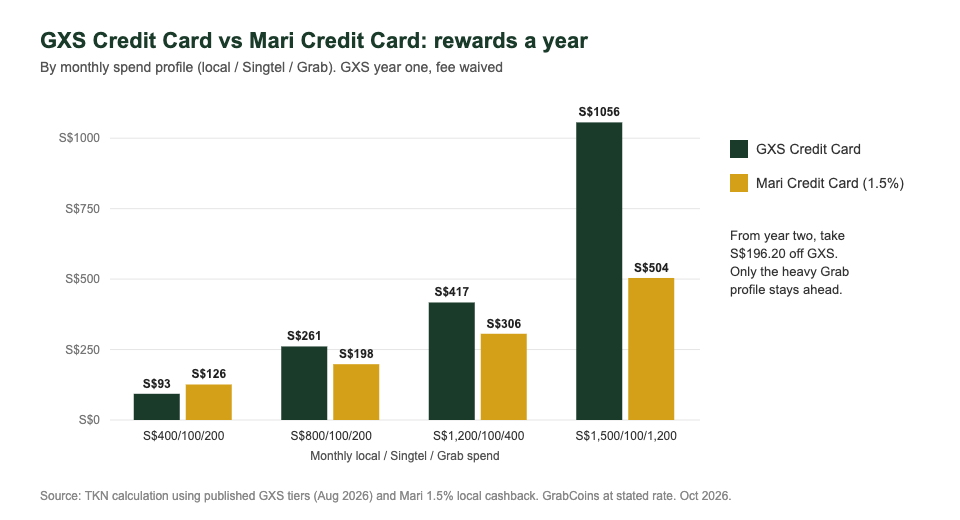
To see whether the GXS card is worth it, we compared it with the Mari Credit Card, which pays a flat 1.5% on eligible local spending with no minimum and no annual fee. See our Mari Credit Card review for the full details.
| Monthly spend profile | GXS a year | Mari (1.5% flat) a year | GXS after S$196.20 fee |
|---|---|---|---|
| S$400 local, S$100 Singtel, S$200 Grab | S$93 | S$126 | -S$229 vs Mari |
| S$800 local, S$100 Singtel, S$200 Grab | S$261 | S$198 | -S$133 vs Mari |
| S$1,200 local, S$100 Singtel, S$400 Grab | S$417 | S$306 | -S$85 vs Mari |
| S$1,500 local, S$100 Singtel, S$1,200 Grab | S$1,056 | S$504 | +S$356 vs Mari |
Source: TKN calculation using the published GXS tiers and Mari’s 1.5% on eligible local spend. GrabCoins counted at the stated rebate rate. Excludes overseas spend and the first-year fee waiver. October 2026
In year one, when the annual fee is waived, GXS comes out ahead for anyone who reliably spends S$500 a month on eligible local spend. At S$800 local spending, it earns about S$63 a year more than Mari.
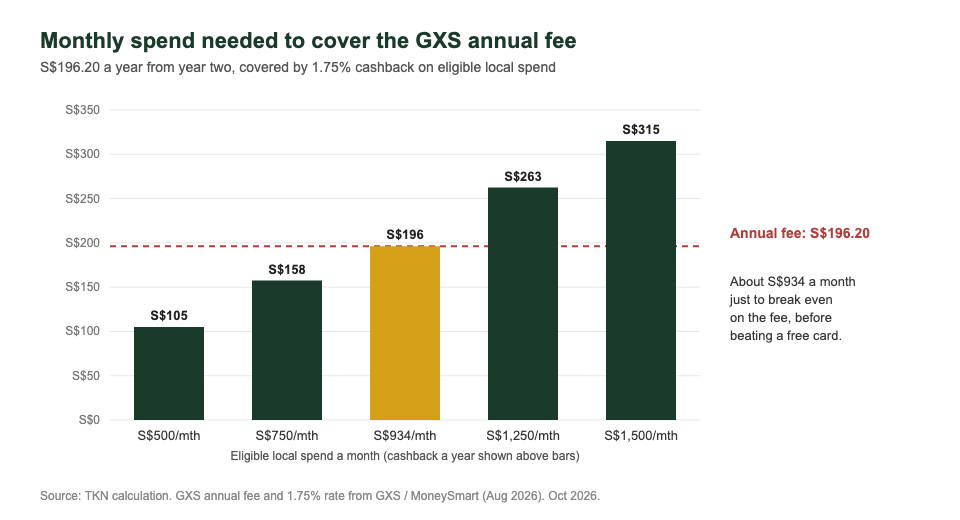
From year two the picture changes. To cover the S$196.20 fee with 1.75% cashback alone, you need about S$934 a month of eligible spending, before you even get ahead of a free card. Only the heavy Grab user in our last example comes out clearly better after the fee.
Two caveats apply. GrabCoins are not cash, and how much they are worth depends on how you use them; MileLion notes they stretch further during Grab’s monthly flash sales. And GXS may waive the fee in later years, but that is not promised.
The catches to know about
- All-or-nothing minimum. Miss S$500 of eligible local spend in a month and you lose that month’s 1.75% cashback entirely.
- Annual fee from year two. S$196.20 a year, with only the first year waived for approvals by 31 December 2026.
- No cashback on most overseas spending. Foreign-currency spend has no FX fee but earns nothing unless it is on Grab. For travel, a no-fee card that earns overseas, such as the Mari card, does better.
- GrabCoins only work on Grab. Fine if you use Grab daily, less useful if you do not.
- Possibly one GXS card only. MileLion reports that you cannot hold the FlexiCard and the GXS Credit Card at the same time. Check in the GXS app before applying.
- High interest. At 29% a year, any balance you carry wipes out the cashback. Pay in full every month.
GXS Credit Card vs GXS FlexiCard
GXS still offers the FlexiCard, and it suits a different person.
The FlexiCard has no minimum income, a fixed S$500 credit limit and no interest charges. Instead, carrying a balance costs a S$5 Flexi fee per billing cycle. It pays a random instant cashback of up to S$3 on each eligible transaction of S$10 or more, and charges a S$54.50 annual fee, waived for the first year.
For a fresh graduate or anyone building a credit history, the FlexiCard is the easier way in. For anyone earning S$30,000 or more who spends heavily on Grab, the new GXS Credit Card is the stronger card.
Who should get it (and who should skip it)
Good fit:
- Heavy Grab users spending S$1,000 or more a month on rides, food and groceries.
- Frequent travellers in Southeast Asia who use Grab abroad, thanks to 10% overseas Grab with no FX fee.
- Anyone who spends well over S$500 a month locally and wants to try it free for the first year.
Skip it if:
- Your eligible local spending is often below S$500 a month.
- You want one simple card with no annual fee. The Mari card or the Trust Freedom card is easier to live with.
- You want rewards on overseas shopping and hotels, not just Grab.
For how GXS compares as a bank overall, see our MariBank vs GXS comparison. To compare against bank cards too, read our best credit cards in Singapore for 2026.
How to apply and claim the GXS referral
- Download the GXS app and open a GXS Savings Account with Singpass. You can also apply for the card through the Grab app.
- Enter TKN’s referral code YONG477 when you open the savings account. GXS’s current referral promotion gives S$8 to you and S$8 to the referrer when a new customer opens a GXS Savings Account and makes a first deposit of S$500, until 31 December 2026 (GXS promotions). See our GXS referral code page for details.
- Apply for the GXS Credit Card in the app. You need an income of at least S$30,000 a year.
- Set up GIRO or a reminder to pay the full statement balance each month, and track your eligible spend so you know when you have passed S$500.
For more on the bank itself, including savings rates and Boost Pockets, read our GXS Bank complete guide.
Not financial advice. Card terms, tiers and fees can change. Check the GXS app and GXS’s website for the latest terms before you apply.
Frequently Asked Questions
What is the GXS Credit Card cashback rate?
It pays 1.75% uncapped cashback on eligible local spending once you spend at least S$500 a month, 1.75% on Singtel bills with no minimum, 3% to 10% in GrabCoins on Grab in Singapore, and 10% in GrabCoins on Grab overseas.
Does the GXS Credit Card have an annual fee?
Yes, S$196.20 a year including GST. The first year is waived for customers approved by 31 December 2026.
What is the minimum income for the GXS Credit Card?
S$30,000 a year for Singaporeans and PRs, and S$120,000 a year for eligible foreigners with a valid pass.
What happens if I spend less than S$500 a month on the GXS Credit Card?
You earn no 1.75% local cashback that month. Singtel bills still earn 1.75% and Grab still earns the base 3% in GrabCoins, but the 5% and 10% Grab tiers also need the S$500 non-Grab spend.
Is the GXS Credit Card good for overseas spending?
Only on Grab. Overseas Grab earns 10% in GrabCoins with no FX fee, but other foreign-currency spending has no FX fee and earns no cashback.
What is the difference between the GXS Credit Card and the GXS FlexiCard?
The FlexiCard has no minimum income, a fixed S$500 limit and random instant cashback of up to S$3 per transaction of S$10 or more. The GXS Credit Card needs S$30,000 income and pays 1.75% uncapped cashback and Grab rewards.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.