SRS Account Interest Rate 2026: What You’re Earning (And How to Beat It)
A complete guide to SRS cash interest, approved investments and maximising your Supplementary Retirement Scheme returns in 2026.
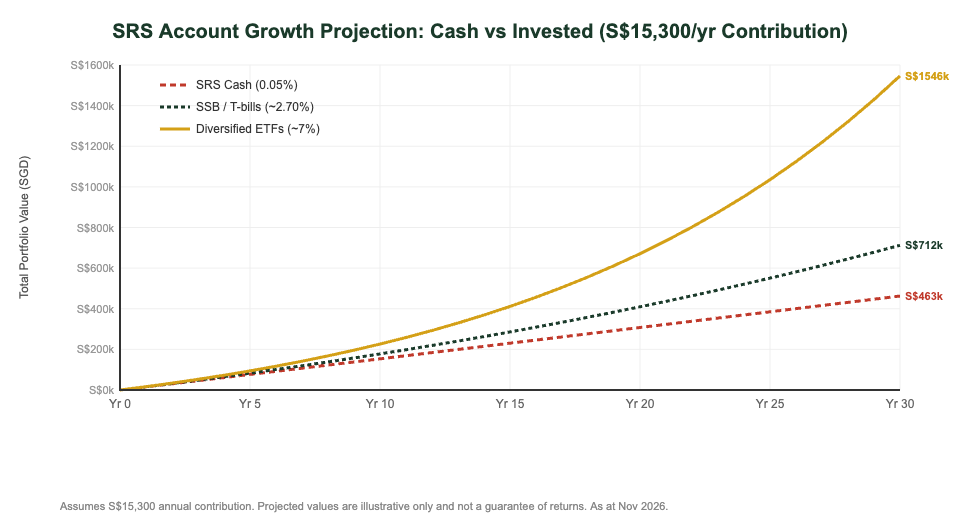
The SRS account earns 0.05% per year in cash — just S$7.65 on a full S$15,300 contribution. The real SRS advantage is not the interest rate, but the tax savings at contribution and the ability to invest in SSBs, T-bills, ETFs and Singapore REITs inside the account, where returns of 2–8% annually are achievable with no dividend or capital gains tax.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Table of Contents
Contents — Click to expand
What Is the SRS Account Interest Rate?
The SRS account interest rate in Singapore is 0.05% per year — a flat rate applied by all three SRS operators: DBS, UOB, and OCBC. This is credited on cash balances left uninvested inside the SRS account.
To put it in concrete terms: if you contributed the full S$15,300 allowance for Singaporeans and PRs in 2026 and left it as cash, you would earn just S$7.65 in interest for the entire year. At that rate, your SRS balance would take over 1,386 years to double via interest alone.
Why Is the SRS Interest Rate So Low?
The SRS is a tax-deferral retirement scheme, not a savings account. The 0.05% cash rate is intentionally low to incentivise account holders to invest their SRS funds rather than park them in cash. The government’s goal is for SRS monies to be deployed into productive investments — equities, bonds, insurance products, REITs — that generate real long-term returns.
In contrast, the CPF Ordinary Account earns a floor rate of 2.5%, and the CPF Special Account earns 4.0%. These are government-guaranteed rates because CPF is a mandatory scheme. SRS is voluntary, and the government allows market returns (and risks) to determine outcomes. According to the Ministry of Finance’s SRS overview, the scheme was specifically designed to complement CPF and encourage members to build a diversified retirement portfolio.
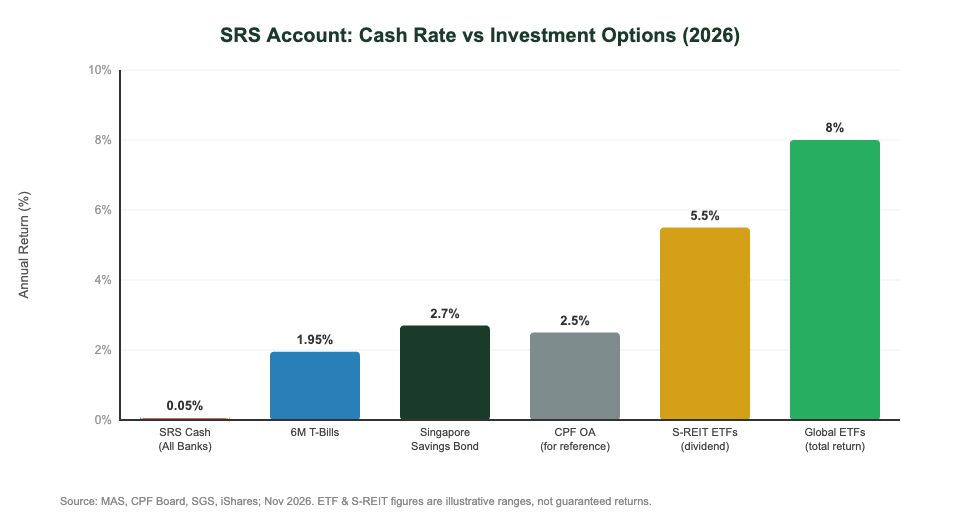
SRS Cash vs Other Savings Options (2026 Rates)
To understand just how low the SRS cash rate is, here’s how it stacks up against other common Singapore savings and investment vehicles in 2026:
| Instrument | 2026 Rate / Expected Return | SRS Eligible? | Risk Level |
|---|---|---|---|
| SRS Cash (DBS/UOB/OCBC) | 0.05% p.a. | N/A (default) | None |
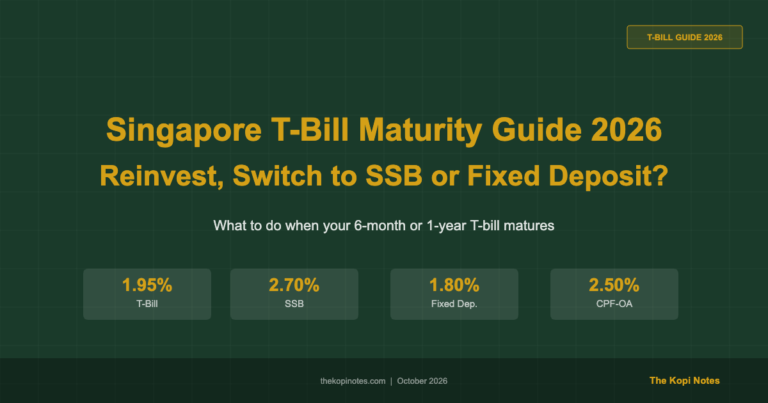
| Singapore Savings Bonds (SSB) | ~2.70% avg 10yr | Yes | Very Low |
| 6-Month T-Bills | ~1.95% p.a. | Yes | Very Low |
| CPF Ordinary Account | 2.5% p.a. | No | None (guaranteed) |
| S-REIT ETFs (e.g. Lion-Phillip) | 5–6% dividend yield | Yes | Moderate |
| Global ETFs (e.g. CSPX, VWRA) | 6–10% long-term avg | Yes (via CDP broker) | Moderate–High |
Source: MAS, SGS, CPF Board; data as at November 2026. Expected returns for equities are historical and not guaranteed.
Even the lowest-risk SRS investment — Singapore Savings Bonds — earns over 50 times more than cash. For investors comfortable with moderate risk, a diversified ETF portfolio inside SRS has historically returned 6–10% annually over the long term. See our Singapore T-bills 2026 guide for step-by-step SRS T-bill subscription instructions.
Approved SRS Investment Options and Expected Returns
The SRS scheme allows a wide range of investments. Here is the complete list of approved SRS investment categories with expected returns and suitability notes:
| Investment Category | Examples | Expected Return | Best For |
|---|---|---|---|
| Singapore Government Securities | T-bills, SGBs, SSBs | 1.9–2.7% p.a. | Capital preservation |
| Listed Shares (SGX) | S-REITs, DBS, Singtel | 4–8% div yield + capital | Income investors |
| ETFs | CSPX, VWRA, Lion-Phillip S-REIT ETF | 5–10% long-term | Growth / diversification |
| Unit Trusts / Robo Advisors | Endowus, Syfe, FSMOne | 4–8% (varies by fund) | Hands-off investors |
| Insurance Products | Endowment plans, annuities | 2.5–3.56% IRR | Conservative, capital-protected |
Source: CPF Board SRS Investment Scheme guidelines; expected returns are illustrative ranges, not guaranteed. As at November 2026.
Using Robo-Advisors for SRS Investing
Several Singapore robo-advisors accept SRS funds, making it easy to invest in diversified portfolios without picking individual stocks. Platforms like Endowus (use referral code 2V343) and Syfe (use referral code SRPRFFFCD) both support SRS contributions, automatically rebalance your portfolio, and offer institutional-grade fund access. FSMOne (referral code P0544985) is another option for cost-conscious investors who prefer to self-select unit trusts.
DBS vs UOB vs OCBC SRS: Does the Bank Matter?
All three SRS operators pay the same 0.05% cash interest rate. The choice of bank affects which investments you can easily access, brokerage fees, and the investment platform interface.
| Bank | SRS Interest Rate | Linked Brokerage | Robo Advisor Support |
|---|---|---|---|
| DBS Bank | 0.05% p.a. | DBS Vickers | Endowus, Syfe |
| UOB | 0.05% p.a. | UOB Kay Hian | Endowus, FSMOne |
| OCBC | 0.05% p.a. | OCBC Securities | Endowus, Syfe |
Source: DBS, UOB, OCBC official SRS pages; as at November 2026.
For most investors, the best SRS bank is whichever you already use for daily banking. If you plan to invest heavily through Endowus, any of the three banks works. See our guide to Singapore Savings Bonds for how to subscribe to SSBs from your SRS account.
The Real SRS Advantage: Tax Savings, Not the Interest Rate
Many people focus on the SRS interest rate when the real benefit is the upfront tax relief. Every dollar contributed to SRS reduces your chargeable income, delivering immediate and certain tax savings.
| Chargeable Income (Before SRS) | Marginal Tax Rate | Tax Saved (S$15,300 contribution) | 1st-Year Return |
|---|---|---|---|
| S$80,001–S$120,000 | 11.5% | ~S$1,760 | 11.5% |
| S$120,001–S$160,000 | 15% | ~S$2,295 | 15% |
| S$160,001–S$200,000 | 18% | ~S$2,754 | 18% |
| S$200,001–S$240,000 | 19% | ~S$2,907 | 19% |
Source: IRAS income tax rates YA2026. Tax savings are estimates based on marginal rate × S$15,300. Actual savings depend on personal relief and deductions.
The SRS tax deferral also applies to investment returns within the account — dividends and capital gains accumulate tax-free until withdrawal. At withdrawal from age 63, only 50% of the withdrawn amount is taxable as income, further reducing the effective rate. For more on maximising your retirement income, see our Singapore retirement calculator.
What Should You Do With Your SRS Account?
Given the 0.05% cash rate, here is a practical framework based on your investment horizon and risk tolerance:
Short-term (2–3 years before withdrawal)
Move SRS cash into Singapore Savings Bonds or T-bills. Both are capital-guaranteed by the Singapore government and eligible for SRS, earning 1.9–2.7% — over 50x the cash rate. See our guide to Singapore Savings Bonds for the SSB ladder strategy.
Medium-term (5–10 years)
Consider a mix of SSBs for the conservative portion and S-REIT ETFs or diversified equity ETFs for the growth portion. Singapore REITs have historically yielded 5–6% and provide inflation-linked income. See our Singapore REIT ETF guide for SRS-eligible options.
Long-term (10+ years)
For investors with a long horizon, global equity ETFs have historically returned 7–10% annually over 10+ year periods. Using the Syfe referral code SRPRFFFCD or Endowus referral code 2V343 gives you access to low-cost managed portfolios that work with SRS funds.
Practical Tip: Don’t Leave SRS as Cash
If you have contributed to SRS this year and have not invested yet, the simplest first step is to subscribe to the next Singapore Savings Bond tranche. Applications open monthly through your bank’s internet banking portal and take only a few minutes. This alone will increase your SRS returns by over 50x compared to leaving funds as cash. For a holistic view of your retirement income plan, use our Singapore retirement calculator.
Frequently Asked Questions
What is the current SRS account interest rate in Singapore?
Is the SRS interest rate the same at DBS, UOB and OCBC?
What can I invest in through my SRS account to get better returns?
How does SRS compare to CPF in terms of interest rate?
When can I withdraw my SRS funds and how is it taxed?
Can I top up my SRS account after the annual contribution limit?
Disclaimer: This article is for informational and educational purposes only. It does not constitute financial advice. SRS interest rates, tax rules, and investment options are subject to change. Please consult a licensed financial adviser before making retirement planning decisions. All referral links on this page may earn The Kopi Notes a referral fee at no cost to you.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.