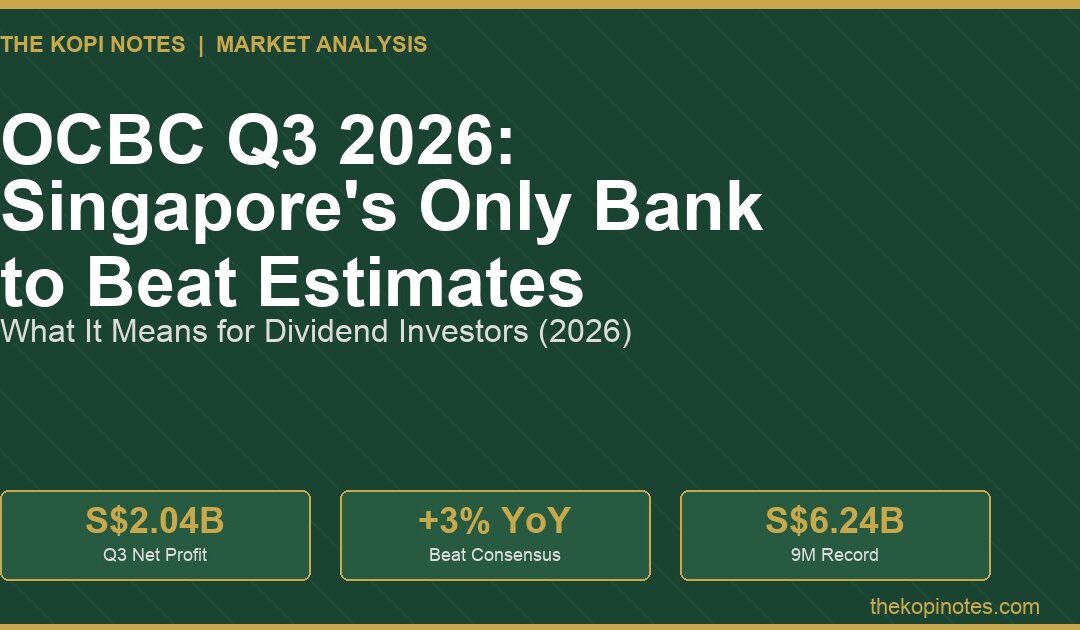
OCBC reported Q3 2026 net profit of S$2.04 billion — up 3% year-on-year and the only Singapore bank to beat analyst estimates this quarter. While DBS and UOB both missed forecasts as NIM pressure continued, OCBC’s record Banking Operations profit, surging wealth fees, and upgraded FY2026 guidance signal a structurally stronger earnings base heading into the final stretch of 2026.
This is an editorial analysis. Not financial advice. Data verified as at 7 November 2026.
The Headline Numbers: OCBC’s Record Q3 2026 Performance
OCBC Group delivered a third-quarter 2026 net profit of S$2.04 billion, marginally above the S$2.00 billion Bloomberg consensus estimate — making it the standout performer in Singapore’s big-three bank earnings season. For the first nine months of 2026, group net profit rose 10% year-on-year to a record S$6.24 billion.
The key driver was Banking Operations, which hit a record quarterly profit of S$1.90 billion in Q3 2026 — up 16% year-on-year and 8% quarter-on-quarter. This was powered by loan growth, record customer flow trading income, and resilient fee income across wealth and wholesale banking.
The only drag? Great Eastern Holdings (GEH), OCBC’s insurance arm, saw lower investment performance due to mark-to-market losses on bond portfolios as interest rates rose in Q3. This pulled group net profit 8% below the record Q2 2026 level of S$2.22 billion. Strip GEH out, however, and OCBC’s Banking Operations are firing on all cylinders.
Net interest income (NII) for Q3 2026 was S$2.31 billion — the highest in six quarters, up 4% year-on-year — supported by 15% average asset growth as OCBC expanded both customer loans and high-quality non-commercial assets. Customer loans reached S$372 billion, up 14% year-on-year in constant-currency terms.
The Singapore Bank Report Card: Why Only OCBC Passed
This quarter’s earnings season told a stark story of divergence among Singapore’s three big banks. DBS and UOB had already reported before OCBC’s November 6 announcement, and both fell short of expectations.
DBS Group posted Q3 2026 net profit of S$2.95 billion, down 2% year-on-year and missing analyst targets as NIM headwinds weighed on net interest income. UOB fared worse, with Q3 2026 profit of S$1.25 billion — down 15% quarter-on-quarter and missing the S$1.38 billion consensus by a wide margin. UOB’s NIM compressed further to 1.68%, raising questions about whether its full-year guidance of 1.75%-1.80% remains achievable.
OCBC, by contrast, saw its NIM compression slow down materially. Its NIM narrowed by just 4 basis points quarter-on-quarter in Q3 2026 to 1.66%, compared to 6 basis points in Q2 and 10 basis points in Q1. That moderating trajectory — combined with strong volume growth and diversified non-interest income — was what allowed OCBC to clear the bar its peers could not.
Singapore Banks Q3 2026 Comparison
| Bank | Q3 2026 Net Profit | YoY Change | vs. Consensus | 9M 2026 Net Profit | Q3 NIM |
|---|---|---|---|---|---|
| OCBC | S$2.04B | +3% | Beat | S$6.24B (record) | 1.66% |
| DBS | S$2.95B | -2% | Miss | – | ~1.70% |
| UOB | S$1.25B | +183%* | Miss | S$4.17B | 1.68% |
*UOB YoY flattered by weak Q3 2025 base. Sources: OCBC official press release (6 Nov 2026); Growbeansprout.com; TKN DBS Q3 2026 article.
OCBC’s Wealth Management Engine: The Real Competitive Edge
If there is one trend that separates OCBC from the pack in 2026, it is wealth management. For the nine months to September 2026, OCBC’s wealth management fees surged 25% year-on-year to a record S$1.33 billion, driven by broad-based growth across private banking, premier banking, insurance, asset management, and stockbroking.
Banking WM assets under management (AUM) reached a new high of S$358 billion in Q3 2026, up 2% quarter-on-quarter. Banking WM income, excluding GEH, rose 2% to a record S$1.12 billion in Q3 2026.
This matters enormously because it means OCBC is less reliant on interest rate tailwinds than DBS or UOB. OCBC’s non-interest income reached a record S$4.93 billion for 9M2026 — up 19% year-on-year — now accounting for 42% of total income, up from 38% in 9M2025.
Customer flow trading income was another standout, hitting a record S$480 million in Q3 2026. For 9M2026, it rose 40% year-on-year to a record S$1.35 billion.
Upgraded FY2026 Guidance: Reading Between the Lines
Perhaps the most telling signal from OCBC’s Q3 results was the guidance upgrade. With three quarters of a record year in the books, OCBC upgraded its FY2026 financial guidance across three key metrics: loan growth, total income, and credit costs.
Asset quality remains solid. The NPL ratio improved to 0.8% in Q3 2026, and total NPA coverage stood at a robust 168%. Credit costs came in at just 6 basis points annualised in Q3 2026 — well below the 14 basis points in Q2 2026. The guidance upgrade on credit costs further supports the earnings outlook.
Meanwhile, Singapore’s strong macro backdrop supports these projections. Singapore’s Q3 2026 GDP grew 5.4%, supporting continued business loan demand across the region.
What OCBC’s Beat Means for Dividend Investors
OCBC does not declare dividends at Q3 results — that comes at the full-year results in February 2027. But the trajectory is what dividend investors should focus on now.
With nine-month profit already at a record S$6.24 billion, OCBC is well-positioned to deliver another record full-year result. If Q4 2026 tracks at around S$2.0-2.1 billion (conservatively), FY2026 net profit could land between S$8.2-8.4 billion — meaningfully above FY2025.
OCBC has consistently maintained a dividend payout ratio of around 50%. A higher full-year profit therefore implies the potential for a higher FY2026 dividend versus FY2025’s payout. For long-term dividend investors who bought OCBC at lower prices, this remains a compelling compounding story — particularly given shares at an all-time high of S$18.08.
For investors using their SRS account for investments, OCBC shares remain one of the most accessible ways to gain blue-chip banking exposure with dividend income.
As a comparison for income alternatives: Singapore T-bills continue to offer risk-free yields around 3.0%-3.2%. OCBC’s forward dividend yield at S$18.08 — based on estimated FY2026 payout — may be broadly comparable or slightly lower. The case for OCBC is capital appreciation potential alongside dividends, not just the yield itself.
Risks Investors Should Monitor
GEH Insurance Volatility: Great Eastern Holdings remains a double-edged sword. Its underlying insurance business is growing well — NBEV up 14% YoY and NBEV margin expanding to 57.5% — but mark-to-market swings in its bond and equity portfolios can create quarter-to-quarter noise.
NIM Plateau Risk: While OCBC’s NIM compression is moderating, it has not stopped. At 1.66% in Q3 2026, NIM is still below the year-ago level of 1.84%.
Geopolitical and Regional Exposure: OCBC has significant exposure to Greater China and Southeast Asia. Any escalation in US-China trade tensions or a sharper-than-expected slowdown in China’s property sector recovery could translate into higher loan losses.
Valuation at All-Time Highs: With OCBC shares at S$18.08 and hitting a fresh all-time high post-results, valuation is stretched. Investors considering S-REITs as an alternative income play should note that some REITs now offer dividend yields of 6%-9.3%.
Bottom Line for SG Investors
OCBC’s Q3 2026 results are a genuine positive. It is the only Singapore bank to beat consensus this quarter, and its upgraded FY2026 guidance is backed by fundamentals — record loan book, moderating NIM compression, surging wealth management fees, and improving credit quality. The record 9-month profit of S$6.24 billion puts FY2026 on track to be OCBC’s best year on record.
TKN’s view: OCBC remains a core holding for Singapore investors seeking a combination of dividend income and regional banking exposure. But investors buying new positions at all-time highs should size positions appropriately and not chase momentum. Consider scaling in gradually, and pair with diversified market exposure across ETFs and REITs.
Frequently Asked Questions
What was OCBC’s Q3 2026 net profit?
OCBC reported Q3 2026 net profit of S$2.04 billion, up 3% year-on-year. For the first nine months of 2026, group net profit was a record S$6.24 billion, up 10% year-on-year.
Did OCBC beat analyst expectations in Q3 2026?
Yes. OCBC was the only Singapore bank to beat consensus estimates in Q3 2026. Its Q3 net profit of S$2.04 billion was slightly above the S$2.00 billion Bloomberg consensus. DBS and UOB both missed forecasts.
What is OCBC’s NIM (net interest margin) in Q3 2026?
OCBC’s NIM was 1.66% in Q3 2026, down 18 basis points year-on-year from 1.84% and down 4 basis points quarter-on-quarter. Crucially, the pace of NIM compression is moderating — it narrowed by 10bps in Q1, 6bps in Q2, and just 4bps in Q3 2026.
Did OCBC upgrade its FY2026 guidance?
Yes. OCBC upgraded its FY2026 financial guidance across three metrics: loan growth (upgraded), total income (upgraded), and credit costs (upgraded to reflect lower expected losses).
What does OCBC’s Q3 2026 beat mean for its dividend?
OCBC does not announce dividends at Q3 results — the final dividend will be declared at the FY2026 results in early 2027. However, with 9M26 profit at a record S$6.24 billion, FY2026 net profit could land at S$8.2-8.4 billion, potentially supporting a higher FY2026 dividend. OCBC has historically maintained a ~50% payout ratio.
How does OCBC compare to DBS and UOB in Q3 2026?
OCBC was the standout performer. DBS posted Q3 2026 net profit of S$2.95 billion (-2% YoY, miss), while UOB reported S$1.25 billion (-15% QoQ, miss). OCBC’s Banking Operations profit hit a record S$1.90 billion.
Should I buy OCBC shares after Q3 2026 results?
OCBC shares hit an all-time high of S$18.08 after Q3 results. While the fundamentals are strong, buying at all-time highs carries valuation risk. This is not financial advice.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.