CapitaLand Ascendas REIT Review 2026: Share Price, DPU & Is A17U Worth Buying?
Singapore’s largest industrial and business space REIT — a complete 2026 breakdown of share price, DPU history, gearing and investment verdict.
CapitaLand Ascendas REIT (SGX: A17U) is Singapore’s largest industrial and business space REIT, managing a S$17+ billion portfolio of 219+ properties across Singapore, Australia, the United Kingdom and the United States. Trading at around S$2.80 in 2026, A17U offers an estimated distribution yield of approximately 5.4%, backed by a blue-chip tenant roster that includes Amazon, DHL and Singtel. For Singapore investors seeking passive income Singapore from an investment-grade industrial REIT, CLAR remains one of the most liquid and well-diversified options on the SGX.
Not financial advice. All figures are for educational reference only and sourced from SGX filings and CLAR investor relations. Data as at November 2026 unless noted.
What Is CapitaLand Ascendas REIT?
CapitaLand Ascendas REIT (ticker: A17U, commonly abbreviated CLAR) was listed on the SGX Mainboard in November 2002. Originally named Ascendas REIT, it was rebranded in 2021 following its integration with the CapitaLand group. CLAR is managed by Ascendas Funds Management (S) Ltd, a wholly-owned subsidiary of CapitaLand Investment Limited.
CLAR’s portfolio spans four asset classes: business parks, logistics and distribution centres, hi-tech industrial buildings, and suburban offices. As of mid-2026, the portfolio comprises over 219 properties valued in excess of S$17 billion. The REIT’s geographic diversification — with assets in Singapore, Australia, the UK and the US — sets it apart from most pure-play Singapore industrial REITs.
As Singapore’s first and largest business space and industrial REIT, CLAR is a core holding in many institutional and retail portfolios. It consistently ranks among the best S-REITs in Singapore 2026 by market capitalisation and trading liquidity.
| Key Facts | Details |
|---|---|
| SGX Ticker | A17U |
| REIT Type | Industrial / Business Space |
| Manager | Ascendas Funds Management (S) Ltd |
| Sponsor | CapitaLand Investment Limited |
| Listed | November 2002 |
| Portfolio Size | 219+ properties, S$17B+ AUM |
| Credit Rating | A3 (Moody’s) / A- (S&P) |
Source: CapitaLand Ascendas REIT investor relations, 2026.
A17U Share Price 2026
As at November 2026, CapitaLand Ascendas REIT (A17U) is trading at approximately S$2.80 per unit. The share price has been under pressure since the interest-rate hiking cycle of 2022–2023, which weighed on yield-sensitive assets globally. However, as the US Federal Reserve signalled and initiated rate cuts from late 2024, CLAR’s unit price has partially recovered from its trough.
At S$2.80, A17U trades at a premium to its book NAV of approximately S$2.17 per unit — implying a price-to-NAV (P/NAV) of about 1.29x. This premium reflects the market’s confidence in the quality of CLAR’s portfolio and its strong sponsor backing. For context, the S-REIT sector average P/NAV in mid-2026 is approximately 0.90x, making CLAR one of the few S-REITs still commanding a premium valuation.
| Metric | Value (Nov 2026) |
|---|---|
| Share Price | ~S$2.80 |
| 52-Week Low / High | ~S$2.46 / ~S$3.05 |
| NAV Per Unit | ~S$2.17 |
| P/NAV | ~1.29x |
| Market Cap | ~S$10.4B |
| Distribution Yield | ~5.4% |
Source: SGX, CapitaLand Ascendas REIT, November 2026. All figures are estimates for educational reference only.
DPU History & Forecast
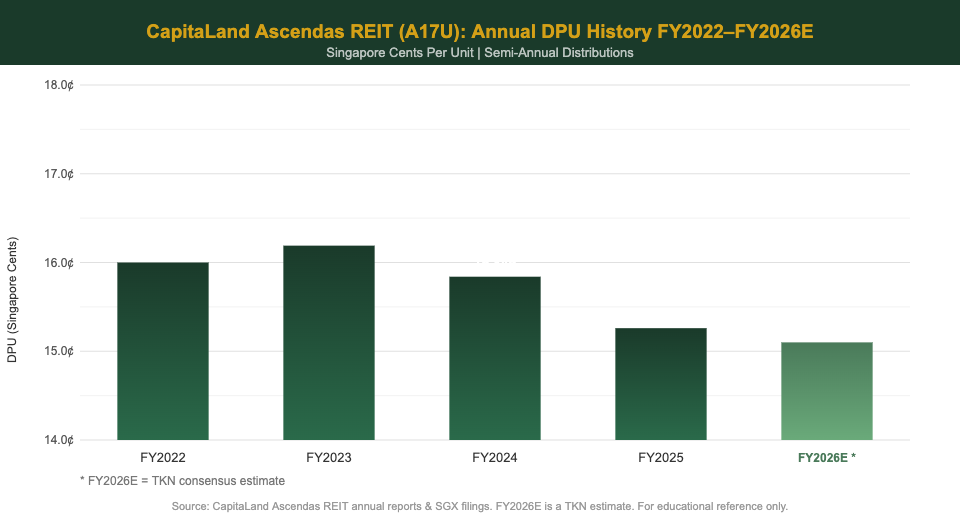
CapitaLand Ascendas REIT distributes income semi-annually. The distribution per unit (DPU) peaked in FY2023 before moderating slightly due to higher financing costs and foreign exchange headwinds from its overseas portfolio. Here is the five-year DPU track record:
| Financial Year | DPU (Singapore cents) | YoY Change |
|---|---|---|
| FY2022 | 16.00¢ | — |
| FY2023 | 16.19¢ | +1.2% |
| FY2024 | 15.84¢ | -2.2% |
| FY2025 | 15.26¢ | -3.7% |
| FY2026E | ~15.10¢ | ~-1.0% (est.) |
Source: CapitaLand Ascendas REIT annual reports, SGX filings. FY2026E is an estimate.
The modest DPU decline over FY2024–2026 reflects two primary headwinds: rising interest expense as older fixed-rate debt was refinanced at higher rates, and Australian dollar and sterling weakness relative to the Singapore dollar. On a positive note, occupancy rates across the Singapore portfolio remain strong at above 93%, and the REIT has been actively recycling capital — divesting older assets and reinvesting in higher-specification logistics and data centre assets.
Using the FY2026E DPU of approximately 15.10 cents and the current price of S$2.80, the forward yield works out to roughly 5.4%. This compares favourably to Singapore fixed deposits at ~1.8% and CPF-OA at 2.5%, though investors seeking higher yields may wish to compare CLAR against peers like Mapletree Industrial Trust FY2027 review.
Portfolio Overview
CLAR’s portfolio is diversified across four geographies and four property types. Singapore remains the core market, contributing approximately 60% of total portfolio value, while Australia, the UK and the US collectively account for the remaining 40%.
| Geography | % of Portfolio | No. of Properties | Key Asset Types |
|---|---|---|---|
| Singapore | ~60% | ~132 | Business parks, logistics, hi-tech |
| Australia | ~16% | ~28 | Business parks, logistics |
| United Kingdom | ~14% | ~48 | Urban logistics, light industrial |
| United States | ~10% | ~11 | Business parks |
Source: CapitaLand Ascendas REIT investor presentations, mid-2026.
CLAR’s Singapore portfolio includes landmark developments such as one-north (a science and business park cluster), Changi Business Park, and multiple logistics hubs in Jurong and Tuas. Its top 10 tenants include names like Singtel, DHL Supply Chain, DB Schenker and Rolls-Royce Holdings, providing significant income stability. The weighted average lease expiry (WALE) for the Singapore portfolio is approximately 3.8 years.
The UK portfolio, acquired progressively between 2021 and 2024, focuses on last-mile urban logistics properties near major UK cities — a segment benefiting from structural tailwinds in e-commerce. The US portfolio is concentrated in business parks in Raleigh-Durham and Portland, two established tech and life sciences clusters.
Financial Health & Gearing
One of the most important metrics for any REIT investor to monitor is the debt gearing ratio — the proportion of total assets funded by borrowings. MAS regulations cap S-REIT gearing at 50% (or up to 55% if the REIT’s interest coverage ratio, or ICR, exceeds 2.5x). CLAR’s current metrics are well within these limits.
| Metric | Value (2026) | MAS Limit | Assessment |
|---|---|---|---|
| Aggregate Leverage | ~38.4% | 50% / 55% | ✅ Comfortable |
| Interest Coverage Ratio (ICR) | ~3.8x | >2.5x for 55% cap | ✅ Strong |
| % Fixed Rate Debt | ~78% | No requirement | ✅ Well-hedged |
| Average Debt Maturity | ~3.5 years | No requirement | ℹ️ Moderate |
Source: CapitaLand Ascendas REIT interim results, mid-2026.
With gearing at approximately 38.4%, CLAR has significant headroom before hitting the MAS limit. This translates to approximately S$2.0–2.5 billion in debt capacity, providing firepower for further acquisitions from its sponsor pipeline — including potential data centre and cold-chain logistics assets — without the need for immediate equity fundraising. The REIT’s strong ICR of approximately 3.8x also reflects healthy net property income relative to its financing costs, even after the interest rate normalisation cycle. If you’re using the Singapore retirement calculator, CLAR’s yield and gearing profile makes it a suitable core REIT holding for income-focused portfolios.
Peer Comparison: CLAR vs Singapore Industrial REITs
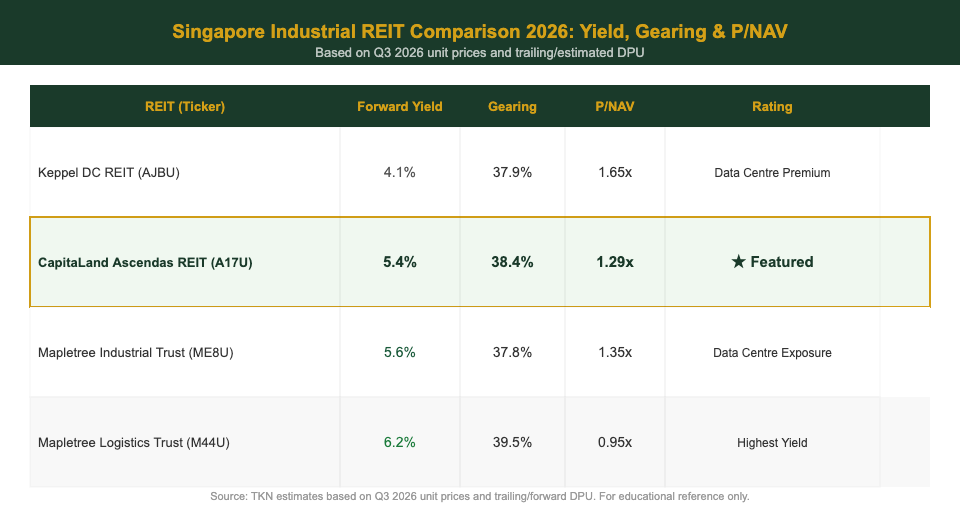
How does CLAR compare against its closest S-REIT peers? The table below benchmarks A17U against Keppel DC REIT (AJBU), Mapletree Industrial Trust (ME8U) and Mapletree Logistics Trust (M44U) on the key metrics Singapore investors care about.
| REIT | Ticker | Yield (est.) | Gearing | P/NAV |
|---|---|---|---|---|
| Keppel DC REIT | AJBU | ~4.1% | ~34% | ~1.6x |
| CapitaLand Ascendas REIT | A17U | ~5.4% | ~38% | ~1.29x |
| Mapletree Industrial Trust | ME8U | ~5.6% | ~40% | ~1.05x |
| Mapletree Logistics Trust | M44U | ~6.2% | ~43% | ~0.90x |
Source: SGX, respective REIT investor presentations, November 2026. All figures are estimates for educational reference only.
CLAR offers a middle-ground yield of approximately 5.4% — higher than Keppel DC REIT’s data-centre premium pricing but lower than MLT’s currently discounted valuation. Its P/NAV of 1.29x signals that the market still assigns a quality premium to CLAR’s size, sponsor strength and diversification. For income-first investors who want a slightly higher yield than KDC REIT with better liquidity than smaller industrial REITs, CLAR is a natural choice.
Investment Verdict 2026: Is A17U Worth Buying?
CapitaLand Ascendas REIT is a high-quality industrial REIT that suits investors seeking stable, recurring income from a diversified, investment-grade portfolio. Here is our balanced assessment of the pros and cons.
| 👍 Strengths | ⚠️ Risks |
|---|---|
| Largest industrial REIT in SG — deep liquidity and institutional ownership | Trades at P/NAV premium (1.29x) — limited near-term capital upside |
| Investment-grade credit (A3/A-) with well-staggered debt maturities | DPU headwinds from USD/GBP/AUD weakness and higher refinancing costs |
| Strong sponsor (CapitaLand Investment) with deep ROFR pipeline | US business parks facing structural vacancy pressures post-pandemic |
| ~5.4% yield with semi-annual distributions, CPF-investable | Rate-sensitive: further Fed rate hikes would pressure unit price |
Our take: CLAR is a core holding rather than a high-yield play. At S$2.80, the 5.4% yield is attractive relative to bonds and fixed deposits, though not exceptional within the S-REIT space. The premium P/NAV limits downside protection in a valuation-driven selloff. Investors comfortable with the current premium and looking for a stable, blue-chip industrial REIT to anchor their income portfolio will find CLAR a solid, if unexciting, choice for 2026. Dollar-cost averaging into CLAR during price dips toward S$2.50–2.60 would improve the entry yield meaningfully.
Not financial advice. Please conduct your own due diligence before investing.
How to Buy CLAR (A17U) in Singapore
CapitaLand Ascendas REIT is listed on the SGX Mainboard and can be purchased through any SGX-authorised brokerage. It is also eligible for CPF Investment Scheme (CPFIS-OA and CPFIS-SA) and SRS investment.
For Singapore retail investors, three popular platforms for buying S-REITs are:
- Syfe — commission-free REIT+ portfolios that hold CLAR as a core position. Use our Syfe referral code and sign-up bonus for a fee waiver on your first few months.
- FSMOne — a one-stop platform for SGX stocks, unit trusts and ETFs. Use our FSMOne referral code P0544985 to earn bonus rebates.
- Endowus — for CPF and SRS investors, Endowus allows you to invest in REIT-focused funds with your CPF-OA. Use our Endowus referral code 2V343 for S$20 access fee credit.
The minimum purchase is 1 lot (100 units), which at S$2.80 per unit amounts to S$280 plus brokerage commissions. Distributions are paid semi-annually — typically in June and December for the financial year ending March.
Frequently Asked Questions
Is CapitaLand Ascendas REIT a good investment in 2026?
What is CLAR's distribution yield in 2026?
How often does CapitaLand Ascendas REIT pay distributions?
Can I buy CLAR using CPF?
What is CLAR's gearing ratio?
What type of properties does CLAR own?
Who is the sponsor of CapitaLand Ascendas REIT?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.