Mapletree Industrial Trust (ME8U) FY2027: DPU Forecast, Dividend Yield & Investment Verdict
Singapore's largest industrial S-REIT — hi-tech buildings, US data centres & ~6.1% yield.
Mapletree Industrial Trust (SGX: ME8U) is Singapore’s largest industrial S-REIT by assets under management, holding approximately S$9.8 billion across over 140 properties in Singapore, the United States, and Japan. Its diversified portfolio spans hi-tech buildings, business parks, flatted factories, and US data centres. With a projected FY2026/27 DPU of approximately 13.60 cents and a dividend yield near 6.1% at November 2026 prices, MIT remains a strong core holding for income-seeking Singapore investors.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Table of Contents
What Is Mapletree Industrial Trust?
Mapletree Industrial Trust (MIT) is a Singapore-listed real estate investment trust managed by Mapletree Industrial Trust Management Ltd, a wholly-owned subsidiary of its sponsor, Mapletree Investments Pte Ltd — one of Singapore’s largest real estate groups. Listed on the SGX in October 2010 under the ticker ME8U, MIT has grown from a portfolio of flatted factories into one of Asia’s most diversified industrial REITs.
As at November 2026, MIT holds approximately 141 properties across Singapore, the United States, and Japan. Singapore remains the core market (~75% of AUM), but the US data centre portfolio has grown to represent around 21% of revenue — providing structural growth tailwinds and USD-denominated income diversification. MIT distributes income quarterly, with distributions based on 100% of distributable income. The trust’s financial year runs from 1 April to 31 March. For investors building a passive income Singapore portfolio, MIT’s quarterly dividends and diversified industrial exposure make it a cornerstone S-REIT holding.
Key Facts at a Glance (ME8U)
| Metric | Detail |
|---|---|
| Full Name | Mapletree Industrial Trust |
| SGX Ticker | ME8U (SGD) / M44U (USD) |
| Sponsor | Mapletree Investments Pte Ltd |
| Listed On | SGX Main Board, October 2010 |
| AUM (Sep 2026) | ~S$9.8 billion |
| Properties | ~141 (Singapore, US, Japan) |
| Gearing (Sep 2026) | ~37.5% |
| DPU FY2025/26 | ~13.40 cents |
| Distribution Frequency | Quarterly |
| Financial Year End | 31 March |
| NAV Per Unit (Sep 2026) | ~S$1.79 |
| Share Price (Nov 2026) | ~S$2.20 |
Source: MIT SGX filings, Q2 FY2026/27 quarterly results. Data as at November 2026.
MIT Portfolio Deep Dive
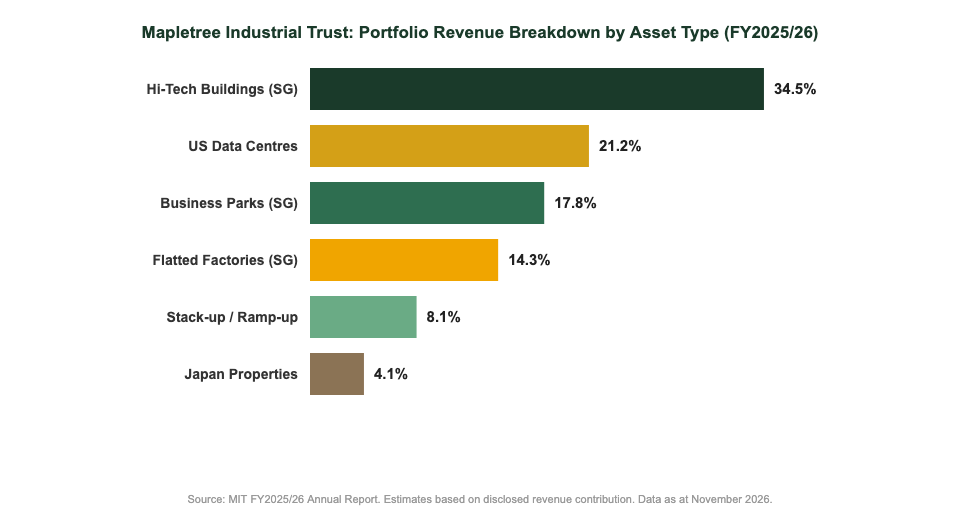
MIT’s portfolio is organised into five distinct asset segments, each with different risk-return profiles and demand drivers:
1. Hi-Tech Buildings (~34.5% of Revenue)
Hi-tech buildings are MIT’s largest revenue contributor. These are modern, air-conditioned industrial facilities with higher specifications than standard factories — including raised floors, precision air conditioning, and enhanced power supply. The flagship property is Mapletree Business City II (MBC II) in Alexandria, Singapore, a landmark 7-building complex housing technology companies, research facilities, and a data centre component. MBC II’s high occupancy and premium positioning underpin MIT’s Singapore income quality.
2. US Data Centres (~21.2% of Revenue)
MIT owns over 25 data centre properties across major US markets including Northern Virginia, Portland (Oregon), and Atlanta (Georgia). Acquired from 2019 onwards, the US data centres have been the key growth engine — benefiting from surging demand from hyperscalers, cloud providers, and AI infrastructure. For Singapore investors comparing best S-REITs in Singapore 2026, MIT’s data centre exposure gives it a structural growth angle versus purely domestic industrial REITs.
3. Business Parks, Singapore (~17.8% of Revenue)
MIT’s Singapore business parks span Toa Payoh, Tai Seng, and Chai Chee, targeting technology, media, and professional services tenants. MBC II provides the high-quality anchor. Lease structures are typically 3-year terms with rent reviews.
4. Flatted Factories (~14.3% of Revenue)
Flatted factories are MIT’s legacy portfolio — multi-storey industrial buildings leased to SMEs for light manufacturing. These generate stable, lower-growth income with 3-year leases providing regular rental reversion opportunities.
5. Stack-up/Ramp-up & Japan (~12.2% of Revenue)
Stack-up and ramp-up buildings serve logistics and light industrial users. MIT’s Japan portfolio (added in 2022) adds JPY-denominated income diversification across industrial properties in key logistics corridors.
DPU History & FY2027 Forecast
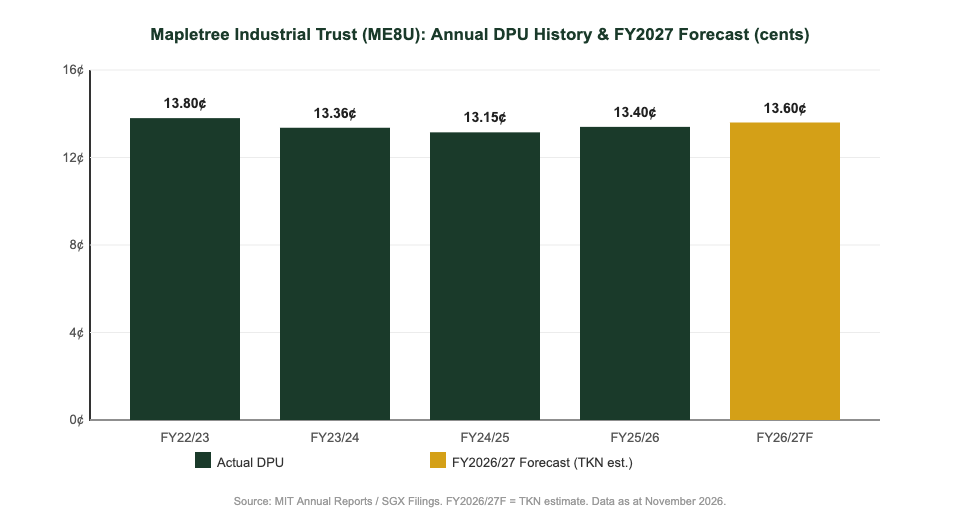
MIT has maintained a broadly stable distribution per unit (DPU) over the past five financial years, with modest compression in FY2023/24 and FY2024/25 reflecting higher floating-rate interest costs during the rate tightening cycle. A recovery began in FY2025/26 as management refinanced maturing debt at lower spreads and benefited from positive rental reversions in the Singapore portfolio.
For FY2026/27 (April 2026–March 2027), we forecast MIT’s full-year DPU at approximately 13.60 cents, a 1.5% increase on FY2025/26. This is supported by: (1) higher income from the US data centre portfolio on new lease commencements from AI/hyperscaler tenants, (2) positive rental reversion on Singapore leases renewing at market rates, and (3) lower effective borrowing costs as MIT refinances maturing debt in a declining-rate environment.
| Financial Year | DPU (cents) | Change YoY | Indicative Yield at S$2.20 |
|---|---|---|---|
| FY2022/23 | 13.80¢ | -2.3% | 6.27% |
| FY2023/24 | 13.36¢ | -3.2% | 6.07% |
| FY2024/25 | 13.15¢ | -1.6% | 5.98% |
| FY2025/26 | 13.40¢ | +1.9% | 6.09% |
| FY2026/27F (TKN est.) | 13.60¢ | +1.5% | 6.18% |
Source: MIT Annual Reports / SGX filings. FY2026/27F = TKN forecast estimate based on H1 results and management guidance. Yield calculated at assumed price of S$2.20. Data as at November 2026.
Dividend Yield & Valuation Analysis
At a November 2026 share price of approximately S$2.20 per unit and a projected FY2026/27 DPU of 13.60 cents, MIT offers a forward distribution yield of approximately 6.18%. This compares favourably to alternative income assets available to Singapore investors:
| Asset Class | Yield / Return | Key Consideration |
|---|---|---|
| MIT (ME8U) — Forward | ~6.18% | Quarterly income, share price growth potential |
| CPF Ordinary Account | 2.50% | Capital guaranteed, limited access before 55 |
| Singapore T-Bill (6-month) | ~1.95% | Risk-free, no capital appreciation |
| Singapore Savings Bond | ~2.70% | Flexible redemption, government guaranteed |
| Fixed Deposit (Best Rate) | ~1.80% | Low risk, fixed lock-in period |
Source: MAS, SGS, CPF Board, major bank rates as at November 2026. MIT yield = TKN estimate based on FY2027F DPU and current share price.
On a price-to-NAV basis, MIT trades at approximately 1.23x NAV (S$2.20 / ~S$1.79 NAV), a modest premium reflecting portfolio quality and stable DPU track record. For context, Singapore’s S-REIT market has historically traded at a P/NAV of 0.9–1.2x through the rate cycle. MIT’s premium is justified by its data centre growth exposure and Mapletree sponsor backing.
For Singapore investors, MIT can be compared alongside our Singapore REIT ETF guide for fund-based exposure, or added directly via brokerage. You can compare platforms via our Syfe referral code or FSMOne referral code for brokerage options.
Gearing & Financial Health
As at Q2 FY2026/27 (September 2026), MIT’s aggregate leverage ratio stands at approximately 37.5% — well below the MAS regulatory cap of 45%. This translates to approximately S$900 million of remaining debt headroom before the cap, providing meaningful capacity for acquisitions or asset enhancement initiatives (AEIs).
Key financial health metrics as at September 2026:
- Weighted average interest rate: approximately 3.8% per annum
- Interest coverage ratio (ICR): approximately 4.3x (well above the MAS 1.5x minimum)
- Fixed-rate debt proportion: approximately 55% hedged, providing income certainty
- Weighted average debt maturity: approximately 3.5 years — well-laddered refinancing schedule
- Undrawn credit facilities: approximately S$300–400 million liquidity buffer
USD-denominated income from US data centres is approximately 70% hedged on a rolling 12-month basis via cross-currency swaps and natural hedges, limiting FX drag on DPU. Investors using Endowus for CPF or SRS investment into S-REIT funds can reference our Singapore retirement calculator to model MIT’s contribution to retirement income targets.
Key Risks for MIT Investors
- Interest rate risk: MIT carries ~45% floating-rate debt. A re-acceleration of inflation could reverse recent DPU improvement.
- FX risk: US data centre income (~21% of revenue) is USD-denominated; Japan properties are JPY-denominated. A strengthening SGD reduces net DPU contribution.
- Oversupply in legacy segments: Singapore’s flatted factory and stack-up market faces potential new supply in certain locations, capping rental reversion upside.
- Concentration risk: MBC II and the US data centre portfolio are significant revenue contributors. Vacancy increases would materially impact DPU.
- Lease expiry risk: Approximately 15–20% of Singapore leases expire in FY2026/27, requiring successful renewals at or above passing rents.
- Acquisition execution risk: MIT’s growth thesis partly relies on sponsor pipeline acquisitions. If pricing is elevated or no suitable assets are available, external growth could stall.
Investment Verdict: Buy, Hold or Sell?
For Singapore-based income investors, Mapletree Industrial Trust (ME8U) presents a compelling case as a core industrial REIT holding in 2026 and into 2027. The combination of a ~6.1% forward yield, quarterly income, data centre growth exposure, and Mapletree sponsor backing makes MIT a quality S-REIT for long-term income investors.
At a P/NAV of ~1.23x, MIT trades at a modest premium, but the quality premium is justified by portfolio diversification and the structural tailwind from AI/cloud data centre demand. Investors seeking a higher-yield entry point may wish to accumulate on pullbacks toward S$2.00–2.10 (yield ~6.5–6.8%). For those building a Singapore dividend income portfolio, MIT complements REITs such as CapitaLand Ascendas REIT or Keppel DC REIT with its industrial and data centre hybrid exposure.
TKN Verdict: Hold / Accumulate on Weakness. MIT is a quality industrial REIT that rewards patient income investors. With DPU stabilising and rate headwinds turning into tailwinds, the FY2027 outlook is cautiously positive.
Not financial advice. Past performance is not indicative of future results. Always consult a licensed financial adviser before making investment decisions.
Frequently Asked Questions
What does Mapletree Industrial Trust (ME8U) invest in?
How often does Mapletree Industrial Trust pay dividends?
What is MIT's current dividend yield?
What is MIT's gearing ratio?
How do I buy Mapletree Industrial Trust shares in Singapore?
What is Mapletree Business City (MBC II) and how does it relate to MIT?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.