Medisave Limit 2026: What Happens to Your CPF Medisave After You Die?
CPF Nominations, Final Hospital Bills, and ISP Premium Refunds — A Complete Singapore Estate Planning Guide
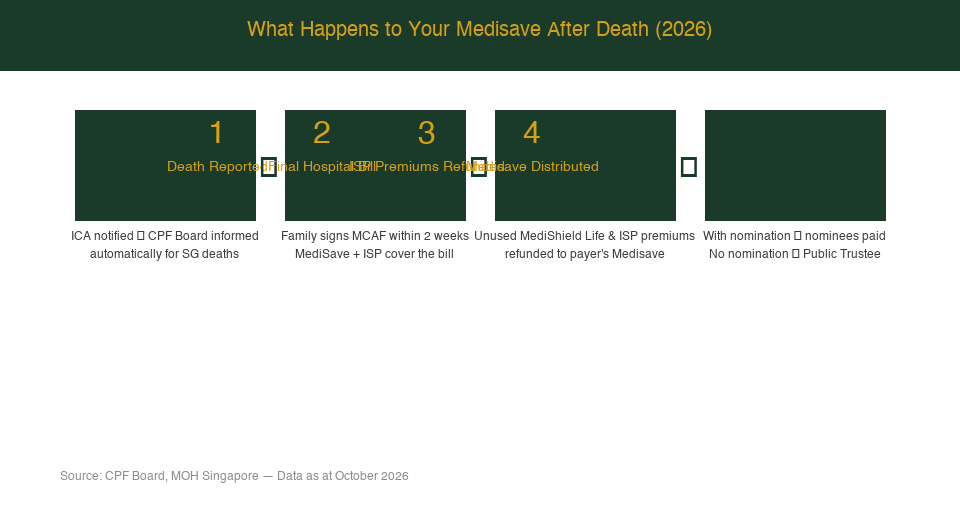
When a CPF member passes away in Singapore, their Medisave account — capped at the 2026 Basic Healthcare Sum (BHS) of $79,000 — does not simply disappear. The family can use it to settle the final hospital bill within two weeks of death using a Medical Claims Authorisation Form (MCAF). The remaining balance is then paid out to CPF nominees within 10 working days, or routed through the Public Trustee under intestacy laws if no nomination exists. Any unused Integrated Shield Plan (ISP) and MediShield Life premiums for the remaining days of the policy year are refunded to the original payer’s Medisave.
Not financial advice. All figures are for educational reference only. Data verified as at 28 October 2026 from CPF Board and MOH official sources.
Table of Contents
Contents — Click to expand
- Overview: What Happens to All Your CPF When You Die?
- Step 1 — Using Medisave for the Final Hospital Bill (MCAF)
- Step 2 — Who Receives the Remaining Medisave Balance?
- What Happens to Your Integrated Shield Plan and MediShield Life?
- Key Medisave Figures for 2026: BHS, Interest, and Limits
- How to Set Up a CPF Nomination in Singapore
- Frequently Asked Questions
Overview: What Happens to All Your CPF When You Die?
Most Singaporeans know that their CPF savings are split into the Ordinary Account (OA), Special Account (SA), MediShield Life Account (MA/Medisave), and — for those aged 55 and above — the Retirement Account (RA). When a CPF member passes away, all four accounts are dissolved and the combined balance is paid out according to one rule: the CPF nomination.
This is a critical point many people miss: your CPF savings, including your Medisave, are NOT governed by your Will. Even if your Will says your savings go to your spouse, CPF savings are distributed separately through the nomination system. A Will has no legal standing over CPF monies.
Here is how the process works at a high level:
| Situation | What Happens to CPF Savings | Timeline |
|---|---|---|
| CPF nomination exists | Nominees receive their designated share in cash | Within 10 working days of notification |
| No CPF nomination | Public Trustee distributes under intestacy laws | Several months (intestacy process) |
| Outstanding hospital bill | Hospital uses Medisave before balance is paid out | Within 2 weeks of death (MCAF signed) |
Source: CPF Board, October 2026. Public Trustee distributes under the Intestate Succession Act (non-Muslims) or Administration of Muslim Law Act (Muslims).
To understand how much Medisave you might be leaving behind, read our guide on the Medisave cap and BHS for 2026, which covers how the Basic Healthcare Sum works and what happens when your Medisave exceeds it.
Step 1 — Using Medisave for the Final Hospital Bill (MCAF)
Before any CPF savings are distributed to nominees, the deceased’s outstanding hospital bill needs to be settled. This is where the Medical Claims Authorisation Form (MCAF) comes in.
If the deceased signed an MCAF before passing away, the hospital can claim Medisave directly without involving the family. But if no MCAF was signed, certain family members can step in and authorise the claim within a limited window.
Who Can Sign the MCAF After Death?
According to the CPF Board, the following persons may sign an MCAF within 2 weeks of the date of death:
- Spouse of the deceased
- Parent of the deceased
- Child aged 21 and above
- Donee under a Lasting Power of Attorney (LPA)
- Deputy appointed by the Court
If none of the above are available, other relatives may sign the MCAF but will need MOH approval. The hospital’s billing department can guide families through this process.
Why the 2-Week Deadline Matters
This is a strict deadline. The hospital must submit the Medisave claim before CPF savings are paid out to nominees. Once the balance has been distributed, it cannot be reclaimed from nominees to pay the hospital. Acting quickly after a bereavement is essential to ensure the bill is properly settled using the Medisave funds.
For a step-by-step breakdown of how Medisave claims work for hospitalisation generally, see our Medisave hospitalisation claims guide.
Step 2 — Who Receives the Remaining Medisave Balance?
After the final hospital bill has been settled (if any), the remaining balance across all CPF accounts — including Medisave — is distributed based on whether a CPF nomination exists.
Scenario A: A CPF Nomination Exists
If the deceased had a valid CPF nomination, the CPF Board contacts nominees after being notified of the death. Eligible nominees who are Singapore Citizens or PRs, aged 18+, with a local address and a CPF-registered bank account are paid automatically within 10 working days — no application needed. All other nominees must submit a withdrawal application via Singpass.
Nominees receive cash, not CPF credits. The payout cannot be deposited into a nominee’s own CPF — it is a one-time cash payment to a bank account.
Scenario B: No CPF Nomination
Without a valid CPF nomination, the CPF Board transfers the monies to the Public Trustee’s Office, which distributes under intestacy laws:
- Non-Muslims: Intestate Succession Act — spouses and children share equally, then parents, then siblings, in order of priority.
- Muslims: Administration of Muslim Law Act (AMLA) — distribution follows the faraid system.
This process typically takes several months and involves legal paperwork — significantly slower than a CPF nomination payout. CPF savings also stop earning interest after the date of death.
For more context on how the CPF Medisave account works throughout a member’s lifetime, our guide covers contribution rates, withdrawal conditions, and the BHS in detail.
What Happens to Your Integrated Shield Plan and MediShield Life?
When a CPF member passes away, their insurance coverage under MediShield Life and any Integrated Shield Plan (ISP) is terminated. But what happens to the premiums already paid for that policy year?
MediShield Life and ISP Premiums
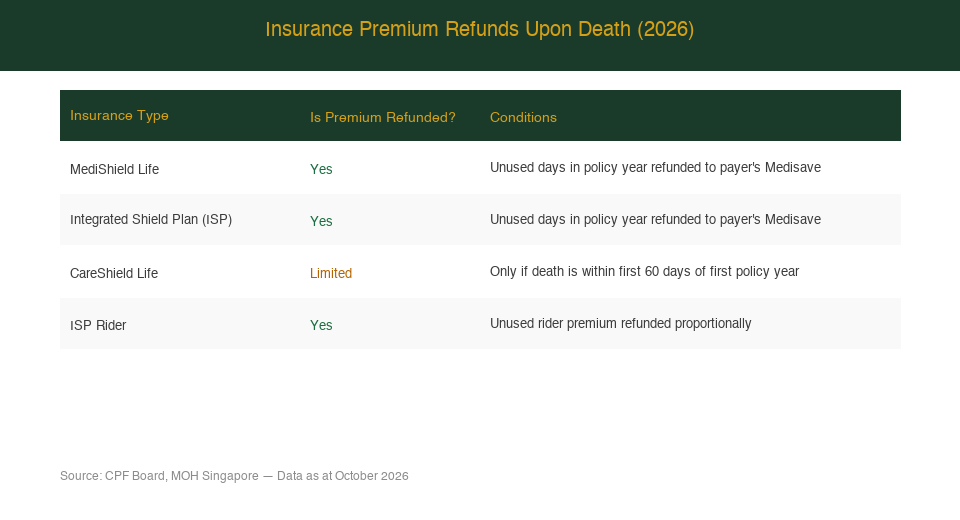
For both MediShield Life and any ISP, the unused premiums for the remaining days in the policy year are refunded to the payer’s Medisave. If you were paying your parent’s ISP from your own Medisave, the refund comes back to you — not to your parent’s estate.
For example, if the member passed away 6 months into a 12-month ISP policy year, approximately half the annual ISP premium would be refunded to the Medisave account that paid for it.
CareShield Life: The Exception
CareShield Life has a different refund rule: premiums are only refunded if death occurs within the first 60 days of the first policy year. After that window, CareShield Life premiums are not refunded on death — unlike ISP and MediShield Life.
ISP Rider Premiums
ISP rider premiums follow the same rules as the main ISP — unused days are refunded to the payer’s Medisave. For context on how ISP riders have changed, see our guide on ISP rider changes in 2025 and 2026.
| Insurance Type | Premium Refund on Death? | Refunded To |
|---|---|---|
| MediShield Life | Yes — unused days refunded | Payer’s Medisave |
| Integrated Shield Plan (ISP) | Yes — unused days refunded | Payer’s Medisave |
| ISP Rider | Yes — unused days refunded | Payer’s Medisave |
| CareShield Life | Only within first 60 days of first policy year | Payer’s Medisave (if eligible) |
Source: CPF Board official guidance, October 2026.
Key Medisave Figures for 2026: BHS, Interest, and Limits
Understanding the key Medisave figures for 2026 helps you estimate how much a CPF member might leave behind — and what nominees can expect to receive.
Basic Healthcare Sum (BHS) 2026
The Basic Healthcare Sum (BHS) for 2026 is $79,000. This is the maximum that can be held in a Medisave account for CPF members below age 65. Medisave contributions above this cap are automatically transferred to other CPF accounts. Once a member turns 65, their BHS is locked at the prevailing figure at that time.
Medisave Interest Rate
Medisave earns 4% per year (the SMRA rate, with a guaranteed floor of 4%). Members under 55 also earn an additional 1% on the first $60,000 of combined CPF balances (OA component capped at $20,000 for this purpose). After death, CPF savings stop earning interest.
How Much Medisave Might Be Left Behind?
The actual balance at death varies based on the member’s age, employment history, and healthcare usage. A healthy, long-employed member may have close to the $79,000 BHS cap. A member with significant hospitalisations may have a lower balance. For more detail on how contributions and caps work, see our Medisave limit 2026 guide.
How to Set Up a CPF Nomination in Singapore
A CPF nomination is the single most important estate planning step for CPF members. Without one, your Medisave and all other CPF savings go through the Public Trustee — adding months of delay and complexity for your family.
The good news: setting up a CPF nomination is free, fully digital via Singpass, and takes under 15 minutes.
How to Make a CPF Nomination
- Log in to cpf.gov.sg using your Singpass.
- Navigate to My CPF > My Home > Nominations.
- Click “Make a Nomination” and enter your nominees’ details (NRIC/passport number, relationship, address).
- Specify the percentage allocation for each nominee — allocations must total 100%.
- Submit online with digital witness signatures via Singpass.
Key Rules to Know
- Up to 10 nominees may be named in a single nomination.
- No legal fees — the process is entirely free.
- Nominations can be updated anytime, particularly after marriage, divorce, or the birth of a child.
- Marriage automatically revokes a prior CPF nomination — unlike insurance policy nominations. You must make a new nomination after getting married or your savings will go to the Public Trustee even if you have a Will.
- A CPF nomination only covers CPF savings. Other assets (bank accounts, property, unit trusts) are governed separately by your Will or joint ownership structures.
If you are reviewing your ISP coverage as part of a broader estate planning exercise, the Shield plan comparison for 2026 can help you find the right coverage for your family’s healthcare needs.
Frequently Asked Questions
What happens to Medisave if there is no CPF nomination?
Can my family use my Medisave for funeral expenses?
How long does it take for CPF nominees to receive the Medisave balance?
What is the Medisave limit in 2026 and will my nominees get the full amount?
Does making a Will cover my CPF Medisave savings?
Is my ISP premium refunded if I die mid-policy year?
Can I nominate a non-Singaporean to receive my CPF Medisave?
Review Your ISP Coverage Today
A robust Integrated Shield Plan reduces your lifetime out-of-pocket healthcare costs — and a proper CPF nomination ensures your Medisave reaches your loved ones without delays. Start by comparing ISPs across all major Singapore insurers.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.