How to Start Investing in Singapore: The 5 Accounts You Need (2026)
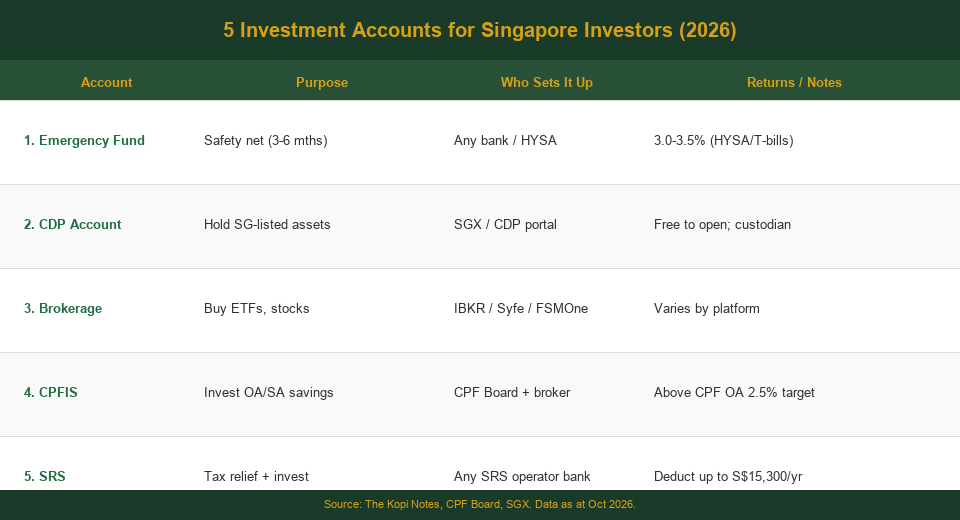
How to start investing in Singapore? Before picking any ETF or stock, you need the right accounts. Most beginners skip this step and end up unable to buy the assets they want, missing CPF/SRS tax benefits, or paying avoidable fees. This guide walks you through the 5 accounts every Singapore investor needs — in the order you should set them up.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
Account 1: Emergency Fund — Your Foundation
Before you invest a single dollar, you need 3-6 months of living expenses in a liquid, accessible account. This is non-negotiable. Without it, a job loss or medical emergency forces you to sell your investments at the worst possible time.
Where to Park Your Emergency Fund in 2026
High-yield savings accounts (HYSAs) and short-duration T-bills are currently yielding 3.0-3.5% — far better than the 0.05% you get in a standard POSB/DBS savings account. The latest 6-month T-bill (8 October 2026) cut-off yield was 1.90%, while 12-month T-bills are closer to 2.0-2.3%. HYSAs from trust banks and digital banks remain competitive at 3-3.5% with near-zero lock-up.
Tip: Keep 3 months in a HYSA for immediate access, and park the other 3 months in T-bills or a Singapore Savings Bond for a slightly better return.
| Option | Rate (Oct 2026) | Liquidity | Best For |
|---|---|---|---|
| HYSA (e.g. Trust Bank) | ~3.0-3.5% | Instant | Immediate access fund |
| 6M T-bill | ~1.90% | 6 months | Slightly higher yield |
| SSB (Nov 2026) | 2.45% (10Y avg) | 1 month notice | Flexible, govt-backed |
Source: MAS T-bill results (8 Oct 2026), MAS SSB announcement (Nov 2026 issue).
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
Learn more about Singapore T-bills 2026 guide and Singapore Savings Bonds guide.
Account 2: CDP Account — Your SGX Custodian
The Central Depository (CDP) account is where SGX-listed securities are held in your name. Unlike overseas brokerages (where the broker is the nominee), CDP directly registers ownership of Singapore shares and ETFs to you. It is free to open and maintained by SGX.
Who Needs a CDP Account?
You need CDP if you plan to buy Singapore-listed ETFs, REITs, or Singapore stocks. If you only intend to buy US or LSE-listed ETFs via an overseas broker like IBKR, you may not need CDP immediately — IBKR holds those in their own custodial structure.
How to Open CDP
Apply at cdp.sgx.com using Singpass. You will also need to link a bank account (DBS/POSB, OCBC, UOB, or Citibank). The whole process takes under 15 minutes online; account activation takes 1-3 business days.
CDP is free. There is no annual fee. Open it early — you cannot buy SGX-listed assets without it.
Account 3: Brokerage Account — Where You Actually Buy
A brokerage account is the trading platform through which you execute buy and sell orders. Different brokerages give you access to different markets and asset classes, so your choice depends on what you plan to invest in.
Key Brokerages for Singapore Investors
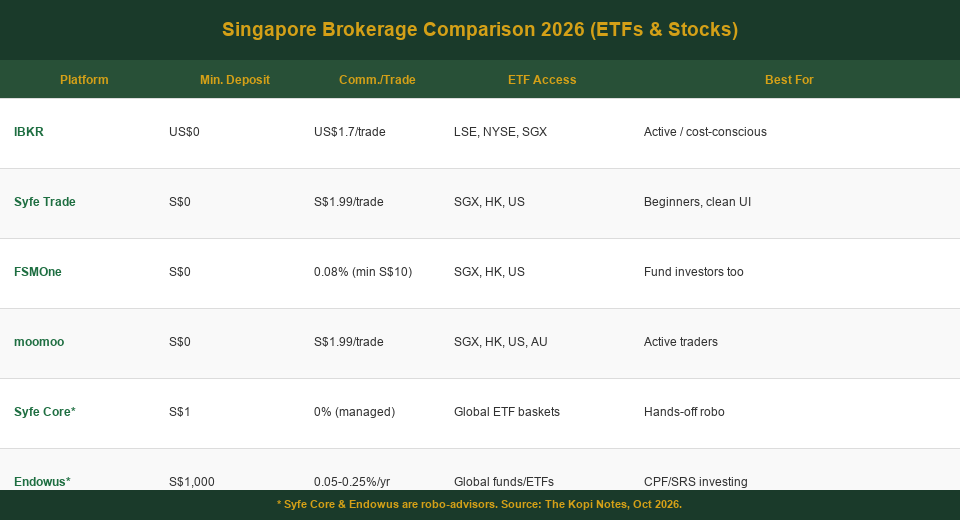
For most beginner investors buying global ETFs (VWRA, CSPX) on the London Stock Exchange, Interactive Brokers (IBKR) offers the lowest commissions at approximately US$1.70 per trade. For a more user-friendly experience, Syfe Trade and FSMOne are popular choices. Use Syfe referral code SRPRFFFCD or FSMOne referral code P0544985.
For hands-off investing, Syfe Core and Endowus are robo-advisors that manage diversified ETF baskets for you. Use Endowus referral code 2V343 for a fee rebate. See our moomoo Singapore review if you prefer active trading.
Account 4: CPFIS — Invest Your CPF Savings
The CPF Investment Scheme (CPFIS) lets you invest the funds in your CPF Ordinary Account (OA) and Special Account (SA) in approved instruments — including unit trusts, ETFs, and SGX stocks.
Is CPFIS Worth Using?
Your CPF OA earns a guaranteed 2.5% per annum. Your SA earns 4.0% per annum (floor rate extended to December 2027 by the CPF Board). For CPFIS to make sense, your investments must consistently beat these rates net of fees and risk — a bar that most retail investors do not clear over the long term.
Use CPFIS only if you have a clear investment plan that targets returns above CPF guaranteed rates. Many Singaporeans are better off leaving CPF OA to compound at 2.5%.
How to Set Up CPFIS
Apply via the CPF website at cpf.gov.sg using Singpass. You will need to open a CPFIS-approved account with a participating bank or broker. See our CPF investment strategy guide for a full breakdown.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
Account 5: SRS Account — Tax Relief + Retirement Investing
The Supplementary Retirement Scheme (SRS) is a voluntary government scheme that offers immediate tax relief for every dollar you contribute, while your investments grow tax-deferred until withdrawal at retirement age.
SRS Contribution Limits (2026)
Singapore citizens and PRs can contribute up to S$15,300 per year. Foreigners can contribute up to S$35,700. Every dollar contributed reduces your chargeable income for that year.
| Taxpayer Type | Annual SRS Cap | Tax Saving (11.5% bracket) |
|---|---|---|
| Citizen / PR | S$15,300 | ~S$1,760/yr |
| Foreigner | S$35,700 | ~S$4,106/yr |
Source: IRAS, CPF Board. SRS cap for citizens/PRs as at 2026.
Withdrawal Rules
You can begin withdrawing from SRS without penalty from the statutory retirement age, which is 64 years old from 1 July 2026 (previously 63). Only 50% of withdrawals are taxed, and spreading them over 10 years can reduce tax to near zero. Early withdrawal incurs a 5% penalty plus full income tax on the amount.
Open your SRS account at DBS, OCBC, or UOB. Even contributing S$1 keeps the account open and you can top it up anytime.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
What Order Should You Open These Accounts?
Not everyone needs all five accounts at once. Here is the recommended sequence:
- Emergency Fund — Build this first. No exceptions.
- CDP Account — Free and fast. Open it now so it is ready.
- Brokerage Account — Pick one and start investing.
- SRS Account — Open when your income hits the 7% tax bracket.
- CPFIS — Only if you have a plan to beat CPF guaranteed rates.
Most beginners only need accounts 1-3. SRS and CPFIS are optimisations for later.
Your 6-Month Action Plan
| Month | Action | Goal |
|---|---|---|
| Month 1 | Open HYSA or T-bill ladder | Emergency fund earning 3%+ |
| Month 2 | Open CDP account (Singpass) | SGX access ready |
| Month 3 | Open brokerage (IBKR or Syfe Trade) | Buy first ETF |
| Month 4-5 | Automate monthly investments | Dollar-cost averaging in place |
| Month 6 | Open SRS (if applicable) | Tax relief before year-end |
Note: SRS is most valuable if opened before 31 Dec to capture that year’s tax deduction.
Try our Singapore retirement calculator to see how much you need. Once your brokerage is set up, explore passive income strategies in Singapore.
Frequently Asked Questions
How much money do I need to start investing in Singapore?
Do I need a CDP account to invest in ETFs?
What is the best brokerage for beginners in Singapore in 2026?
Should I use CPFIS or leave my CPF in OA/SA?
When should I open an SRS account?
How is SRS different from CPF?
Ready to Start Investing?
Use these referral codes when signing up:
- Syfe — code SRPRFFFCD
- Endowus — code 2V343
- FSMOne — code P0544985
- Trust Bank (HYSA) — code HTWYQP95
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.