INTEGRATED SHIELD PLAN REVIEW 2026
Great Eastern SupremeHealth B Plus 2026: Complete Review
B1 Ward Premiums, GREAT TotalCare 2 Rider & Claims-Based Pricing
Data verified as at 22 September 2026 · Source: Great Eastern official benefit schedule, 1 April 2026
Table of Contents
What Is GREAT SupremeHealth B Plus?
2026 Premium Table
Plan Comparison
GREAT TotalCare 2 Rider
Who Should Get B Plus?
⚡ Quick Verdict
GREAT SupremeHealth B Plus is a solid, affordable ISP for Singaporeans who want B1-ward-and-below coverage with a generous $500,000 annual limit. At just $92.65/year for a 31–35-year-old, it is one of the lowest-cost ISPs in this coverage tier. The biggest watch-out: Great Eastern uses claims-based pricing, so your premium may jump significantly after hospitalisation.
What Is GREAT SupremeHealth B Plus?
GREAT SupremeHealth B Plus is Great Eastern’s mid-tier Integrated Shield Plan (ISP), designed to supplement your basic MediShield Life coverage. It pays “as charged” for hospitalisation in Class B1 wards (and below) in restructured hospitals, with no sublimit on most bills.
Key eligibility rules to know upfront:
- Singapore Citizens and Permanent Residents only — foreigners and employment pass holders are NOT eligible for B Plus
- Must be a Singapore resident insured under MediShield Life
- Enrolment available from birth; maximum entry age varies by plan tier
Key Benefits & Coverage
All figures below are verified from the official Great Eastern benefit schedule effective 1 April 2026 (document reference: GSHGTCP/Ver1.0/202604).
| Benefit | B Plus Detail |
|---|---|
| Ward class | Class B1 and below, restructured hospitals |
| Annual limit | $500,000 |
| Deductible (B1 ward) | $2,500 per policy year |
| Co-insurance | 10% of claimable amount |
| Co-payment cap (with GTC2 B rider) | $6,000 per policy year |
| Pre-hospitalisation | 90 days (180 days for Panel Provider visits) |
| Post-hospitalisation | 180 days (365 days for Panel Provider visits) |
| Claimable basis | As Charged (no sublimits on most items) |
The “As Charged” basis is important: unlike older-generation plans that cap specific benefits (e.g. ICU at $X/day), B Plus covers the actual bill up to the $500,000 annual limit. This protects against unexpectedly large bills for complex surgeries or ICU stays.
2026 B Plus Premium Table
All premiums below are for Singapore Citizens and Permanent Residents, inclusive of 9% GST, effective 1 April 2026. Premiums marked with * include a cash component that exceeds the MediSave Additional Withdrawal Limit (AWL) for that age band.
| Age Band | Annual Premium | Cash Top-Up Needed | MediSave AWL |
|---|---|---|---|
| 21–25 | $77.39 | — | $300 |
| 26–30 | $77.39 | — | $300 |
| 31–35 | $92.65 | — | $300 |
| 36–40 | $104.64 | — | $300 |
| 41–45 | $165.68 | — | $600 |
| 46–50 | $175.49 | — | $600 |
| 51–55 | $289.94 | — | $600 |
| 56–60 | $344.44 | — | $600 |
| 61–63 | $455.62 | — | $600 |
| 64–65 | $587.51 | — | $600 |
| 66–68 * | $758.64 | $158.64 | $600 |
| 69–70 * | $989.72 | $389.72 | $600 |
* Cash top-up required as the premium exceeds the MediSave AWL for that age band. Source: GREAT SupremeHealth Benefit Schedule, Great Eastern, 1 April 2026.
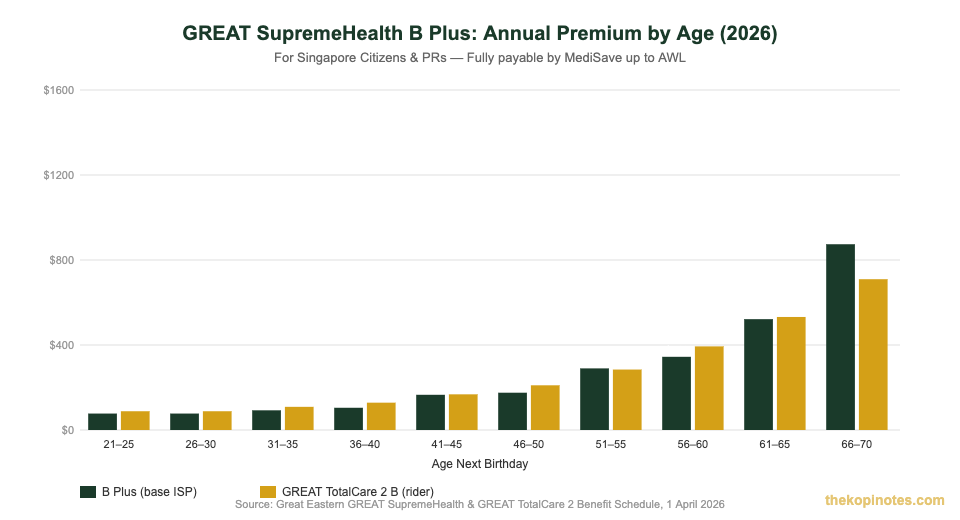
Chart: B Plus base premium (dark green) vs GREAT TotalCare 2 B rider (gold) by age group. Source: Great Eastern, 1 April 2026.
Understanding MediSave Additional Withdrawal Limits (AWLs)
Your MediSave can fund ISP premiums up to the AWL for your age band:
- Up to age 40: AWL = $300/year
- Age 41–70: AWL = $600/year
- Age 71+: AWL = $900/year
For most working-age Singaporeans, the B Plus base premium fits within the AWL — meaning you can fund it entirely from MediSave with no cash outlay. This changes from age 66 onwards, when the premium exceeds $600 and you must pay the difference in cash.
B Plus vs Standard vs A Plus: Which Tier Is Right for You?
SupremeHealth comes in four main tiers. The table below compares the three most popular ones — Standard, B Plus, and A Plus — using verified 2026 data.
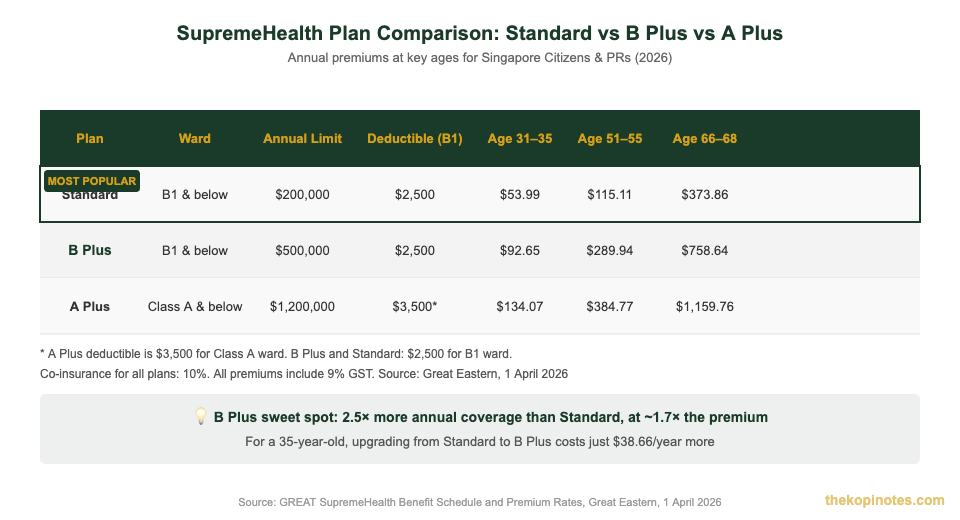
Source: Great Eastern official benefit schedule, 1 April 2026.
The key insight: B Plus hits a sweet spot. Upgrading from Standard to B Plus costs just $38.66/year more for a 35-year-old, but raises your annual limit from $200,000 to $500,000 — a 2.5× improvement. The jump to A Plus adds Class A ward access but also introduces a higher deductible ($3,500 vs $2,500) and significantly higher premiums, especially at older ages.
For most Singaporeans comfortable with B1-ward care, B Plus delivers excellent value. A Plus makes sense only if you specifically want the option of Class A single-room accommodation.
GREAT TotalCare 2 (GTC2) B Rider: Capping Your Out-of-Pocket Costs
Without a rider, B Plus leaves you exposed to the $2,500 deductible plus 10% co-insurance on every admission. The GREAT TotalCare 2 (GTC2) B rider caps your total annual cash outlay at $6,000 per policy year, covering the deductible and co-insurance beyond that cap.
GTC2 B rider premiums (2026, all-cash — not MediSave-payable):
| Age Band | GTC2 B Rider (Annual) |
|---|---|
| 31–35 | $109.00 |
| 36–40 | $128.62 |
| 41–45 | $167.86 |
| 46–50 | $210.37 |
| 51–55 | $284.49 |
| 56–60 | $393.49 |
Source: GREAT SupremeHealth Benefit Schedule, Great Eastern, 1 April 2026. Rider premiums are payable in cash only.
For a 33-year-old, adding the GTC2 B rider brings the combined annual cost to $201.65/year ($92.65 base + $109 rider). That’s about $16.80/month for full ISP coverage with a $6,000/year cash cap.
⚠️ Claims-Based Pricing: What You Must Know Before Buying
Great Eastern is one of the few insurers in Singapore that uses claims-based pricing for its ISP products. This means your individual premium can increase above the standard age-band rate if you make claims — unlike community-rated insurers where all policyholders in the same age band pay the same premium regardless of claims history.
How it works in practice:
- If you make claims, GE may charge you a higher loading on your renewal premium
- The loading is proportional to the amount and frequency of your claims
- Healthy policyholders (no claims) typically pay the published base rates above
- Policyholders with significant claim histories may pay materially more than the base table rates
This is a meaningful financial consideration for anyone with chronic conditions or who anticipates needing regular hospitalisation. If premium predictability is important to you, compare GE B Plus against insurers that use purely age-band (community) pricing, such as AIA, Prudential, or NTUC Income.
Who Should Get GREAT SupremeHealth B Plus?
B Plus is a good fit if you:
- Are a Singapore Citizen or PR in good health (no pre-existing conditions likely to trigger claims loading)
- Want affordable B1-ward coverage with a high annual limit
- Are comfortable using restructured hospitals and Panel Providers
- Prefer to fund the premium entirely from MediSave (works for ages up to ~65)
- Already have existing Great Eastern life insurance and want to consolidate with one insurer
Consider alternatives if you:
- Have chronic conditions or anticipate frequent hospitalisation (claims loading risk)
- Want Class A single-room access (look at SupremeHealth A Plus or P Plus instead)
- Are a foreigner or EP holder (B Plus is SC/PR only)
- Prioritise predictable premiums over all else (consider community-rated ISPs)
Overall, GREAT SupremeHealth B Plus remains competitive in 2026. Its base premiums are among the most affordable in the B1-ward ISP segment, and the $500,000 annual limit is meaningfully higher than the Standard plan. Just go in aware of the claims-based pricing model.
Frequently Asked Questions
What is the annual premium for GREAT SupremeHealth B Plus in 2026?
The 2026 annual premium for GREAT SupremeHealth B Plus starts at $77.39/year for those aged 21–30, rising to $92.65/year for ages 31–35 and $104.64/year for ages 36–40. All premiums are inclusive of 9% GST and verified from the Great Eastern official benefit schedule effective 1 April 2026. For ages 66 and above, a cash top-up is required as premiums exceed the MediSave AWL.
Can foreigners get GREAT SupremeHealth B Plus?
No. GREAT SupremeHealth B Plus is available to Singapore Citizens and Permanent Residents only. Foreigners, employment pass holders, and dependant pass holders are not eligible. Foreigners may consider Great Eastern’s other health insurance products, but the ISP range is restricted to SC/PR holders who are covered under MediShield Life.
What is the GREAT TotalCare 2 rider and do I need it?
The GREAT TotalCare 2 (GTC2) B rider is an optional add-on that caps your annual cash out-of-pocket at $6,000 per policy year by covering the $2,500 deductible and 10% co-insurance after the cap is reached. Without the rider, you are exposed to these costs every hospitalisation. The rider is recommended for most policyholders — at just $109/year for a 31–35-year-old, the peace of mind is well worth it. Rider premiums are payable in cash only (not MediSave).
What is claims-based pricing and how does it affect my premium?
Claims-based pricing means your individual ISP premium can increase above the published base rate if you make claims. Great Eastern is one of a small number of Singapore ISP providers that uses this model. If you are a healthy policyholder with no claims, you typically pay the base table rate. If you make claims — especially large ones — GE may apply a loading to your renewal premium. The size of the loading depends on claim frequency and severity. This is the biggest risk factor for B Plus buyers with existing health conditions.
What wards does GREAT SupremeHealth B Plus cover?
B Plus covers hospitalisation in Class B1 wards and below at restructured hospitals. This includes Class B1 (4–6 beds per room), Class B2, and Class C wards. It does not cover Class A (single room) or private hospital wards. If you want Class A access, you would need to upgrade to SupremeHealth A Plus or higher.
How much of the B Plus premium can I pay from MediSave?
You can use MediSave to pay the B Plus base premium up to the MediSave Additional Withdrawal Limit (AWL) for your age band: $300/year up to age 40, $600/year from age 41–70, and $900/year from age 71. For most working-age Singaporeans, the B Plus premium falls within the AWL — so you can pay it entirely from MediSave. From age 66, the premium exceeds $600 and you must pay the difference in cash. The GTC2 rider premium is always cash-only and cannot be funded from MediSave.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.