Critical Illness Insurance Singapore 2026: How Much Coverage Do You Actually Need?
Critical illness insurance pays you a tax-free lump sum if you are diagnosed with cancer, heart attack, stroke, or any of 36 other major illnesses under the LIA CI Framework 2024. The Life Insurance Association Singapore benchmarks CI coverage at five times your annual income — enough to replace your salary for five years while you recover. Most Singaporeans fall far short of this: the average CI recovery gap is S$170,000, according to Singlife’s 2026 study, and Singapore’s total CI protection gap stands at an estimated S$580 billion.
Not financial advice. All figures are for educational reference only. Data verified as at 21 September 2026 unless otherwise noted.
- Target at least 5x your annual income in CI coverage — the LIA benchmark for a five-year recovery period
- Your Integrated Shield Plan covers hospital bills, but not the income you lose during recovery
- Use the four-step formula: income replacement + remaining debts + medical gaps + recovery costs
Why Most CI Coverage Falls Short
Seven in ten Singaporeans are underinsured for critical illness. The LIA’s Protection Gap Study found that 74% of economically active individuals do not have sufficient CI coverage — down from 81% in 2017, but still far too high. The total CI protection gap in Singapore reached an estimated S$580 billion as of 2025.
The most common mistake is confusing CI insurance with hospitalisation coverage. Your Integrated Shield Plan and MediShield Life pay your hospital bills. CI insurance does something different. It hands you a lump-sum payout when you are diagnosed — regardless of your actual hospital bill. That lump sum is meant to cover the income you lose while you recover, the debts that keep coming in, and the out-of-pocket costs your ISP will not touch.
Most people think S$100,000 of CI coverage is enough. For someone earning S$5,000 a month, that covers just over 20 months of income — well short of the five-year benchmark. A cancer recovery alone can take three to five years, and heart disease or stroke may mean permanent lifestyle adjustments that reduce your earning capacity long after discharge.
Singlife’s 2026 Critical Illness study found the average Singaporean faces a S$170,000 CI recovery gap. That gap accounts for lost income, out-of-pocket medical costs, and recovery expenses that no policy currently covers.
The LIA 5-Year Rule Explained
The Life Insurance Association Singapore uses a five-year recovery period as its benchmark for how long a major illness typically keeps you off work or at reduced capacity. Your CI coverage should be large enough to replace your full salary for those five years.
Here is how the maths works. If you earn S$5,000 a month, your annual income is S$60,000. Multiply that by five and you get S$300,000 — that is your minimum CI sum assured target. Add debts and medical gaps on top, and the recommended figure climbs higher.
The five-year figure is not arbitrary. Studies on cancer recovery in Singapore consistently show that three to five years is needed to return to full earning capacity after treatment, even with good medical outcomes. Heart attack survivors may need six to twelve months of cardiac rehabilitation before returning to demanding work, and stroke patients can take longer still.
You can link this to your Singapore retirement calculator to see how a five-year income gap would affect your retirement savings — the compounding loss is significant.
How to Calculate Your CI Coverage Needs
Use these four components to arrive at your personalised CI sum assured. Add them all up, then subtract any CI coverage you already hold.
Component 1: Income Replacement
Multiply your annual income by five. This is your base. For a monthly salary of S$6,000, that is S$72,000 a year, or S$360,000 over five years. This component alone already exceeds what most people in Singapore currently hold.
Component 2: Outstanding Debts
Add two years of mortgage or loan repayments. You need to service your debts even when you are not working. Two years is a conservative buffer — it gives you time to restructure finances without defaulting. For a monthly mortgage of S$2,000, that is S$48,000.
Component 3: Medical Cost Gaps
Your ISP covers hospitalisation, but not everything. Specialist consultations, certain outpatient chemotherapy drugs not on the Cancer Drug List, traditional Chinese medicine, and post-discharge physiotherapy all come out of pocket. Budget S$20,000 to S$50,000 depending on the illness. For this worked example, use S$30,000.
Component 4: Recovery and Rehabilitation
Budget separately for lifestyle adjustments during recovery — dietary changes, home care, transport to clinic appointments, or temporary domestic help if your condition limits mobility. S$20,000 is a reasonable minimum. More serious conditions may require S$50,000 or more.
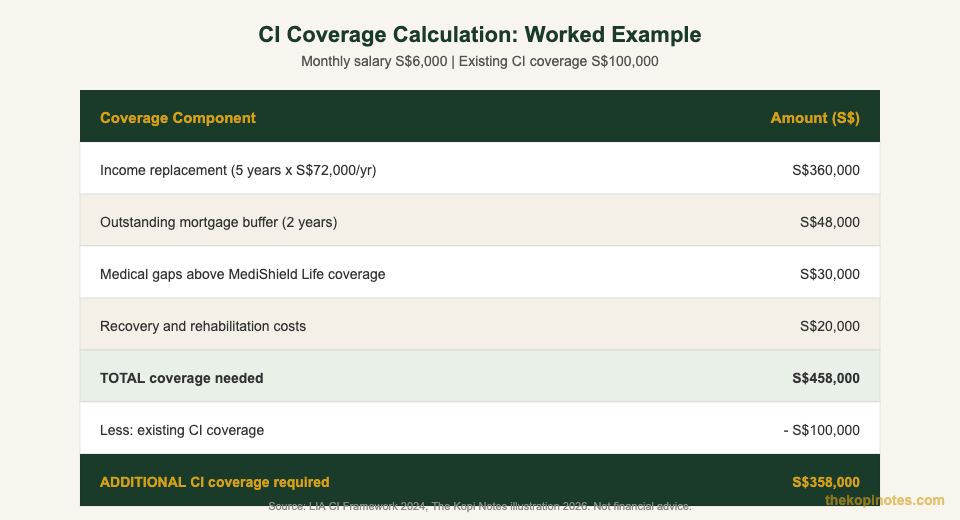
Source: LIA CI Framework 2024, The Kopi Notes illustration 2026. Figures are illustrative. Not financial advice.
In this worked example, someone earning S$6,000 a month with S$100,000 in existing CI coverage needs an additional S$358,000 in CI sum assured to meet the LIA benchmark. That does not mean buying one giant policy — you can layer a standalone CI plan on top of a CI rider on your term or whole life plan. See our guide on CI insurance: term plan versus whole life rider for how to structure this efficiently.
CI Coverage by Income Level
The table below summarises the minimum and recommended CI coverage targets across four common income brackets in Singapore. The recommended figure adds a buffer for debts and medical gaps above the five-year income replacement base.
| Monthly Income | Annual Income | Min CI (5x) | Recommended CI |
|---|---|---|---|
| S$3,000 | S$36,000 | S$180,000 | S$200,000 – S$250,000 |
| S$5,000 | S$60,000 | S$300,000 | S$320,000 – S$380,000 |
| S$8,000 | S$96,000 | S$480,000 | S$500,000 – S$600,000 |
| S$12,000 | S$144,000 | S$720,000 | S$750,000 – S$900,000 |
Source: LIA Protection Gap Study 2022, LIA CI Framework 2024. Recommended range includes debt buffer and estimated medical gaps. Not financial advice.
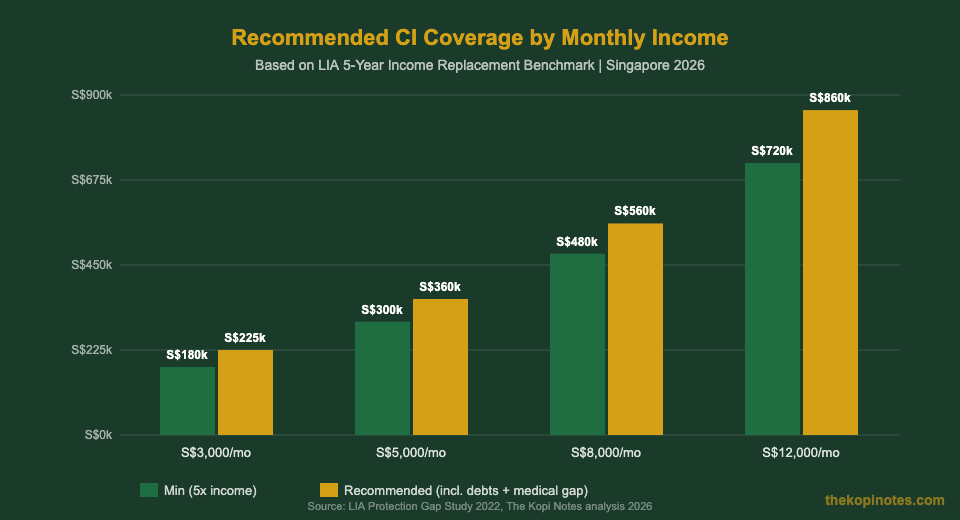
Source: LIA Protection Gap Study 2022, LIA CI Framework 2024, The Kopi Notes analysis 2026.
These figures assume you have no existing CI coverage. If you already hold a CI rider through your whole life policy, subtract that sum assured from the recommended figure to find how much additional standalone CI cover you need. For a deeper look at what happens when you actually claim, read our article on what your CI lump sum actually covers.
How CI Insurance Works Alongside MediShield Life
Many Singaporeans confuse their Integrated Shield Plan with CI insurance. They serve completely different purposes, and you need both.
Your ISP and MediShield Life cover your hospitalisation bills — ward charges, surgical fees, and inpatient treatments. The insurer pays the hospital directly. You never see the money as cash.
CI insurance is different. When you are diagnosed with a covered illness, the insurer pays you a lump sum. You decide how to use it: pay off your mortgage, fund your children’s school fees, hire a caregiver, or simply replace the income you are no longer earning. The payout is independent of your hospital bill.
The Chemotherapy Gap — A Practical Example
Chemotherapy in Singapore can cost S$4,000 or more per session, according to the Ministry of Health. MediShield Life raises its claim limits to S$3,000 per month for chemotherapy. That still leaves a potential S$1,000+ gap per month from chemo costs alone — before you count lost income, transport to the cancer centre, dietary supplements, and the emotional cost of not working.
| Cost Category | Monthly Cost (est.) | ISP Covers | Your Gap |
|---|---|---|---|
| Chemotherapy drugs | S$4,000+ | S$3,000 | S$1,000+ |
| Specialist outpatient visits | S$300 – S$800 | Partial (if inpatient) | S$300 – S$800 |
| Lost income (S$5k/mo salary) | S$5,000 | S$0 | S$5,000 |
| Recovery and caregiving | S$500 – S$2,000 | S$0 | S$500 – S$2,000 |
Source: Ministry of Health Singapore, MediShield Life claim limits 2026. Estimates for illustration only.
This is why CI coverage matters even when you have a comprehensive ISP. The ISP handles the bill. CI insurance handles your life while you recover.
If you are weighing whether to add an early-stage CI rider to your plan, read our comparison of early-stage versus late-stage CI coverage — the difference in payout timing can be material.
CI Coverage at Different Life Stages
Your CI coverage needs change as your life changes. The right sum assured at 28 is very different from what you need at 45 or 58.
| Life Stage | Key Financial Risk | CI Priority |
|---|---|---|
| Young adult (25–35) | Income loss, career disruption | Standalone term CI + early-stage cover |
| Family stage (35–50) | Mortgage, dependent children | Higher sum assured, consider multi-pay CI |
| Pre-retirement (50–65) | Lower income risk, higher health risk | Whole life CI component, confirm cover stays past 65 |
Source: LIA Singapore guidance, The Kopi Notes analysis 2026.
At 25 to 35, your biggest risk is losing a decade of compounding returns if you get sick and cannot work. Buy as much standalone term CI as you can afford early — premiums are lowest in your late 20s and early 30s.
At 35 to 50, you likely have a mortgage and dependent children. This is when a multi-pay CI plan becomes worth evaluating. Multi-pay plans pay out once per illness category, so a cancer diagnosis and a subsequent heart attack could each trigger a separate payout.
From 50 onwards, your earned income is shorter-lived but your health risk is highest. Confirm that your CI policy does not lapse at 65 or 70 — many term CI policies do. A whole life CI component that lasts until death gives you permanent protection, though premiums are significantly higher if purchased late.
If your claim is ever in doubt, it helps to know in advance what can go wrong. Our article on why CI claims get rejected covers the six most common exclusions that catch policyholders off guard.
If you are considering how CI fits into your broader financial plan, the Endowus referral code gets you up to S$20 cashback when you start investing your spare premiums — a useful complement to your protection planning.
Frequently Asked Questions
How much critical illness insurance do I need in Singapore?
Is S$100,000 of critical illness insurance enough?
Does my Integrated Shield Plan cover critical illness?
What illnesses are covered under critical illness insurance in Singapore?
Should I get a CI rider or a standalone CI plan?
How does the September 2026 rate hike affect CI insurance premiums?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.