Disability Income Insurance Waiting Period Singapore: Which Deferment Period Saves You the Most?
The waiting period on your disability income insurance is the one variable that can cut your annual premium by 30 to 45 percent — or leave you scrambling for cash when you need it most. In Singapore, most DI plans offer deferment periods ranging from 30 to 180 days. After the September 2026 Fed rate hike pushed local savings rates above 3%, the calculus has shifted. Here is how to pick the right waiting period for your income and lifestyle.
Not financial advice. All premium figures are indicative estimates for educational reference only. Data verified as at September 2026. Speak to a licensed financial adviser before purchasing any insurance product.
- A longer waiting period means lower premiums – going from 30 days to 90 days typically saves you around 30% per year
- The right deferment period equals your employer sick leave plus a cash buffer you can actually sustain
- Post-rate-hike (Sep 2026): high-yield savings now earn 3%+ so a bigger emergency fund for a longer deferment now partially pays for itself
Table of Contents
What Is the Deferment Period in DI Insurance?
The deferment period – also called the waiting period or deferred period – is how long you must remain unable to work before your disability income insurance starts paying out. Think of it as an excess on a car insurance policy: you absorb the first portion of loss yourself, and the insurer steps in after that.
If you have a 90-day deferment period and you suffer a slipped disc in January that keeps you off work, your first payout would only arrive in April. For those three months, you rely entirely on employer sick leave, personal savings, or annual leave.
This is one of the most consequential decisions you make when buying DI coverage. Get it wrong and you either overpay for coverage you do not need, or find yourself financially exposed during a period you expected to be protected.
Deferment Period Options in Singapore
Singapore major disability income insurers – NTUC Income, AIA, Prudential, Great Eastern, Manulife, and Singlife – typically offer deferment periods of 30, 60, 90, or 180 days. A small number of plans offer a one-year deferment for significant premium savings.
| Deferment Period | Also Called | When Payout Starts | Best For |
|---|---|---|---|
| 30 days | 1-month deferment | Month 2 of disability | Minimal savings; high disability risk jobs |
| 60 days | 2-month deferment | Month 3 of disability | Short employer sick leave; lean emergency fund |
| 90 days | 3-month deferment | Month 4 of disability | Most popular; matches typical sick leave plus modest buffer |
| 180 days | 6-month deferment | Month 7 of disability | Strong emergency fund; stable income; post-rate-hike sweet spot |
| 365 days | 1-year deferment | Month 13 of disability | High-net-worth; significant liquid assets |
Source: TKN research based on publicly available plan summaries, September 2026. Availability varies by insurer and plan.
Most Singaporeans gravitate toward the 90-day option. It lines up neatly with the combined effect of employer hospitalisation leave (typically up to 60 days per year for those on standard employment contracts) plus a few weeks of personal emergency savings.
How Much Does a Shorter Waiting Period Cost You?
The shorter your deferment period, the more the insurer is on the hook – and the higher your premium. Extending from a 30-day to a 90-day deferment typically cuts your annual premium by around 30%, based on indicative market data for standard occupation class profiles.
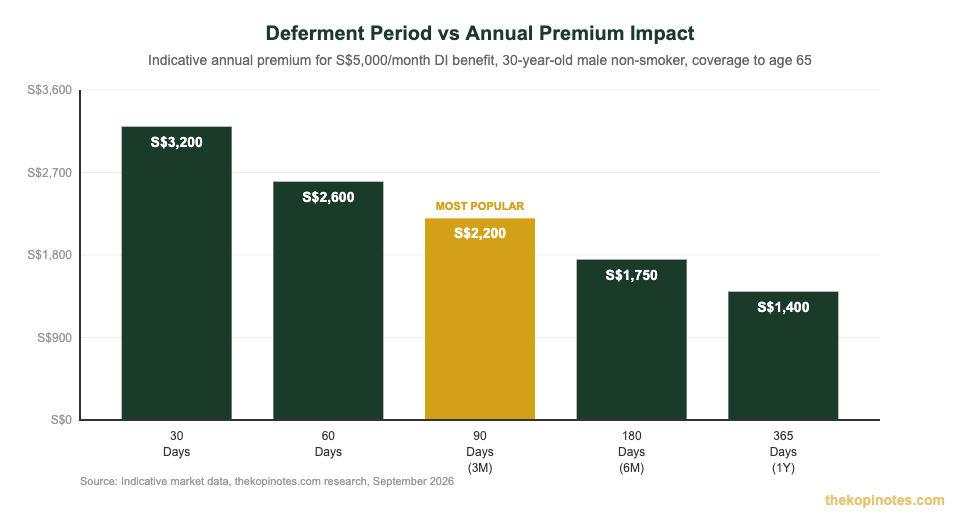
Indicative annual premiums for S$5,000/month benefit, 30-year-old male non-smoker, coverage to age 65. Source: TKN research, September 2026.
The numbers above are indicative – your actual premium will depend on your age, gender, occupation class, health history, and the specific insurer you choose. However, the directional relationship holds across all plans: each time you extend the waiting period, you reduce how often the insurer needs to pay in the early weeks of a disability, which translates directly into a lower annual cost for you.
Here is what the premium savings look like in dollar terms over a 30-year policy horizon:
| Deferment | Est. Annual Premium | Savings vs 30-Day | 30-Year Total Savings |
|---|---|---|---|
| 30 days | S$3,200 | Base | Base |
| 60 days | S$2,600 | S$600/year | S$18,000 |
| 90 days | S$2,200 | S$1,000/year | S$30,000 |
| 180 days | S$1,750 | S$1,450/year | S$43,500 |
Source: Indicative estimates, TKN research, September 2026. Premiums for S$5,000/month benefit, 30-year-old male non-smoker.
A 90-day deferment saves you roughly S$30,000 in premiums over 30 years compared to a 30-day option – money that could sit in a high-yield savings account or be invested instead. The trade-off is that you need to self-fund the first three months of any disability. That is the core decision.
The Post-Rate-Hike Calculation (Sep 2026)
Here is where the September 2026 Federal Reserve rate hike changes the maths for Singapore savers. With local high-yield savings accounts – including MariBank and Trust Bank – now paying around 3% per annum, the emergency fund you need to bridge a longer deferment period is no longer dead money. It is working for you.
Consider this scenario. You choose a 180-day deferment instead of a 90-day one. You need S$30,000 in liquid savings to cover six months of S$5,000 income replacement. At 3% interest, that S$30,000 earns S$900 per year. Your net premium after that interest income is just S$850 per year – compared to S$2,200 at 90 days.
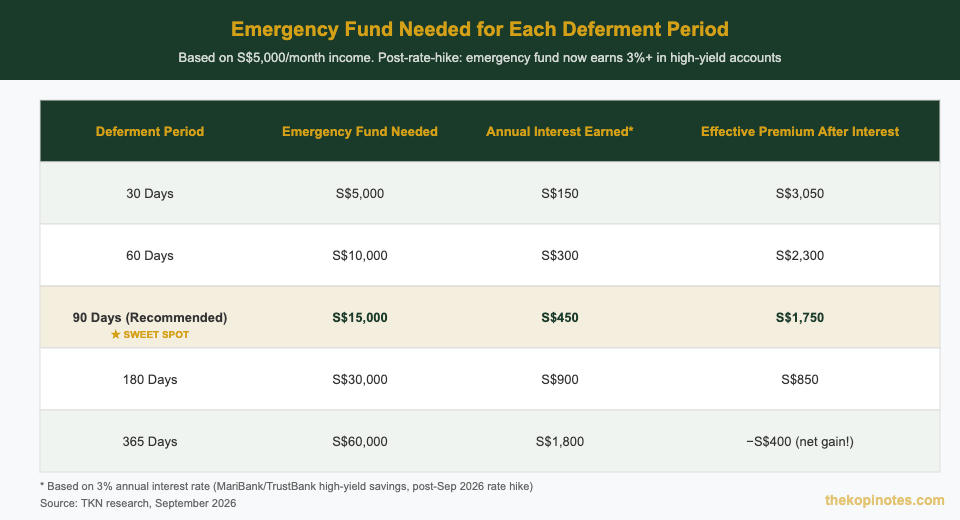
Emergency fund analysis assumes S$5,000/month income, 3% savings rate post-rate-hike. Source: TKN research, September 2026.
That said, this only makes sense if you can genuinely sustain the emergency fund. The S$30,000 buffer for a 180-day deferment must be liquid and separate from your investment accounts. It cannot be locked in T-bills or a fixed deposit you cannot access in a hurry. If you want to build that buffer while growing your wealth, platforms like Endowus let you invest in liquid money-market funds that can be redeemed quickly while still earning a competitive yield. Use our retirement planning calculator to see how your income protection fits your overall financial picture.
Factor In Your Employer Sick Leave First
Before picking your deferment period, map out what your employer already covers. Under the Employment Act, most Singapore employees are entitled to at least 14 days of paid outpatient sick leave and up to 60 days of paid hospitalisation leave per year (combined). Some employers offer more.
Your DI insurance only needs to kick in after your sick leave runs out. If you have 60 days of hospitalisation leave, a 30-day deferment period on your DI plan is essentially wasted overlap – you are paying for coverage during a period your employer already covers.
| Employment Type | Typical Sick Leave | Recommended Minimum Deferment |
|---|---|---|
| Salaried employee (standard) | 14 days outpatient + 60 days hospital | 60 or 90 days |
| Salaried employee (generous) | 60+ days combined | 90 or 180 days |
| Self-employed / freelance | None | 30 days (if lean savings) or 60 days |
| Business owner | Depends on arrangement | 60 or 90 days depending on reserves |
Source: Employment Act (Singapore), MOM guidelines. Sick leave entitlements depend on years of service and employment contract terms. September 2026.
For most salaried employees, a 90-day deferment is the sweet spot. It covers the gap after your sick leave and a modest personal buffer – without requiring you to hold a massive emergency fund.
Self-employed individuals face a different calculation. You do not have employer sick leave to fall back on. A 30 or 60-day deferment is almost always more appropriate. Yes, it costs more in premiums. But the consequence of a 90-day gap with no employer leave and a thin savings cushion is far more damaging. For a complete overview of how DI insurance works with your overall protection stack, read our disability income insurance complete guide.
Which Deferment Period Is Right for You?
Use this quick framework. Answer three questions, and your deferment period becomes obvious.
Question 1: How many days of paid sick leave does your employer provide?
Add up your outpatient and hospitalisation leave. This is your free buffer. You do not need DI coverage to overlap with it.
Question 2: How many months of expenses can you sustain from liquid savings alone?
Count only cash, savings accounts, and instant-access investments. Exclude CPF savings and illiquid assets.
Question 3: Are you salaried or self-employed?
Salaried workers can lean toward longer deferments because employer leave provides a natural cushion. Self-employed individuals should default to shorter deferments.
Once you have answered those three questions, the decision looks like this:
- Employer leave under 30 days AND liquid savings under 1 month income: Choose 30-day deferment
- Employer leave 30 to 60 days AND liquid savings 1 to 2 months: Choose 60 or 90-day deferment
- Employer leave 60+ days AND liquid savings 3+ months: Choose 90 or 180-day deferment
- Self-employed with thin savings: Choose 30 or 60-day deferment regardless
If you are building passive income streams alongside your career, it may also be worth factoring in any passive income from Singapore REITs or dividends that could partially cover expenses during a disability. That could justify a longer deferment period even with a moderate emergency fund.
Frequently Asked Questions
”Can
”What
”How
Build Your Financial Buffer
Choosing a longer deferment period requires a strong liquid emergency fund. If you want your buffer to grow while staying accessible, compare cash management platforms and referral bonuses on The Kopi Notes referral pages.
Not financial advice. Always compare plans and consult a licensed financial adviser before making insurance decisions.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.