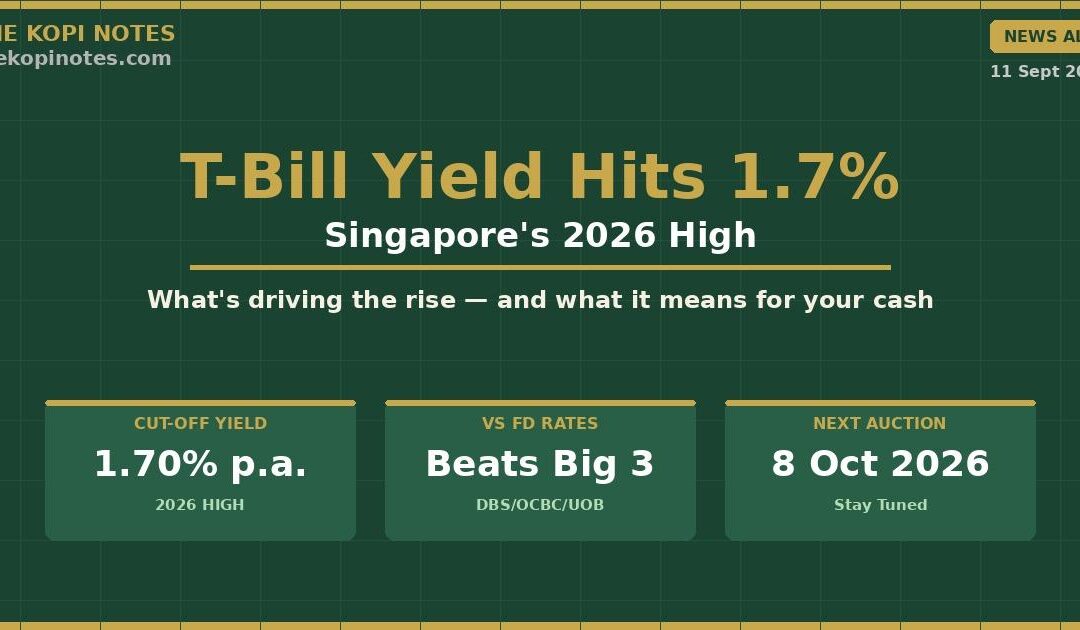
Singapore’s 6-month Treasury bill (T-bill) cut-off yield climbed to 1.70% per annum at the latest auction on 10 September 2026 — the highest rate recorded so far in 2026 for the 6-month tenor. The auction, for bond code BS26118E, drew strong demand with a total issue size of S$8.4 billion, and the notes will settle on 15 September 2026.
For Singaporean retail investors who rely on T-bills as a safe, short-term savings instrument, this uptick brings renewed interest — especially when compared against bank fixed deposits, Singapore Savings Bonds (SSB), and CPF interest rates.
What Is the BS26118E T-Bill?
The BS26118E is a 6-month Singapore Government Securities (SGS) T-bill — a zero-coupon instrument backed by the Singapore government. Investors buy T-bills at a discount and receive the face value (S$1,000 per unit) at maturity.
- Bond Code: BS26118E
- Tenor: 6 months
- Cut-Off Yield: 1.70% per annum
- Auction Date: 10 September 2026
- Settlement Date: 15 September 2026
- Issue Size: S$8.4 billion
How Does 1.70% Compare to Fixed Deposits?
The 1.70% T-bill yield beats most bank fixed deposit rates for equivalent tenors:
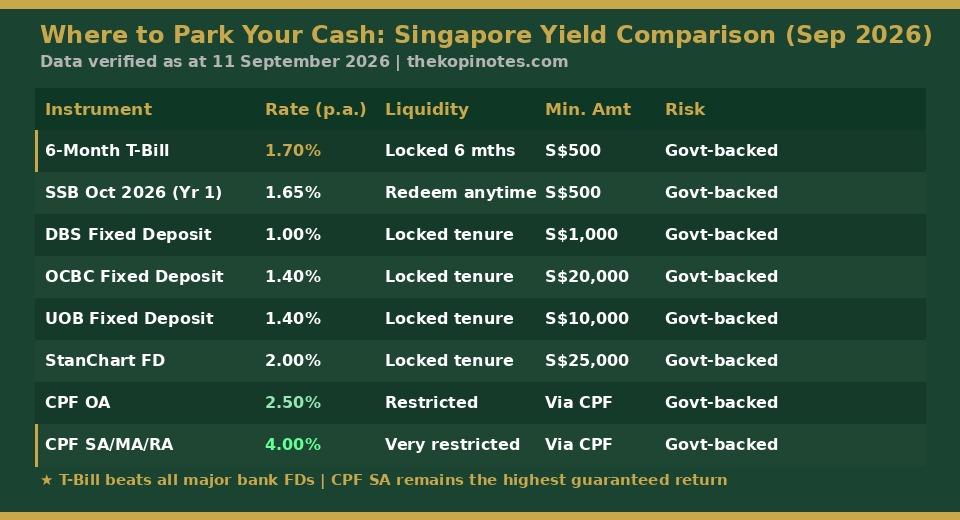
- DBS Bank FD (6M): ~1.00% p.a.
- OCBC Bank FD (6M): ~1.40% p.a.
- UOB Bank FD (6M): ~1.40% p.a.
- Standard Chartered FD (6M): ~2.00% p.a.
- 6-Month T-Bill (BS26118E): 1.70% p.a.
The T-bill outpaces DBS, OCBC, and UOB while falling just below Standard Chartered’s promotional 2.00% rate. For investors who value government backing and liquidity, the T-bill at 1.70% is a compelling option.
T-Bill vs Singapore Savings Bonds (SSB) — October 2026
The October 2026 SSB offers Year 1 return of 1.65% p.a., stepping up to a 10-year average of 2.32% p.a. if held to full maturity.
- T-bill (BS26118E): 1.70% p.a. — locked in for exactly 6 months
- SSB (Oct 2026, Year 1): 1.65% p.a. — fully flexible, redeemable anytime with no penalty
The T-bill wins on raw yield for the 6-month period, but SSBs can be redeemed in any calendar month without forfeiting interest. If liquidity matters, SSB at 1.65% is only marginally lower.
T-Bill vs CPF Interest Rates
CPF remains the benchmark for risk-free savings in Singapore:
- CPF Ordinary Account (OA): 2.5% p.a.
- CPF Special / MediSave / Retirement Account (SA/MA/RA): 4.0% p.a.
- 6-Month T-Bill (BS26118E): 1.70% p.a.
At 1.70%, the T-bill does not beat CPF rates. T-bills serve a different purpose: accessible cash savings outside of CPF that can be deployed flexibly. For long-term capital, CPF — especially the SA at 4% — remains hard to top.
Why Is the T-Bill Yield Rising?
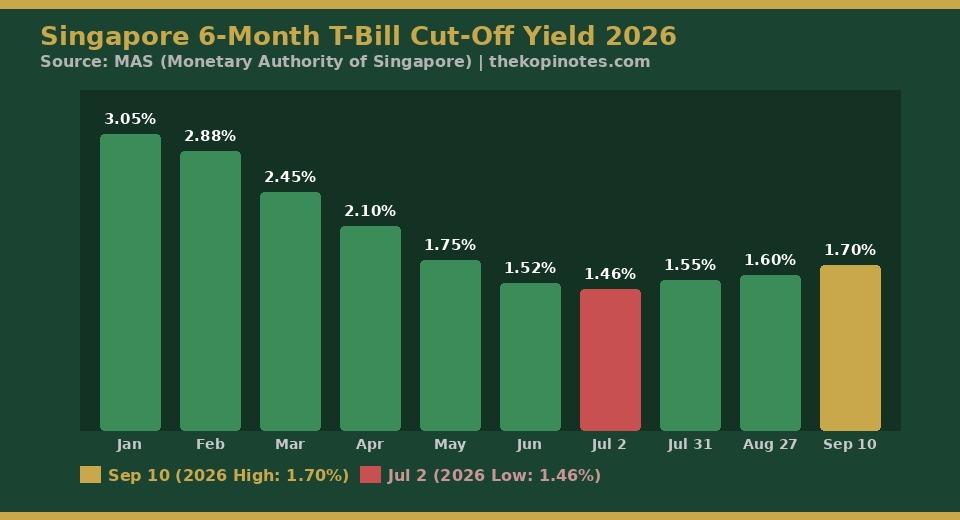
The 1.70% yield for BS26118E marks the 2026 high for the 6-month tenor, up from levels that hovered in the 1.40%–1.60% range earlier in the year. Singapore’s T-bill yields track global interest rate conditions, particularly US Federal Reserve policy, as MAS manages monetary policy through the Singapore dollar exchange rate rather than interest rates.
How to Apply for Singapore T-Bills
Retail investors can apply via:
- ATM (DBS/POSB, OCBC, UOB) — cash or SRS funds
- Internet banking — via DBS, OCBC, or UOB online portals
- CPF Investment Scheme (CPFIS) — using OA funds (note: CPF OA earns 2.5%, making this less attractive at current yields)
Should You Apply for the Next T-Bill?
- Apply if: You have idle cash earning less than 1.70% and don’t need it for 6 months.
- Consider SSB instead if: Liquidity matters — SSBs offer 1.65% Year 1 with monthly redemption, no penalty.
- Skip if: Your CPF SA/MA is not maxed — 4.0% p.a. risk-free beats everything else.
- Skip if: You need the money within 6 months — selling T-bills on SGX before maturity may reduce your effective yield.
Bottom Line
The BS26118E T-bill at 1.70% p.a. is the best 6-month T-bill yield Singapore has seen in 2026, comfortably ahead of most bank FDs and slightly above the SSB Year 1 rate. While it doesn’t beat CPF (which remains the gold standard for safe returns), it’s a solid option for surplus cash you can park safely for half a year. Watch the MAS website and SGX for the next 6-month T-bill auction if you missed this round.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. T-bill yields are subject to change at each auction. Always verify rates with official sources (MAS, SGX) before investing.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.