Keppel DC REIT Share Price 2026: Dividend Sustainability, AI Data Centre Demand & Singapore Supply Pipeline
Singapore’s largest data centre REIT — DPU outlook, AI tailwinds, and key risk factors
Keppel DC REIT (SGX: AJBU) is Singapore’s largest listed data centre REIT, owning 23 data centres across 9 countries with a portfolio valued at approximately SGD 3.7 billion. Listed on the SGX Mainboard since December 2014, it distributes quarterly DPU at a trailing yield of approximately 4.5–5.5% at current prices. With AI infrastructure spending accelerating globally and Singapore’s rate cuts reducing borrowing costs, Keppel DC REIT’s dividend sustainability is strengthening heading into 2H2026.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
For Singapore investors seeking passive income in Singapore, Keppel DC REIT is unique: it’s the only large-scale pure-play data centre S-REIT on SGX, with tenants that include hyperscalers, cloud providers, and enterprise corporations operating on long-term, inflation-linked leases. This deep dive covers the 2026 share price trajectory, DPU history, AI demand tailwinds, Singapore’s supply pipeline, and the risks every investor must understand before buying.
What Is Keppel DC REIT?
Keppel DC REIT (ticker: AJBU) was the first data centre REIT listed in Asia, debuting on SGX Mainboard on 12 December 2014. Its sponsor, Keppel Corporation, is one of Singapore’s largest conglomerates with deep expertise in infrastructure asset management. The REIT specialises in mission-critical data centre facilities — buildings housing servers, networking equipment, and cooling systems for cloud providers, enterprises, and governments. Unlike office or retail REITs, data centres typically sign 5–15 year leases with built-in rental escalations, making income streams highly predictable.
| Metric | Details |
|---|---|
| SGX Ticker | AJBU |
| Properties | 23 data centres across 9 countries |
| Portfolio Valuation | ~SGD 3.7 billion (2H2026 est.) |
| Distribution Frequency | Quarterly |
| Gearing Ratio | ~37% |
| WALE | ~7.4 years |
| Occupancy Rate | ~97% |
Source: Keppel DC REIT SGX filings & investor presentations, Q3 2026. Figures are approximate.
Share Price Performance in 2026
Keppel DC REIT’s share price has been among the S-REIT sector’s standout performers in 2026, propelled by three converging catalysts: Singapore’s rate cutting cycle, the global surge in AI infrastructure spending, and proactive portfolio management by its manager. After bottoming in the SGD 1.70–1.80 range during the 2023–2024 rate peak, recovery began in 2025 as rate cut expectations built. By mid-2026, with actual cuts materialising and AI data centre leasing activity at record highs, the share price had recovered substantially. Investors tracking the best S-REITs in Singapore 2026 consistently spot KDC in watchlists for growth-oriented income investors.
DPU History & Dividend Sustainability
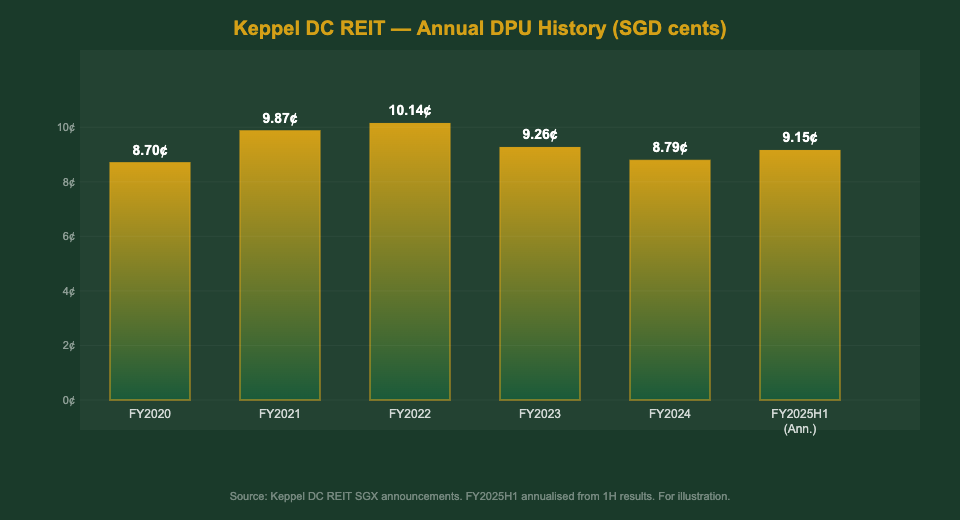
The core question for any income investor: can Keppel DC REIT sustain — and grow — its dividend? Here’s the full DPU track record:
| Financial Year | DPU (SGD cents) | YoY Change | Key Driver |
|---|---|---|---|
| FY2020 | 8.70¢ | — | COVID accelerated cloud adoption |
| FY2021 | 9.87¢ | +13.4% | Acquisitions accretive; strong occupancy |
| FY2022 | 10.14¢ | +2.7% | All-time high DPU; rates still low |
| FY2023 | 9.26¢ | −8.7% | Rate hikes hit financing costs; China assets under review |
| FY2024 | 8.79¢ | −5.1% | Rates peaked; hedging costs elevated |
| 1H2025 (annualised) | ~9.15¢ | +4.1% | Rate cuts begin; new leases at higher rents |
Source: Keppel DC REIT SGX announcements. 1H2025 annualised from H1 results. Educational illustration only.
Three structural factors support DPU sustainability in 2026: First, rate cuts are reducing financing costs — with Singapore rates declining, KDC’s cost of debt that peaked above 4.0% is trending back toward 3.0–3.5% as hedges roll off, with each 25bps reduction adding approximately 0.1–0.2¢ DPU annually. Second, legacy leases signed at pre-2020 rents are expiring and renewing at meaningfully higher market rates, particularly in Singapore and Europe, delivering positive rental reversion without capex. Third, AI demand is pushing utilisation toward 100% in Singapore properties and supporting premium pricing for upgraded, high power-density spaces.
Singapore Data Centre Supply Pipeline
Singapore’s government imposed a moratorium on new data centre projects from 2019 to 2022, creating a supply crunch that dramatically benefited existing operators like Keppel DC REIT. From 2022, Singapore restarted approvals under a Green Lane framework requiring operators to meet strict power efficiency (PUE ≤ 1.3) and renewable energy commitments. Supply growth is measured and deliberate — structurally supportive for incumbents with existing, approved facilities.
Key supply dynamics: Singapore properties operate at 97-98% occupancy — essentially full. New data centre approvals are constrained by regulatory requirements and power grid capacity. KDC is focused on expanding existing Singapore campuses (adding power capacity) rather than greenfield builds. Colocation rental rates in Singapore have increased 15–25% over three years with further upside as AI drives demand for low-latency infrastructure.
AI Demand: The 2026 Tailwind
Artificial intelligence has fundamentally altered the data centre investment thesis. AI training and inference workloads grow exponentially — unlike traditional enterprise IT — and require specialised, power-dense infrastructure. For Keppel DC REIT, this means hyperscalers (AWS, Azure, Google Cloud) aggressively expanding in Singapore as a Southeast Asian hub, directly benefiting KDC’s existing tenant base. AI servers require significantly more power per rack than traditional servers, and KDC is upgrading facilities to handle higher power density at premium rents. Multi-year AI infrastructure commitments from tenants further reinforce KDC’s already-long WALE and reduce vacancy risk.
Use TKN’s Singapore retirement calculator to model how S-REIT dividend income compounds toward your financial independence goals over 10–30 year horizons.
Portfolio by Geography
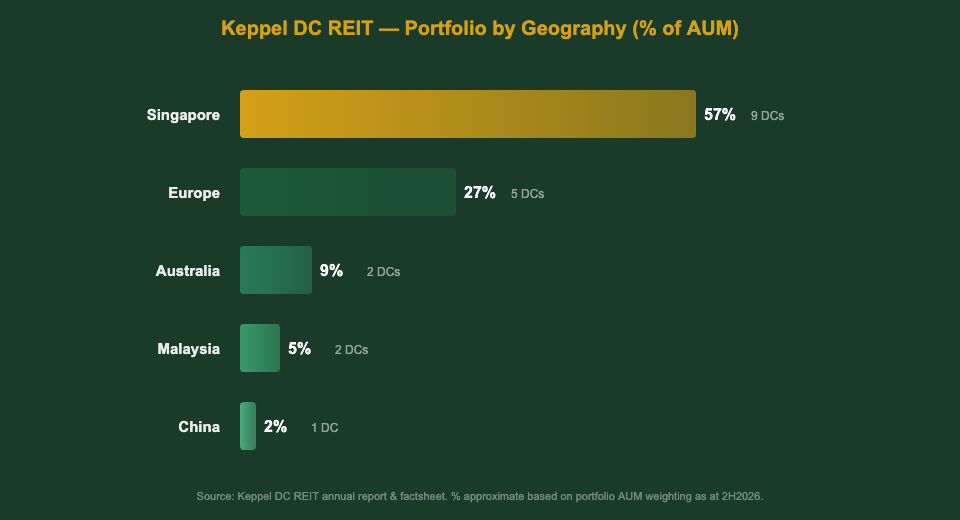
Singapore accounts for ~57% of Keppel DC REIT’s AUM — 9 data centres that represent some of Asia’s most premium data centre assets. Europe (~27%, 5 DCs across Germany, Netherlands, UK, Italy, Ireland) adds diversification across mature, high-income markets. Australia (2 DCs, ~9%) and Malaysia (2 DCs, ~5%) round out the APAC exposure. The China assets (~2%) represent the portfolio’s main near-term uncertainty.
Key Risk Factors
Keppel DC REIT investors should monitor: (1) Interest rate reversals — despite cuts, KDC carries significant debt and a rate reversal would compress valuations; approximately 60–65% of debt is hedged providing near-term protection. (2) China asset overhang — Chinese data centre assets face lower utilisation and regulatory complexity, and any negative developments could weigh on sentiment. (3) FX risk — EUR and AUD revenue introduces currency exposure; SGD appreciation versus EUR reduces translated income. (4) Tenant concentration — the top 3 tenants likely represent 30–40% of gross revenue, making any major tenant departure material. (5) Technological obsolescence — legacy facilities must continually upgrade to handle AI-era power density requirements.
For a risk-free income comparison, see TKN’s Singapore T-bills 2026 guide.
Peer Comparison
| Metric | Keppel DC REIT (AJBU) | Mapletree Industrial Trust (ME8U) | Digital Core REIT (DCRU) |
|---|---|---|---|
| Asset Type | Pure-play DCs | Industrial + DCs | Pure-play DCs (US) |
| Geography | SG, Europe, APAC | SG, Japan, US | US (primarily) |
| Approx. Yield | 4.5–5.5% | 5.0–6.0% | 5.5–7.0% |
| Gearing | ~37% | ~34% | ~35% |
| WALE | ~7.4 yrs | ~3.2 yrs | ~5.0 yrs |
| AI Exposure | High (SG DCs, hyperscalers) | Moderate (US DCs) | High (US hyperscalers) |
Source: SGX filings & company presentations, 2H2026. Yields are approximate trailing figures at prevailing prices.
Buy, Hold, or Wait?
For income investors building a passive income portfolio in Singapore, Keppel DC REIT presents a compelling but increasingly well-priced proposition in 2H2026. The bull case: rate cuts continue, AI demand drives rental upside, Singapore supply stays constrained, and DPU recovers toward 10¢+ highs — at current prices, this implies a 5.5–6% yield on cost. The base case: DPU stabilises at 9.0–9.5¢, share price trades in a range as income investors collect quarterly distributions. The bear case: China assets surprise negatively, or rates reverse — a 15–20% price correction would create a materially better entry. For investors wanting managed S-REIT exposure including KDC, Syfe (SRPRFFFCD) and Endowus (2V343) both offer S-REIT portfolios.
Frequently Asked Questions: Keppel DC REIT 2026
What is the current Keppel DC REIT share price in 2026?
What is Keppel DC REIT's DPU and dividend yield in 2026?
Is Keppel DC REIT a good buy in 2026?
How many data centres does Keppel DC REIT own?
How does AI demand benefit Keppel DC REIT investors?
What is Keppel DC REIT's gearing ratio and is it safe?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.