If you or a family member were born before 1 January 1958, your CPF retirement payouts almost certainly come through the Retirement Sum Scheme (RSS) — not CPF LIFE. The two schemes work very differently: RSS draws down your Retirement Account (RA) balance month by month and stops when it runs out, while CPF LIFE is a lifelong annuity that never ends.
Understanding how RSS works, how long it lasts, and whether switching to CPF LIFE makes sense can help you — or your parents — plan with greater certainty. This article covers the 2026 rules, with data sourced from CPF Board (cpf.gov.sg) and verified as at October 2026.
For a full overview of all CPF retirement sums, see the CPF Retirement Sum Singapore guide — the pillar article for this topic.
TL;DR — Key Facts at a Glance
| Who is on RSS | CPF members born before 1 January 1958 (and some others — see below) |
| How it pays | Monthly draw-down from your Retirement Account (RA) balance |
| Interest rate | 4% p.a. floor on RA, guaranteed until 31 December 2026 |
| Payout duration | Calculated to last ~20-25 years from payout start (typically to age 85-90) |
| Minimum payout | S$350/month (as at June 2023) |
| Key risk | Payouts stop when RA is depleted — no lifelong income guarantee |
| Can you switch? | RSS to CPF LIFE allowed from age 65 to before age 80. Switch is one-way. |
What Is the Retirement Sum Scheme (RSS)?
The Retirement Sum Scheme is CPF’s earlier retirement income model, predating CPF LIFE. Under RSS, your Retirement Account (RA) balance is drawn down monthly as a fixed payout. As long as there is money in the RA, you receive your monthly payout; when the balance reaches zero, payouts stop.
CPF LIFE (Lifelong Income For the Elderly) replaced RSS as the default scheme for most Singaporeans from 2009 onward. The core difference is longevity protection: CPF LIFE pays for as long as you live, regardless of how long the pool lasts. RSS has no such guarantee — it is a draw-down, not an annuity.
On death, any remaining RA balance under RSS is paid to your nominated CPF beneficiaries, or distributed under the Intestate Succession Act if no nomination is made. Under CPF LIFE, the residual premium balance goes to nominees, but this amount shrinks as you age.
Who Is on the Retirement Sum Scheme?
Three groups of CPF members receive RSS payouts instead of CPF LIFE payouts:
- Born before 1 January 1958. Members in this cohort — now aged 68 and above in 2026 — were not automatically enrolled in CPF LIFE. They are on RSS by default unless they chose to opt in to CPF LIFE.
- Born in 1958 or later, but with less than S$60,000 in RA savings when payouts begin. These members do not meet CPF LIFE’s auto-inclusion threshold. They may still voluntarily join CPF LIFE.
- Non-Singapore Citizens and non-Permanent Residents. CPF members who are not SC or PR receive payouts from RSS based on their RA balance.
| Criterion | RSS (default) | CPF LIFE (auto-included) |
|---|---|---|
| Birth year | Before 1 January 1958 | 1 January 1958 or later |
| RA balance at payout start | Any amount | At least S$60,000 |
| Citizenship | SC, PR, or non-SC/non-PR | Singapore Citizen or PR only |
Source: CPF Board (cpf.gov.sg), as at October 2026.
How RSS Payouts Are Calculated
Your monthly RSS payout is determined by three factors:
- Your RA balance when payouts start. The more you have saved in your Retirement Account, the higher your monthly payout. You can check your balance via my.cpf.gov.sg.
- The interest rate. Your RA earns a floor rate of 4% per annum, guaranteed until 31 December 2026. Members aged 55 and above earn additional interest: an extra 2% p.a. on the first S$30,000 of combined CPF savings, and an extra 1% p.a. on the next S$30,000. This extra interest slows the draw-down and extends how long payouts last.
- When you start payouts. Payouts can begin any time after age 65. If you have not chosen a start date, they begin automatically at age 70. Deferring to a later age may increase the monthly payout or extend the payout period.
CPF uses these inputs to spread your RA balance over an estimated payout period, typically to age 90. The minimum payout floor is S$350 per month (as at June 2023).
How Long Do RSS Payouts Last?
CPF calculates RSS payouts to last approximately 20-25 years from your payout eligibility age. A member who starts at 65 can generally expect payouts to run to roughly age 85-90, assuming the 4% floor rate continues.
The extra interest earned on the first S$60,000 of combined CPF savings acts as a buffer, stretching payouts closer to age 90 rather than 85. The exact duration depends on your individual RA balance and the interest rates that apply during the payout period.
The critical caveat: if you live past age 90 — or even past 85, depending on your balance — payouts may end while you are still alive. This is the longevity risk that CPF LIFE was designed to eliminate. Singapore women have an average life expectancy of approximately 86 years, but many individuals live well into their 90s.
RSS vs CPF LIFE: A Side-by-Side Comparison
For a deeper look, see our dedicated guide: Retirement Sum Scheme vs CPF LIFE — What’s the Difference?
| Feature | RSS | CPF LIFE (Standard Plan) |
|---|---|---|
| Payout duration | Until RA depletes (~20-25 years) | For life, no matter how long you live |
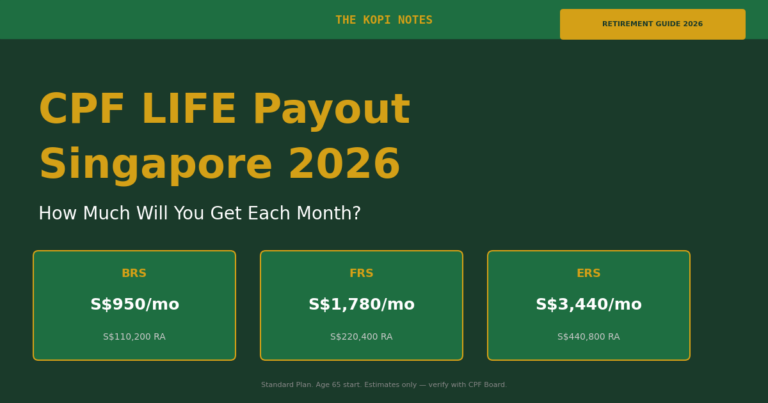
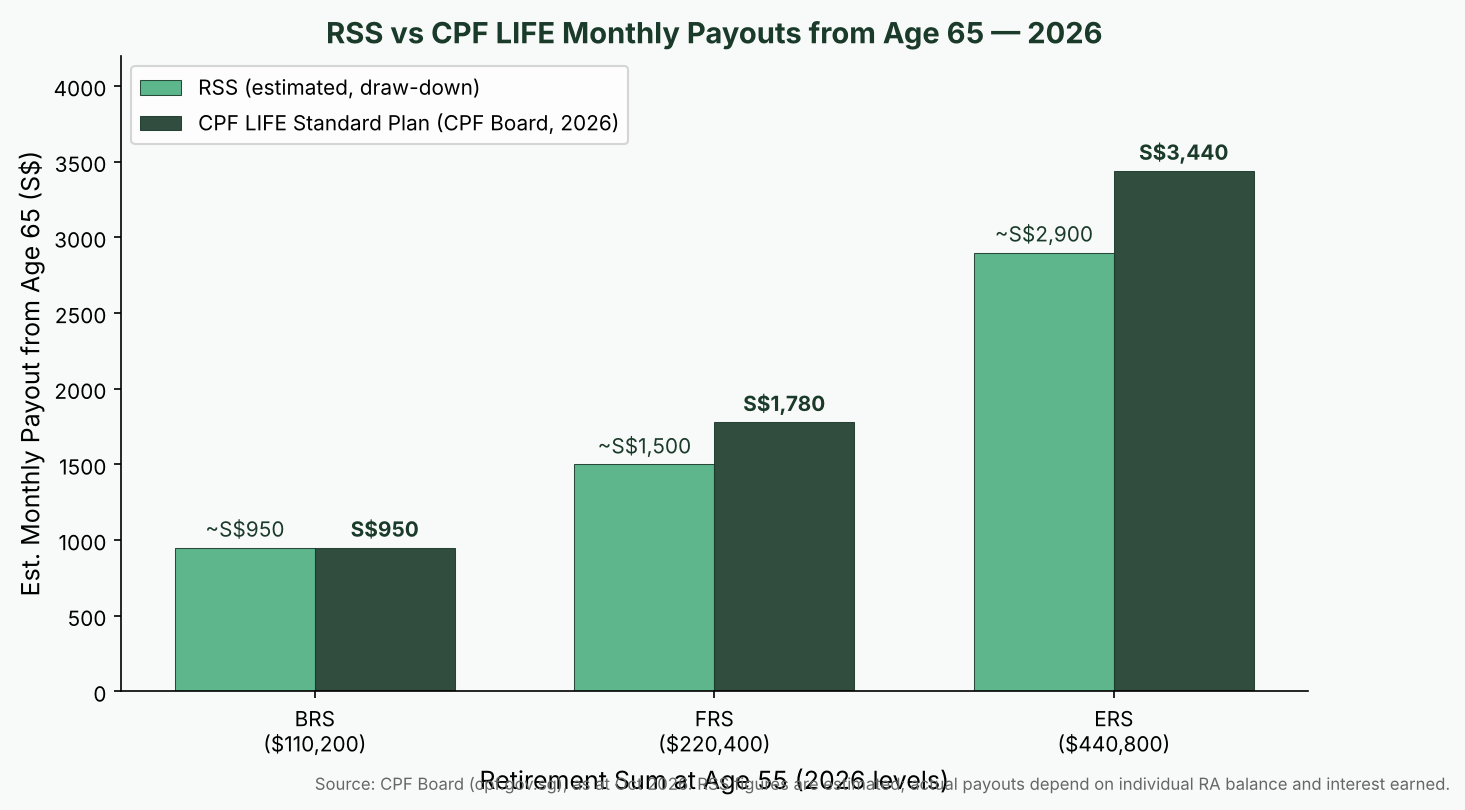
| Monthly payout at FRS (S$220,400 from age 65) | ~S$1,400-1,600/month (estimated) | ~S$1,780/month (CPF Board, 2026) |
| RA interest treatment | Earned on RA; slows draw-down | Pooled into Lifelong Income Fund |
| RA balance on death | Full remaining RA balance to nominees | Residual premium (decreases with age) to nominees |
| Minimum payout | S$350/month (Jun 2023) | Depends on plan and balance |
| Longevity protection | None — payouts stop when RA depletes | Yes — payouts continue for life |
| Switching | RSS to CPF LIFE allowed (age 65 to before 80) | CPF LIFE to RSS: not allowed |
CPF LIFE Standard Plan figures: CPF Board (cpf.gov.sg), as at September 2026. RSS monthly payout at FRS is an estimate; actual payouts depend on your RA balance and interest earned.
Worked SGD Example: Madam Wong, Born 1953
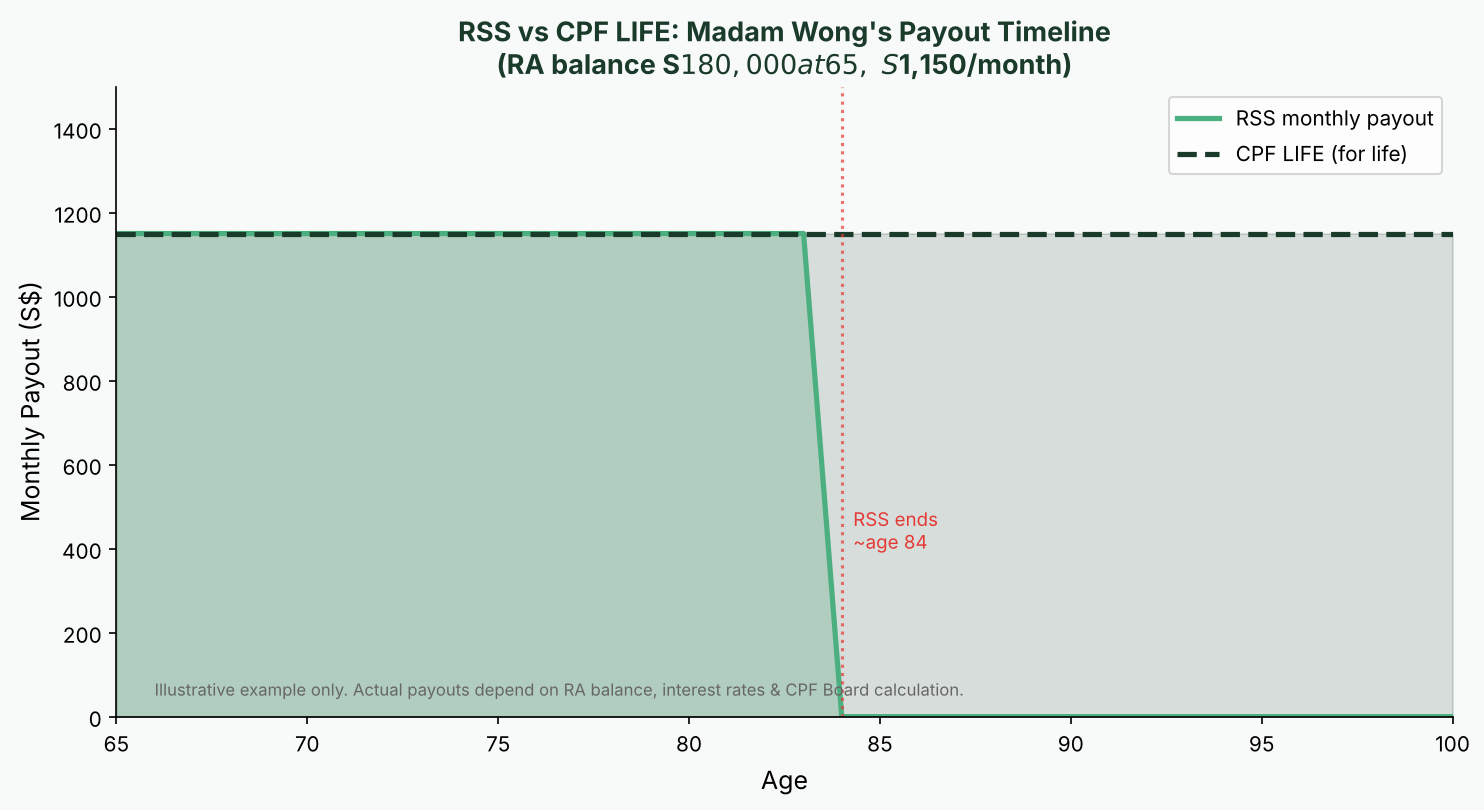
Madam Wong was born in October 1953 and is now 72 years old. She started RSS payouts at age 65 in October 2018. At payout start, her Retirement Account balance was approximately S$180,000 — close to the Full Retirement Sum at the time. Based on the 4% interest floor and a payout period calculated to age 90, CPF set her monthly payout at approximately S$1,150 per month.
After eight years of payouts (about 96 payments), her remaining RA balance is approximately S$75,000 — the ongoing 4% interest earned on the RA has partially offset the draw-down.
Scenario A — Stay on RSS: Payouts of approximately S$1,150/month continue until around age 88-90, when the RA is expected to deplete. After that, no further CPF retirement income.
Scenario B — Switch to CPF LIFE Standard before age 80: Her remaining balance of approximately S$75,000 becomes her CPF LIFE premium. Estimated monthly payout: approximately S$600-700/month for life. Lower than current RSS — but she cannot outlive it, even if she reaches 100.
The trade-off is real: staying on RSS gives Madam Wong more income now; switching locks in a lower but lifelong income floor. The right choice depends on her health, family longevity, and other income sources. This example is illustrative only — actual payouts depend on CPF’s internal calculations and the interest rates that apply.
Can You Switch from RSS to CPF LIFE?
Yes — and for many members currently on RSS, it is worth considering. You can switch from RSS to CPF LIFE at any time from age 65 up to one month before your 80th birthday. The switch is one-way: once on CPF LIFE, you cannot return to RSS.
To switch, log in to my.cpf.gov.sg, navigate to the CPF LIFE section, and select “Join CPF LIFE”. You will choose a plan: Standard (highest monthly payout), Basic (slightly lower payout, higher residual for beneficiaries), or Escalating (starts lower, increases 2% per year — better inflation protection over a long retirement).
If you switch after RSS payouts have already started, your remaining RA balance becomes your CPF LIFE premium. The resulting monthly payout will be lower than your current RSS amount, since the RA balance has already been partially drawn down — but it will continue for life. Members in good health with a long family history of longevity are most likely to benefit from switching.
Use the Retirement Planning Calculator to estimate your projected income under both scenarios, and compare it to your expected expenses. For the full picture on how CPF retirement sums work, revisit the CPF Retirement Sum Singapore guide. You may also find the Enhanced Retirement Sum guide useful if you are exploring how to top up your RA before payouts begin.
No financial advice: This article describes how the Retirement Sum Scheme operates under Singapore CPF rules as at October 2026. It is for educational and informational purposes only and does not constitute financial, tax, or legal advice. Your individual CPF payouts depend on your own RA balance, payout start age, CPF interest rates, and personal circumstances. The worked example above is illustrative only. Consult a MAS-licensed financial adviser or contact CPF Board directly at my.cpf.gov.sg for personalised guidance.
Frequently Asked Questions
What is the Retirement Sum Scheme (RSS) in Singapore?
The Retirement Sum Scheme is CPF’s earlier retirement income model for members born before 1 January 1958. It pays monthly amounts from your CPF Retirement Account (RA) balance until the funds are depleted — typically around age 85-90. It was the default payout scheme before CPF LIFE was introduced in 2009.
Who qualifies for the Retirement Sum Scheme?
Primarily CPF members born before 1 January 1958 — now aged 68 and above in 2026. Also: Singapore Citizens and Permanent Residents born in 1958 or later with less than S$60,000 in RA savings when payouts start, and non-SC/non-PR CPF members. Log in to my.cpf.gov.sg to confirm which scheme applies to you.
How much will I receive under RSS per month?
It depends on your RA balance and when you start payouts. The minimum is S$350/month (as at June 2023). A member with approximately S$180,000-S$220,400 in the RA at age 65 could expect roughly S$1,150-S$1,780/month at the start. Use CPF’s Payout Estimator at my.cpf.gov.sg for a personalised figure.
What happens when my RSS payouts stop?
When your Retirement Account balance reaches zero, RSS payouts end. You would then rely on other income — personal savings, investment returns, rental income, family support, or the Silver Support Scheme if you qualify. This longevity risk is the key disadvantage of RSS versus CPF LIFE, which pays for life regardless of how long you live.
Can I switch from RSS to CPF LIFE?
Yes. You can switch from RSS to CPF LIFE any time between age 65 and one month before your 80th birthday. The switch is permanent — you cannot return to RSS once you have joined CPF LIFE. Your remaining RA balance becomes your CPF LIFE premium, and your monthly payout is set based on that balance. Log in to my.cpf.gov.sg to apply.
Is RSS or CPF LIFE better for a Singapore retiree?
It depends. RSS typically pays a comparable monthly amount early on, and any remaining RA balance goes fully to your nominees on death — which matters for estate planning. CPF LIFE provides lifelong income, which is most valuable if you live longer than expected. Most financial planners favour CPF LIFE for longevity protection, but someone in poor health or with substantial other assets may prefer RSS for the higher short-term payout and larger estate return. This is a personal decision based on your health, family longevity history, and overall financial picture.
What happens to my RSS balance if I die?
Under RSS, your full remaining Retirement Account balance is paid to your nominated CPF beneficiaries, or distributed under the Intestate Succession Act if no nomination is in place. Under CPF LIFE, only the residual premium balance (which decreases as you age) goes to nominees. For members prioritising estate preservation, RSS can be more advantageous in this respect.
Is the RSS interest rate changing after December 2026?
The 4% floor rate on RA savings is guaranteed only until 31 December 2026. CPF Board reviews the rate annually. After that date, the rate could change depending on prevailing market conditions. Always check cpf.gov.sg for the latest interest rate announcements.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.