MariBank Loan Singapore (2026): Interest Rate, EIR, Eligibility & Honest Review
Updated October 2026 | Data verified against maribank.sg official website
The MariBank Instant Loan offers Singapore Citizens and PRs a fully digital personal loan with a flat rate starting from 1.28% p.a. (EIR from 1.92% p.a. for a 3-month tenor), loan amounts from S$100 to S$100,000, and disbursement within 10 seconds via the Mari Credit Card — making it one of the fastest, most affordable personal loan options available from a licensed digital bank in Singapore as at October 2026.
Not financial advice. All figures are for educational reference only. Data verified as at 10 October 2026 against maribank.sg official sources and MoneySmart. Rates are the lowest published and may vary based on your credit profile.
What Is the MariBank Instant Loan?
MariBank is Singapore’s digital bank backed by Sea Limited — the same group that operates Shopee and Garena. Licensed by the Monetary Authority of Singapore (MAS) as a digital full bank, MariBank launched retail lending under the product name MariBank Instant Loan (also referred to internally as the “Mari Credit Card Instant Loan”).
Unlike traditional personal loans where funds are disbursed to your bank account, the MariBank Instant Loan works uniquely: upon approval, MariBank issues you a Mari Credit Card with your approved loan amount preloaded as a credit limit. You can then draw down the funds via cash advance to your savings account within 10 seconds, or use the card directly for purchases.
This structure means your repayments are made as monthly credit card instalments — and if you miss a payment, the higher credit card interest rate (30.99% p.a. late interest) applies, not the loan rate. It’s critical to set up GIRO or manual monthly repayments before drawing down.
Singaporeans already familiar with MariBank through its MariBank savings and fixed deposit rates will find the loan experience equally seamless — fully app-based, with Singpass-verified identity and no physical branch visits required.
MariBank Loan Interest Rate & EIR (October 2026)
The published loan rate is from 1.28% p.a. flat rate, with an EIR (Effective Interest Rate) from 1.92% p.a. — the EIR is calculated on a 3-month loan tenor per MariBank’s official disclosures. For longer tenures, the EIR approaches approximately 2.3–2.5% p.a. (a standard formula for flat-rate loans).
The rate you actually receive is determined by your credit profile and income during the application process in the MariBank app. You’ll see your personalised rate before accepting — it is guaranteed once approved.
Key Rate Facts (Source: maribank.sg, October 2026)
| Detail | Figure |
|---|---|
| Advertised flat rate | From 1.28% p.a. |
| EIR (3-month loan) | From 1.92% p.a. |
| Example (S$10,000 / 12 months) | S$844/month · Total S$10,128 |
| Late payment interest | 30.99% p.a. on unpaid balance |
| Unpaid statement balance interest | 27.99% p.a. |
Source: maribank.sg official product page and help centre, October 2026. Rates are indicative lowest published rates.
The flat-to-EIR relationship is important: for a 12-month loan at 1.28% p.a. flat, the total interest on S$10,000 is just S$128 — paying you back S$10,128 over the year at S$844/month. Compare this with a credit card cash advance at 26–29% p.a. and the savings are significant.
Loan Amount & Tenure
MariBank’s Instant Loan has a notably low minimum loan amount of just S$100 — unusually flexible compared to most banks that require a minimum of S$1,000 or more. The maximum loan amount is S$100,000, subject to MariBank’s credit assessment.
Loan tenure runs from 3 to 60 months (3 months to 5 years), but your available tenor options are determined by MariBank during the application process based on your income, credit history, and overall profile. You won’t have full free choice of any tenor — only those MariBank approves for you.
For borrowers who need quick bridging funds under S$1,000 (e.g. for an unexpected expense or small renovation payment), MariBank is one of very few licensed lenders offering this at a transparent fixed rate. Compare this with a licensed moneylender’s higher rates or a credit card cash advance at 26%+ p.a.
MariBank Loan Eligibility Requirements
MariBank’s Instant Loan is available to Singapore Citizens and Permanent Residents only — foreigners are not eligible. The core eligibility criteria as at October 2026 are:
| Requirement | Details |
|---|---|
| Citizenship | Singapore Citizens and Permanent Residents only |
| Minimum age | 21 years old |
| Min. annual income (ages 21–55) | S$30,000 p.a. |
| Min. annual income (age 56+) | S$15,000 p.a. |
| Required accounts | Mari Savings Account + Mari Credit Card (opened on approval) |
Source: MoneySmart MariBank Instant Loan review, October 2026.
Note for lower-income applicants: If you earn under S$30,000 p.a. (ages 21–55), you may still receive a Mari Credit Card with a S$500 limit — but you won’t qualify for the Instant Loan. The S$15,000 threshold for those 56 and above reflects MAS regulations for senior borrowers.
MariBank also conducts a credit bureau check via CBS (Credit Bureau Singapore). If your credit score is poor or you have outstanding debts beyond MAS’s unsecured borrowing limits, your application will likely be declined or offered a reduced amount.
Fees & Charges
One of MariBank’s genuine competitive advantages is its lean fee structure. Here’s the full picture:
| Fee Type | Amount | Notes |
|---|---|---|
| Processing fee | S$0 | No upfront fees |
| Annual fee | S$0 | No annual card fee |
| Early repayment fee | S$100 or 3% of outstanding principal (whichever is higher) | Full settlement only — no partial repayments |
| Late payment interest | 30.99% p.a. | On unpaid minimum payment |
| Unpaid statement balance | 27.99% p.a. | Standard credit card rate if balance unpaid |
Source: MoneySmart MariBank Instant Loan review; maribank.sg, October 2026.
The early repayment fee is worth noting if you plan to pay off the loan ahead of schedule. For a S$20,000 loan where you’ve repaid half and want to clear the remaining S$10,000 early, the fee would be: max(S$100, 3% × S$10,000) = max(S$100, S$300) = S$300. Factor this in before assuming you can save on interest by prepaying.
Critically, partial repayments are not allowed — you can only settle the full outstanding principal. This is a meaningful restriction compared to traditional bank loans.
Monthly Repayment Guide (Verified Estimates)
The table below shows estimated monthly instalments at the lowest advertised flat rate of 1.28% p.a. The S$10,000 / 12-month figure of S$844 has been verified against MariBank’s official example. Your actual rate may be higher.
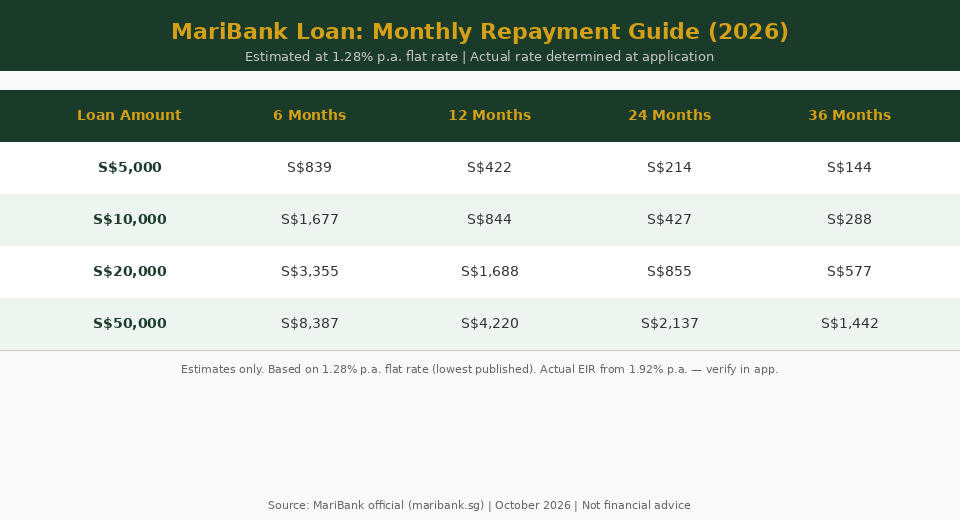
Figures based on 1.28% p.a. flat rate. Actual rate personalised. Source: MariBank official (maribank.sg), Oct 2026.
For context, a Singapore investor with S$10,000 in short-term cash earning 1.5% p.a. in a MariBank savings account would essentially break even if they borrow at 1.28% flat — the interest cost is offset by the savings rate. Of course, net of EIR (1.92%+) the loan still costs more than typical savings returns.
How to Apply for the MariBank Instant Loan
The entire application is done within the MariBank app — no paper forms, no branch visits. Here’s the step-by-step process:
- Download the MariBank app (iOS or Android) and create a Mari Savings Account if you don’t already have one.
- Open the app and navigate to the Instant Loan section under “Borrow” or “Credit”.
- Enter the loan amount and select your desired tenor — the app will show you what tenors you qualify for based on your profile.
- Verify via Singpass — MariBank uses MyInfo to pull your income, CPF contributions, and identity data automatically. No payslips to upload.
- Review your personalised rate — the app shows your exact interest rate, monthly instalment, and total cost before you accept. The rate is guaranteed once you proceed.
- Accept and receive funds within 10 seconds — a Mari Credit Card is issued simultaneously, and the funds are disbursed to your linked bank account.
- Set up autopay immediately after disbursement to avoid missing monthly repayments and triggering the 30.99% p.a. late interest.
For borrowers who are not yet MariBank customers, the good news is that opening a Mari Savings Account is part of the loan approval process — you don’t need to set it up beforehand. Use a MariBank referral code at sign-up to qualify for any current welcome bonus.
MariBank Loan vs Competitors (October 2026)
How does MariBank’s Instant Loan stack up against other digital bank and traditional bank personal loans in Singapore? The chart below compares EIR figures for a S$10,000 loan over 12 months at advertised lowest rates. Note that all EIRs depend on your profile and will vary.
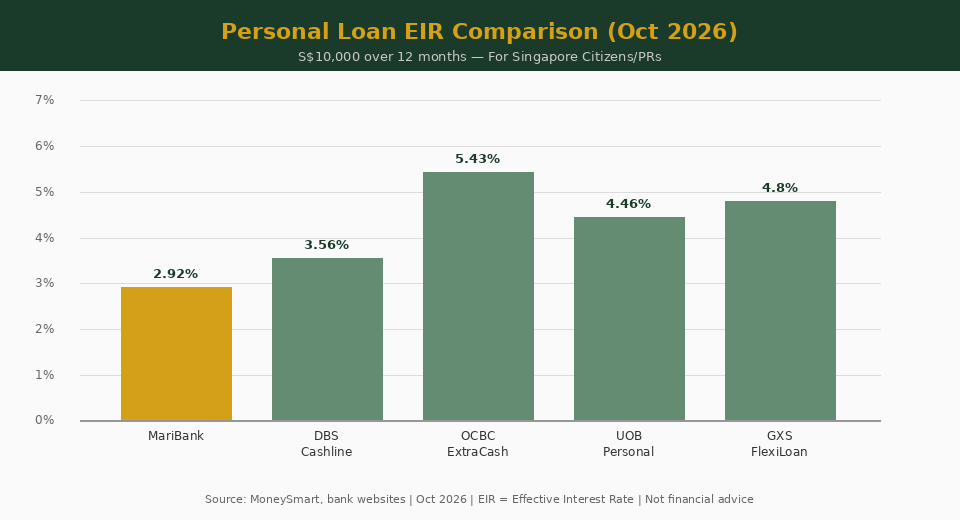
EIR comparison at advertised lowest rates. Source: MoneySmart, bank websites, October 2026. Not financial advice.
| Lender | Product | Flat Rate (from) | EIR (from) | Processing Fee |
|---|---|---|---|---|
| MariBank ⭐ | Instant Loan | 1.28% p.a. | 1.92% p.a.* | S$0 |
| DBS | Cashline | ~1.88% p.a. | ~3.56% p.a. | S$0 |
| GXS Bank | FlexiLoan | ~2.53% p.a. | ~4.80% p.a. | S$0 |
| UOB | Personal Loan | ~2.38% p.a. | ~4.46% p.a. | S$0 |
| OCBC | ExtraCash Loan | ~2.88% p.a. | ~5.43% p.a. | 1%–2% |
*MariBank EIR of 1.92% p.a. is for 3-month tenor; EIR for 12-month loan is approx. 2.3–2.5% p.a. Source: MoneySmart comparison, bank websites, October 2026. All rates are lowest advertised — actual rates vary by profile.
MariBank offers the lowest advertised rate among digital and traditional bank personal loans in Singapore as at October 2026. However, because the Mari Credit Card repayment structure means late payments incur 30.99% p.a. interest, disciplined borrowers stand to benefit most. If you’re someone who occasionally misses payment deadlines, the risk-adjusted cost could be higher than GXS or DBS alternatives that charge a flat late fee rather than compounding interest.
If you’re also considering GXS Bank for banking, check out our full comparison of digital bank savings rates alongside the loan options.
MariBank Loan: Honest Pros & Cons
Pros
- Lowest advertised rate in Singapore: 1.28% p.a. flat (EIR from 1.92% p.a.) as at Oct 2026 — cheaper than traditional banks and other digital banks
- Fully digital, Singpass-integrated: No payslips, no branch visit — approval and disbursement within 10 seconds
- Low minimum loan: S$100 minimum — unusual flexibility for small bridging needs
- Zero processing fee: Unlike OCBC and some banks that charge 1–2%
- SDIC-insured institution: MariBank’s deposits are covered up to S$100,000 per depositor under the Singapore Deposit Insurance Corporation (SDIC)
- Transparent rate disclosure: You see your exact rate before committing — no post-approval surprises
Cons
- Credit card repayment structure: Repayments run through the Mari Credit Card — missing a payment triggers 30.99% p.a. interest, not a flat late fee
- No partial repayments: You must settle the full outstanding principal if you want to prepay — no flexibility
- Early repayment fee: S$100 or 3% of outstanding principal — penalises those who want to pay off early
- SC/PR only: No access for foreigners or Employment Pass holders
- Rate varies: The 1.28% p.a. is the lowest published rate — your actual rate depends on your credit profile and may be higher
- Tenor not freely selectable: MariBank decides which tenors you qualify for
The verdict: For a disciplined borrower with good credit who sets up autopay immediately, MariBank’s Instant Loan offers Singapore’s most competitive personal loan rate as at October 2026. The key risk is the credit card late-payment penalty — if you’re not 100% confident in monthly repayments, compare carefully with alternatives. Read more about managing your finances with the Singapore retirement planning calculator or explore CPF investment strategies to reduce reliance on borrowing.
Frequently Asked Questions: MariBank Loan Singapore
Is the MariBank Instant Loan safe? Is MariBank a legitimate bank?
What is the actual EIR for the MariBank loan over 12 months?
Can foreigners or Employment Pass holders apply for the MariBank loan?
What happens if I miss a MariBank loan repayment?
Can I repay the MariBank loan early?
How does the MariBank loan compare with the GXS FlexiLoan or Trust Bank?
Do I need an existing MariBank account to apply for the loan?
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Interest rates, fees, and eligibility criteria are subject to change — always verify directly with MariBank before applying. TKN does not earn referral fees from MariBank’s loan product. Data verified as at 10 October 2026.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.