Singapore and the UK held their 11th Financial Dialogue on 20 October 2026, spotlighting progress on capital market reforms that directly affect how retail investors buy and hold Singapore equities. From the S$5.4 billion Equity Market Development Programme (EQDP) to the October 5 board lot reduction for 11 blue-chip stocks, here is exactly what changed, what it means for your portfolio, and what to watch next.
What Is the UK-Singapore Financial Dialogue?
Held annually since 2013, the UK-Singapore Financial Dialogue is a bilateral forum between HM Treasury (HMT), the Bank of England, the Financial Conduct Authority (FCA) on the UK side, and the Monetary Authority of Singapore (MAS) on the Singapore side. It was established to deepen cooperation across financial services — and unlike a press conference or policy announcement, it is a working-level forum where both governments share what they are actually doing and align on joint priorities.
The 11th edition took place in Singapore on 20 October 2026, co-chaired by Ms Gwyneth Nurse (HMT Director General, Financial Services) and Mr Leong Sing Chiong (MAS Deputy Managing Director, Markets and Development). Critically for investors, capital markets reform featured as a dedicated agenda item — with MAS sharing an update on the Equities Market Review Group (EMRG) measures that have been rolling out across 2025 and 2026.
This matters to Singapore retail investors because the EMRG recommendations are the policy engine behind two concrete changes already in effect: the board lot reduction that took effect on 5 October 2026, and the EQDP that has channelled S$5.4 billion into Singapore-listed equities so far. Singapore’s Q3 2026 GDP growth of 5.4% adds further tailwind to this reform momentum.
MAS Equity Market Development Programme: S$5.4B Deployed, S$1.1B to Go
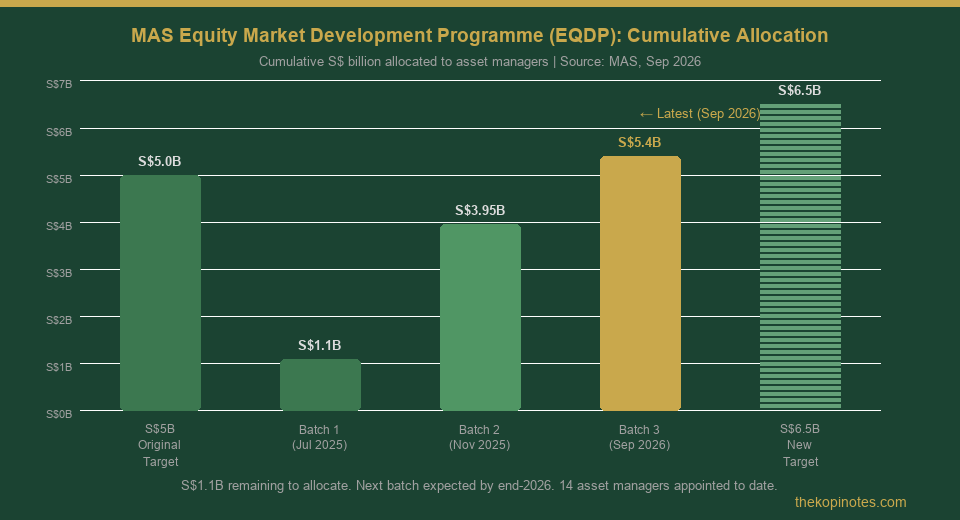
The EQDP — one of the most significant structural interventions in Singapore’s equity market in years — is now in its third batch. MAS announced Batch 3 on 29 September 2026, appointing five global asset managers: Amundi, Franklin Templeton, HSBC Asset Management, M&G Investments, and Natixis Investment Managers. This brought the cumulative allocation to S$5.4 billion across 14 managers, out of a S$6.5 billion total target — leaving S$1.1 billion still to be deployed in a future batch.
| Batch | Date | Amount | Managers | Cumulative |
|---|---|---|---|---|
| Batch 1 | July 2025 | S$1.1B | 3 | S$1.1B |
| Batch 2 | November 2025 | S$2.85B | 6 | S$3.95B |
| Batch 3 | September 2026 | S$1.45B | 5 | S$5.4B |
| Remaining (target S$6.5B) | S$1.1B | TBD | — | |
In practical terms, the EQDP commits institutional managers to deploy capital into SGX-listed equities — the kind of structural demand that can improve liquidity, reduce bid-ask spreads, and give Singapore stocks a sustained valuation tailwind. For investors in the Straits Times Index (STI) or S-REIT ETFs, this is the macro backdrop that supports the case for staying invested in the Singapore market.
Alongside the EQDP, MAS also launched the GEMS Market Making Grant — a S$20 million scheme from the Financial Sector Development Fund that covers roughly 80 small-and-mid-cap SGX stocks through to 31 December 2028. The grant subsidises market makers to tighten bid-ask spreads and improve price discovery for smaller stocks that are often thinly traded. If you hold any small-cap SGX stocks, expect liquidity to gradually improve.
SGX Board Lot Reduction: 11 Blue Chips, Lower Entry Cost
The most immediate change for retail investors was the board lot reduction effective 5 October 2026, which cut the minimum tradeable lot from 100 shares to 10 shares for 11 of SGX’s most expensive-per-lot stocks. This is a direct outcome of EMRG recommendations, making blue-chip investing materially more accessible. Here is what one lot now costs for each affected stock (at September 2026 prices):
| Stock (Code) | Share Price | Old Lot (100 shares) | New Lot (10 shares) | Saving |
|---|---|---|---|---|
| DBS Group (D05) | S$77.60 | S$7,760 | S$776 | S$6,984 |
| UOB (U11) | S$41.77 | S$4,177 | S$418 | S$3,759 |
| OCBC (O39) | S$31.85 | S$3,185 | S$319 | S$2,867 |
| Jardine Cycle & Carriage (C07) | S$27.04 | S$2,704 | S$270 | S$2,434 |
| Singapore Exchange (S68) | S$24.95 | S$2,495 | S$250 | S$2,246 |
| Great Eastern Holdings (G07) | S$20.78 | S$2,078 | S$208 | S$1,870 |
| Venture Corporation (V03) | S$16.67 | S$1,667 | S$167 | S$1,500 |
| Haw Par Corporation (H02) | S$14.19 | S$1,419 | S$142 | S$1,277 |
| Keppel Ltd (BN4) | S$11.53 | S$1,153 | S$115 | S$1,038 |
| Jardine Matheson (J36) | US$59.18 | US$5,918 | US$592 | US$5,326 |
| Prudential (K6S) | US$14.20 | US$1,420 | US$142 | US$1,278 |
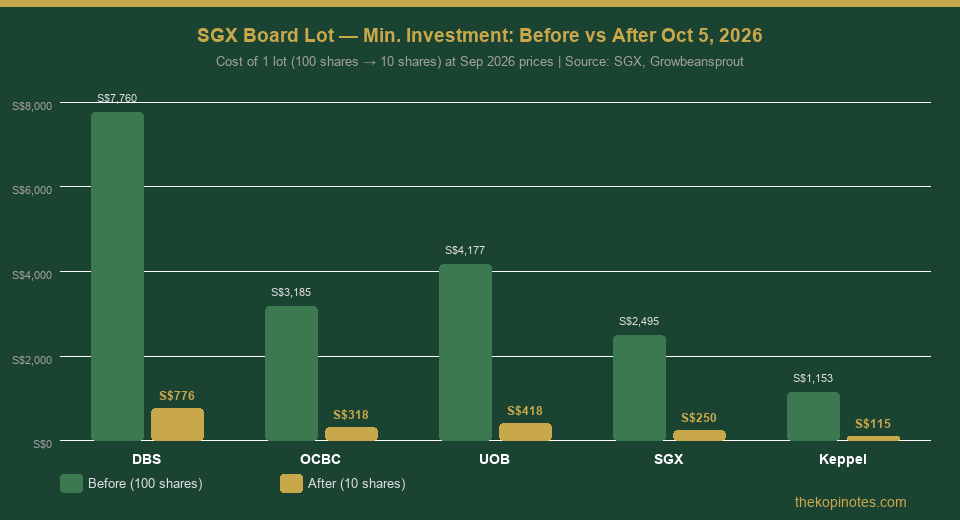
Source: SGX, Growbeansprout. Share prices as at 2 September 2026. Figures exclude brokerage fees. Jardine Matheson and Prudential are denominated in US dollars.
For investors considering DBS, OCBC or UOB after October’s bank selloff, the board lot change removes a key barrier. You can now start a DBS position for S$776 instead of S$7,760 — the kind of entry point that makes dollar-cost averaging practical for new or smaller investors.
Digital Finance and AI: Why the Dialogue Matters Beyond Capital Markets
While capital markets dominated the investor-relevant agenda, the 11th Dialogue also covered two forward-looking themes: digital finance and artificial intelligence in financial services.
On digital finance, the UK and Singapore exchanged updates on tokenisation and wholesale digital markets — MAS’s Project Guardian and BLOOM on one side, the UK’s Digital Securities Sandbox on the other. Both sides also discussed stablecoins and digital money for wholesale settlement. The relevance for retail investors is long-term: tokenised securities and settlement infrastructure will reduce costs and delays in how equities are traded and held.
On AI, both sides affirmed the importance of safe and responsible AI adoption in financial services. MAS’s SAFR framework for AI agents and the UK’s AI Adoption Plan for Financial Services are converging on similar principles. The PathFin.ai initiative — a joint UK-Singapore collaboration to apply AI in the financial sector — continues to develop. This institutional AI alignment will shape how your broker’s apps, robo-advisers, and fund managers operate over the coming years.
Sustainable Finance: The Singapore-Asia Taxonomy 2.0
For investors in S-REITs, green bonds, and ESG funds, Singapore is updating its Singapore-Asia Taxonomy to version 2.0. The revised taxonomy will expand the classification framework for sustainable activities, making it easier to verify whether a fund or REIT genuinely qualifies as “green.” MAS also highlighted its Financial Sector Carbon Market Grant, which supports Singapore’s ambition to become a regional carbon trading hub.
If you are evaluating S-REITs with 6%–9.3% yields on TKN’s October 2026 income screen, it is worth noting that green-certified assets are increasingly viewed favourably by institutional investors funded under the EQDP — which creates a valuation premium incentive for REITs to green their portfolios.
What This Means for Singapore Retail Investors: 5 Practical Takeaways
Putting all the threads together, here is how the 11th Dialogue and surrounding reforms affect your investment decisions today:
- Lower entry barriers for blue chips. With 11 stocks now tradeable in lots of 10, you can build a diversified Singapore portfolio at a fraction of the old cost. The three banks, Keppel, SGX, and Venture Corp are all now accessible under S$500 per lot.
- Institutional demand supports Singapore equities. S$5.4B in EQDP commitments — with S$1.1B more to come — represents sustained demand for SGX-listed stocks. This is structural, not speculative.
- Better liquidity for small-mid caps via GEMS. The S$20M market making grant covering ~80 stocks should tighten spreads and reduce the cost of entering and exiting smaller SGX names.
- Green assets get a structural premium. With Singapore-Asia Taxonomy 2.0 on the way, ESG certification will become a differentiator for REITs and infrastructure stocks targeting institutional capital.
- T-bills and CPF remain relevant as a cash management base. Despite MAS holding its policy rate steady in October, the Singapore dollar is stable and 6-month T-bill yields remain attractive ahead of the October 22 auction. Using T-bills to park your cash while waiting for S-REIT entry points remains a sound strategy.
What to Watch Next
The 12th UK-Singapore Financial Dialogue will be hosted by the UK in 2027. Between now and then, watch for: the final EQDP Batch 4 allocation (S$1.1B remaining); further SGX board lot expansions to additional stocks; Singapore-Asia Taxonomy 2.0 final publication; and any SGX-HMT collaboration on cross-listing or mutual recognition of funds. The industry-led UK-Singapore business roundtable that followed on 21 October 2026 may produce additional private-sector initiatives to watch.
What is the UK-Singapore Financial Dialogue?
What did the 11th UK-Singapore Dialogue announce for Singapore investors?
What is the MAS EQDP and how much has been committed?
Which SGX stocks had their board lot reduced from 100 to 10 shares?
What is the GEMS Market Making Grant?
How does the Singapore-Asia Taxonomy 2.0 affect REIT investors?
When is the next UK-Singapore Financial Dialogue?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.