How to Invest in Singapore: 5 Common Mistakes Beginners Make (2026 Guide)
Most beginners make at least one of these five mistakes. Each one has a measurable cost — here is what it is and how to avoid it.
Learning how to invest in Singapore is not as complicated as most beginners believe — but the five mistakes below cost real money. New investors routinely pay too much in fees, wait too long to start, or sell the moment markets fall. Each mistake has a compounding cost that is easy to calculate but hard to reverse. This guide lays out what goes wrong, how much it costs in SGD, and what to do instead.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
Table of Contents
Contents — Click to expand
- Why Getting Investing Right Early Matters
- Mistake 1: Waiting Until You “Know Enough”
- Mistake 2: Trying to Pick Winning Stocks
- Mistake 3: Ignoring Fees and Hidden Costs
- Mistake 4: Missing Singapore’s Tax Advantages
- Mistake 5: Panic-Selling During Market Corrections
- A Simpler Way to Start Investing in Singapore
- Frequently Asked Questions
Why Getting Investing Right Early Matters
The cost of starting late is the most concrete argument for investing in Singapore sooner rather than later. A Singapore resident who puts S$500 a month into a broadly diversified index ETF at age 25 — earning 7% a year, a broadly used long-run estimate for global equities — will have roughly S$1.31 million by age 65. Start at 35 instead, same contribution, same return, and the balance at 65 is about S$610,000. The ten-year delay costs approximately S$702,000 — not in fees or taxes, but in lost compounding time.
Put another way: doing almost anything — even imperfectly — for longer beats doing it perfectly but late. The five mistakes below are all worth correcting. The biggest one, by a wide margin, is delaying the correction.
Mistake 1: Waiting Until You “Know Enough”
The most common investing mistake in Singapore is not making a bad trade. It is making no trade at all.
The feeling of not being ready is nearly universal among new investors. Financial literacy is the top reason Singaporeans give for not investing, according to MAS consumer research. The irony: most of what you think you need to know is learned by doing, not by reading.
You do not need to understand options pricing, bond duration, or how to read a company’s balance sheet before you put S$500 into a low-cost index ETF. The core mechanics are straightforward — buy a fund that owns hundreds or thousands of companies, pay as little as possible in fees, hold for decades. That is the strategy used by most long-run outperformers, and it requires very little specialist knowledge to execute.
Every month you wait is a month of compounding you give up permanently. At a 7% annual return, money doubles roughly every 10 years (the Rule of 72). An investor who waits five extra years to “feel ready” does not lose five years of returns — they lose the returns on those returns, and the returns on the returns on those returns, compounding outward for the rest of their investing life.
The fix is to start small. Many Singapore brokers, including Syfe, allow you to start with as little as S$100. If you are brand new to how to invest in Singapore, the step-by-step beginners guide to investing in Singapore covers exactly how to open a brokerage account and place your first trade.
Mistake 2: Trying to Pick Winning Stocks
Stock-picking is the second most common mistake — and the most expensive for investors who do manage to start.
The appeal is intuitive. You read a piece about a company, the business makes sense, you buy shares. The problem is the evidence: SPIVA, which tracks active fund performance against benchmarks across markets, consistently finds that 80–90% of active fund managers underperform their benchmarks over 15-year periods. These are professionals with research teams, trading algorithms, and real-time data. Retail investors, working from news articles and quarterly reports, face even longer odds.
The standard explanation is market efficiency: by the time a retail investor reads news about a company, professional traders and algorithms have already priced it in. Acting on yesterday’s news is not an edge.
For a Singapore investor, the practical alternative is an index ETF. A fund like CSPX (iShares Core S&P 500 UCITS ETF, listed on the London Stock Exchange) gives exposure to 500 of the largest US companies for 0.07% in annual fees. You do not need to pick the right companies. You own all of them.
The question of whether to go index or active is covered with Singapore-specific data and worked examples in the index funds vs active investing in Singapore guide.
Mistake 3: Ignoring Fees and Hidden Costs
Fees are invisible in the short run and expensive in the long run.
A Singapore investor who puts S$200,000 into a unit trust charging 1.5% in annual management fees pays roughly S$3,000 in fees in year one. Compounded over 20 years at 7% gross return, a 1.5% annual fee reduces the ending balance from approximately S$764,000 (at 0.07% — the CSPX TER) to approximately S$584,000 (at 1.5%). That is a S$180,000 difference from a fee the investor might not even have noticed.
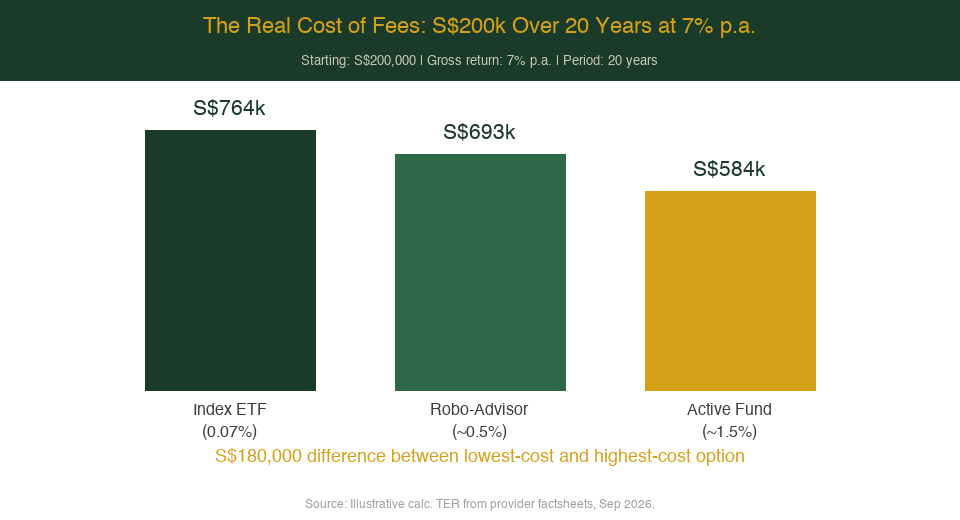
| Investment Type | Typical Annual Fee | Comment |
|---|---|---|
| Unit trust / active managed fund | 1.0–2.5% | Includes fund management fee + distributor trail commission |
| Robo-advisor (e.g. Endowus, Syfe) | 0.3–0.65% | Includes platform fee + underlying fund fees |
| Index ETF (self-directed, e.g. CSPX) | 0.07–0.20% | Fund fee only — brokerage commission is separate, typically S$1–S$10 per trade |
Source: MAS product comparison tables, provider websites, September 2026
Beyond the headline management fee, three hidden costs cut into returns:
- FX spread: Buying USD-denominated ETFs from SGD requires a currency conversion. IBKR charges approximately 0.002% on SGD/USD; some banks charge 1–2%. On a S$10,000 purchase, that is S$200 gone at the point of entry.
- Brokerage commission: IBKR charges USD 1.00 minimum per trade on US and LSE markets. Some local brokerages charge S$10–S$25 per foreign trade. For a S$1,000 monthly contribution, a S$25 commission represents a 2.5% drag before the investment even starts growing.
- Platform fee: Some custodian or nominee account fees apply even if you hold, not trade. Check the full fee schedule, not just the headline commission rate.
For investors who want to keep it simple, the FSMOne referral code page has details on FSMOne’s Regular Savings Plan — one of the lowest-cost options for building ETF positions monthly in Singapore.
Mistake 4: Missing Singapore’s Tax Advantages
Singapore investors operate in one of the most tax-friendly environments in the world for investing. Missing the legal routes to reduce your tax drag is leaving money on the table.
Singapore’s three key tax advantages for investors:
1. Zero capital gains tax. There is no tax on investment profits in Singapore. You can sell a S$500,000 position at a S$200,000 gain and owe nothing to IRAS. Most countries — the US, UK, Australia — have capital gains taxes ranging from 10% to 30%+. Singapore does not.
2. No dividend withholding tax on Singapore dividends. Singapore companies do not withhold tax on dividends paid to individual investors. This is one reason Singapore REITs (S-REITs) are attractive compared to US REITs, where a 30% withholding tax applies to distributions received by non-US investors.
3. Supplementary Retirement Scheme (SRS) tax deduction. Contributions to an SRS account are fully deductible from taxable income in the year you make them. Singapore Citizens and Permanent Residents can contribute up to S$15,300 per year; foreigners can contribute up to S$35,700.
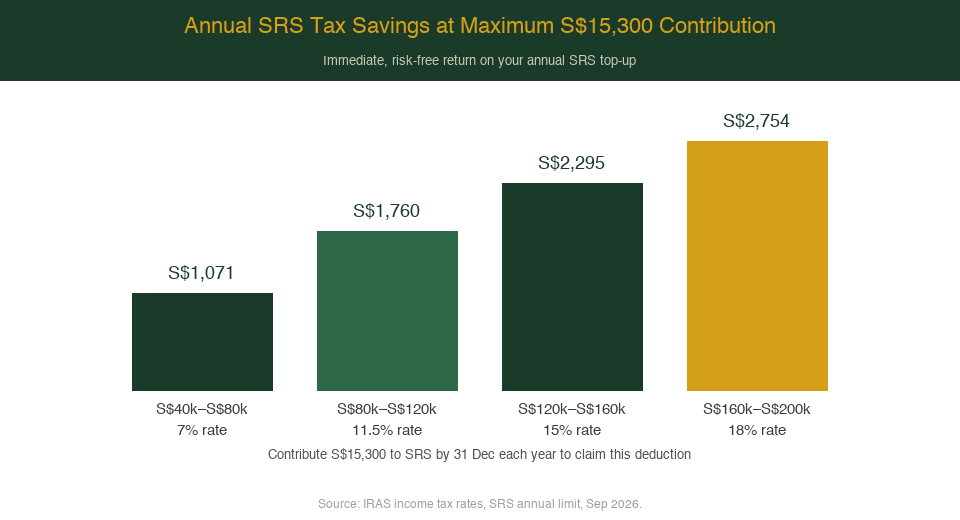
| Annual Chargeable Income | Marginal Tax Rate | Max SRS Contribution | Estimated Annual Tax Saving |
|---|---|---|---|
| S$40,001–S$80,000 | 7% | S$15,300 | ~S$1,071 |
| S$80,001–S$120,000 | 11.5% | S$15,300 | ~S$1,760 |
| S$120,001–S$160,000 | 15% | S$15,300 | ~S$2,295 |
| S$160,001–S$200,000 | 18% | S$15,300 | ~S$2,754 |
Source: IRAS income tax brackets, Year of Assessment 2026
SRS funds can be invested in SGX-listed securities, approved unit trusts, and Singapore government securities. For CPF-eligible investments, the CPF Investment Scheme (CPFIS) lets you invest CPF OA savings — currently earning 2.5% per annum — in a range of approved investments. The full mechanics are covered in the CPF investment strategy Singapore guide.
The fact that Singapore has no CGT, no dividend withholding tax on local securities, and a deductible savings scheme makes it materially easier to build wealth here than in many other countries. Leaving SRS contributions unused is the most common and most easily corrected version of this mistake.
Mistake 5: Panic-Selling During Market Corrections
Market corrections — drops of 10% or more from a recent peak — are not exceptional events. Since 1928, the S&P 500 has experienced a 10%+ correction roughly once a year on average. Bear markets (drops of 20%+) occur approximately every three to four years. They are a feature of investing, not a malfunction.
The mistake is not surviving a correction. It is selling during one.
An investor who sold their S&P 500 holdings in March 2020 — when the index dropped 34% in 33 days during the COVID crash — and waited for things to “settle down” before re-entering would have missed one of the fastest recoveries in market history. The index regained its pre-crash high within six months. By the end of 2021 it had gained over 100% from the March 2020 trough. Selling at the bottom and buying back at the top is the exact inverse of what generates returns.
Three things help:
- Automate contributions. A standing monthly instruction to buy your chosen ETF removes the decision from the moment of maximum fear. When markets fall, your regular purchase buys more units at lower prices — dollar-cost averaging working in your favour.
- Hold a buffer. A portion of your portfolio in low-volatility assets — Singapore Savings Bonds, T-bills, a high-yield savings account — gives you the psychological and financial cushion to ride out equity falls without needing to sell. The Singapore Savings Bonds guide covers current rates and how to subscribe.
- Know your allocation before you invest. If a 30% fall in your portfolio would force you to sell or would cause severe distress, you are overexposed to equities. The Singapore retirement calculator lets you model different allocations and see their effect on your long-term balance.
The allocation that covers life-stage investing considerations — how much equity versus bonds or cash to hold at age 30 vs 50 — is covered in full in the Singapore investing by life stage guide.
A Simpler Way to Start Investing in Singapore
Avoiding these five mistakes does not require expertise. It requires a simple, consistent approach:
1. Start with a low-cost, broadly diversified ETF. CSPX (tracks the S&P 500) or VWRA (tracks global equities) on the London Stock Exchange are the two most widely used starting points for Singapore investors. Both are Ireland-domiciled UCITS ETFs, which means 15% withholding tax on US dividends instead of 30%, and no US estate tax exposure. Neither requires picking individual companies.
2. Use a low-cost broker. Interactive Brokers (IBKR) is the most cost-effective for larger amounts (referral code: jianxiong368). Syfe’s brokerage platform is the easiest for beginners — commission-free for its regular savings plan and no minimum. The Syfe referral code page has the current sign-up bonus. For investors who prefer managed ETF portfolios, the Endowus referral code page covers the platform’s SRS and CPF-eligible options.
3. Invest a fixed amount every month. S$500 to S$2,000 per month, regardless of market conditions, removes the timing problem entirely. The compounding does the rest over time.
4. Use SRS every year. Max the S$15,300 SRS contribution before the calendar year ends. The tax saving alone — between S$1,071 and S$2,754 depending on your bracket — is an immediate, risk-free return on that contribution. Invest SRS funds in the same style as your main portfolio where eligible.
5. Check quarterly, rebalance annually. More frequent checking is associated with more panic decisions. Less monitoring, not more, tends to produce better results over long periods. A once-a-year rebalance — selling a little of what has grown, buying a little of what has lagged — keeps your allocation on track without requiring constant attention.
For a complete step-by-step walkthrough of how to open a brokerage account and make your first ETF purchase, see the beginner’s guide to investing in Singapore.
Not financial advice. Past returns do not guarantee future results. All calculations assume a constant 7% annual return for illustrative purposes only. Data as at September 2026.
Frequently Asked Questions
How much money do I need to start investing in Singapore?
What is the best investment for beginners in Singapore?
Is investing in Singapore taxed?
Can I use my CPF to invest?
When should I start investing in Singapore?
What should I do if markets crash after I invest?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.