MEDISAVE GUIDE · 2026
MediSave Limit 2026: 7 Mistakes Singaporeans Make With Their Healthcare Account
Most Singaporeans know MediSave exists. Far fewer know how to use it correctly — or what the limits actually mean at the hospital checkout counter.
MediSave is Singapore’s mandatory national medical savings account, capped at the Basic Healthcare Sum (BHS) of $79,000 for 2026. It can be used to pay for hospitalisation, day surgery, Integrated Shield Plan (ISP) premiums, and approved outpatient treatments — but each use comes with specific rules, daily limits, and age-based caps that catch most Singaporeans off guard when the bill arrives.
Not financial advice. All figures are for educational reference only. Data verified as at 2026-10-05 from CPF Board and MAS official sources.
Mistake 1: Confusing the BHS With Your Daily Withdrawal Limit
The MediSave Basic Healthcare Sum (BHS) for 2026 is $79,000. This is the maximum balance you can hold in your MediSave account — not a withdrawal entitlement.
Many Singaporeans assume that because their MediSave balance is high, they can draw on it freely at any hospital. What actually governs your claim is the daily withdrawal limit, which is set separately:
- Class B1 and above wards: $1,130 per day
- Class B2 and C wards: $400 per day
- Day surgery: $830 per procedure
A patient spending 7 days in a Class B1 ward can claim a maximum of $7,910 from MediSave via the daily limit — regardless of whether they have $79,000 sitting in their account. The BHS is a cap on accumulation, not a credit limit.
Why it matters: Hospital bills for complex procedures — cardiac surgery, cancer treatment, orthopaedic operations — can run $30,000 to $100,000+. MediSave covers only a fraction. Your best Integrated Shield Plan in Singapore covers the rest — but only up to its own policy limits and ward class entitlement.
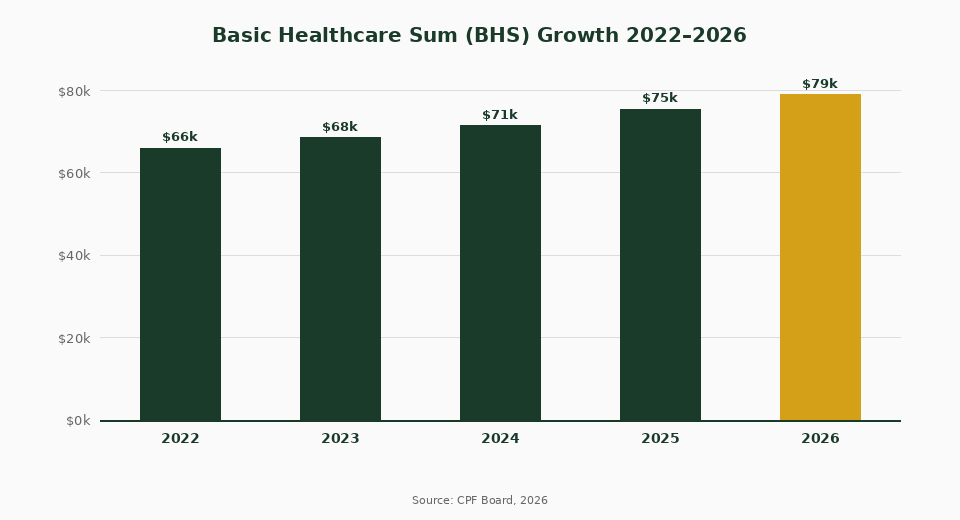
Source: CPF Board, 2026. BHS increases annually and locks in at age 65.
Mistake 2: Expecting MediSave to Cover 100% of the Hospital Bill
Even with both MediSave and an ISP, you will almost certainly have an out-of-pocket expense. Here is why:
ISPs have a deductible — the initial amount you pay before insurance kicks in. Deductibles in 2026 range from $1,500 to $3,500 per policy year depending on the plan and ward class. Above the deductible, most ISPs impose co-insurance of 10%, meaning the policyholder shares 10% of all remaining eligible costs.
MediSave covers hospitalisation up to the daily limits mentioned above. The ISP then covers eligible bills above that, minus your deductible and co-insurance share. Cash is what bridges the gap.
Some policyholders add a rider to their ISP to cover the deductible and co-insurance — bringing their cash exposure close to zero. However, riders must be paid entirely in cash (see Mistake 3). To understand exactly how deductibles affect your real out-of-pocket exposure, read our ISP deductible impact guide for 2026.
Mistake 3: Trying to Pay ISP Rider Premiums From MediSave
This is one of the most commonly misunderstood rules in Singapore’s healthcare financing system.
Under CPF rules, MediSave can be used to pay the base Integrated Shield Plan premium — which covers MediShield Life and the additional private insurer component. But rider premiums — which cover deductibles and co-insurance — cannot be paid using MediSave. They must be paid entirely in cash.
This distinction matters because rider costs are substantial:
- A standard rider for a 40-year-old on a mid-tier ISP: approximately $600–$900/year in cash
- For a 55-year-old on a comprehensive plan with full-rider coverage: $1,500–$2,500/year or more
When budgeting for healthcare costs, many people look only at their ISP’s MediSave-payable premium. If they have a rider, the actual annual cost is higher — and the rider portion is a cash commitment that compounds as you age. Plan accordingly.
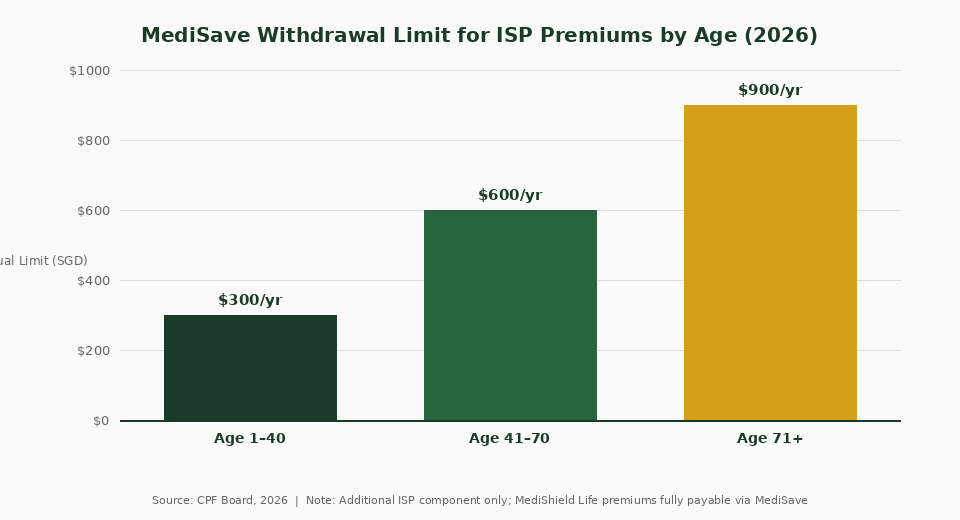
Source: CPF Board, 2026. AWL figures apply to the additional ISP component only; MediShield Life premiums are fully payable via MediSave.
Mistake 4: Not Knowing the ISP MediSave Withdrawal Limit Is Age-Tiered
The amount you can withdraw from MediSave each year to pay your ISP’s additional premium is not a fixed number — it scales with age through the Additional Withdrawal Limit (AWL).
| Age Band | ISP AWL (per year) | Practical Implication |
|---|---|---|
| Age 1–40 | $300 | Cash top-up likely needed for most private ISPs |
| Age 41–70 | $600 | MediSave may cover more of the premium as it rises with age |
| Age 71+ | $900 | Higher AWL helps offset rising premiums in old age |
Source: CPF Board, 2026. AWL applies to additional ISP component only.
Many Singaporeans in their 30s choose premium ISPs with additional premiums of $500–$700/year, assuming MediSave will fully cover it. At age 35, the AWL is only $300 — meaning at least $200–$400 in cash is needed annually. This cash outlay grows as premiums increase with age, even though the AWL also rises.
For the full breakdown of how AWL varies by age and plan tier, see our detailed guide on MediSave withdrawal limits for ISP premiums in 2026.
Mistake 5: Not Realising MediSave Can Cover Immediate Family Members
Your MediSave account is not just for your own healthcare. Under CPF Board rules, you can use your MediSave to pay for hospitalisation, approved outpatient treatments, and ISP premiums for:
- Your spouse
- Your children
- Your parents and parents-in-law
- Your grandparents and grandparents-in-law
This is a significant benefit that many working adults overlook. Adult children who are supporting elderly parents with limited CPF savings can draw on their own MediSave account to cover the parents’ ISP premiums — subject to the AWL for the parent’s age group.
Example: Your 72-year-old mother is on an ISP with an additional premium of $1,200/year. The AWL for her age band (71+) is $900. You can pay $900 from your own MediSave account toward her premium, with the remaining $300 in cash.
Mistake 6: Thinking You Can Top Up MediSave Freely After Age 65
Here is a nuance that catches many pre-retirees off guard: the BHS is not a fixed number for everyone. It increases annually — but only for those who have not yet turned 65.
Once you turn 65, your BHS is frozen at the BHS applicable in the year you turn 65. This becomes your permanent, personalised BHS for the rest of your life.
| Turned 65 in Year | Fixed BHS (for life) |
|---|---|
| 2022 | $66,000 |
| 2023 | $68,500 |
| 2024 | $71,500 |
| 2025 | $75,500 |
| 2026 | $79,000 |
Source: CPF Board, 2022–2026 BHS announcements. Verified as at 2026-10-05.
A Singaporean currently aged 62 turning 65 in 2029 will have a BHS set at whatever the BHS is in 2029 — likely higher than today’s $79,000. The key planning insight is to maximise voluntary top-ups before you turn 65, to benefit from the highest possible BHS that applies at the time of lock-in.
After 65, any CPF contributions that would push your MediSave above your fixed BHS are automatically transferred to your Retirement Account (RA) instead. Use our Singapore retirement calculator to model how MediSave flows interact with your overall CPF picture.
Mistake 7: Missing the MMSS Matching Grant
The Matched MediSave Saving Scheme (MMSS) — significantly enhanced in 2026 — provides dollar-for-dollar government matching on voluntary MediSave top-ups, up to $1,000 per year for Singaporeans aged 55 to 70 whose MediSave balance is below the BHS.
That is up to $1,000 in free government money each year, yet this scheme has remarkably low uptake among those who qualify. The top-up must be voluntary (not from mandatory CPF contributions) and can be made in cash or via inter-account CPF transfer.
Eligibility criteria:
- Singapore Citizens or Permanent Residents aged 55–70
- MediSave balance below the prevailing BHS
- Not receiving means-tested government assistance already addressing healthcare costs
If you are eligible and invest through platforms that leverage CPF-SA or SRS (see our CPF investment strategy guide), maximising MMSS before you invest elsewhere is arguably the highest guaranteed return available — 100% on day one, with zero market risk.
For managed portfolios that include MediSave-related planning tools, Endowus (referral code: 2V343) offers CPF and SRS investment capabilities that pair well with MMSS top-up planning.
MediSave 2026 Quick Reference
| Limit / Cap | 2026 Figure | Notes |
|---|---|---|
| Basic Healthcare Sum (BHS) | $79,000 | Maximum MediSave balance; freezes at 65 |
| Hospitalisation daily limit (B1+) | $1,130/day | Class B1, A, Private wards |
| Hospitalisation daily limit (B2/C) | $400/day | Class B2 and C wards |
| Day surgery limit | $830/procedure | Per day surgery episode |
| ISP AWL — Age 1–40 | $300/year | Additional ISP component only |
| ISP AWL — Age 41–70 | $600/year | Additional ISP component only |
| ISP AWL — Age 71+ | $900/year | Additional ISP component only |
| MMSS matching grant | Up to $1,000/year | Ages 55–70, voluntary top-up only |
Source: CPF Board. Data verified as at 2026-10-05.
Know Your Coverage Before You Need It
MediSave is most useful when you understand its limits before you’re sitting in a hospital. Review your ISP coverage, check your AWL by age band, and if you’re 55–70, explore the MMSS matching opportunity before the financial year ends.
For managed investing that integrates CPF and SRS alongside your healthcare planning, Endowus (referral code: 2V343) offers government-accredited portfolios with no sales commissions.
Frequently Asked Questions
What is the MediSave Basic Healthcare Sum (BHS) in 2026?
Can I use MediSave to pay for ISP rider premiums?
How much can I withdraw from MediSave for hospitalisation?
What is the MMSS and who qualifies?
Can I use my MediSave for my parents' healthcare?
What happens to my MediSave BHS when I turn 65?
How much can I withdraw from MediSave per year for my ISP premium?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.