DIGITAL BANKS · FIXED DEPOSITS
DBS 1-Year Fixed Deposit Rate (November 2026): What You’re Actually Getting
DBS 1-year fixed deposit earns 1.00% p.a. — but only if your total DBS deposits stay below S$20,000. If you hold more, every tenure drops to 0.05% p.a. Here’s the full picture.
The DBS 1-year fixed deposit rate in November 2026 is 1.00% per annum — but this applies only to deposits where your total DBS deposit balance remains below S$20,000. Hold more than that across all DBS fixed deposit accounts combined, and every tenure collapses to a flat 0.05% p.a. At that rate, a S$50,000 placement earns just S$25 per year. Competitor banks currently offer up to 2.30% p.a. for the same 1-year tenure.
Not financial advice. All figures are for educational reference only. Data verified as at 6 November 2026 against official bank websites and industry aggregators.
What Is the DBS 1-Year Fixed Deposit Rate?
DBS Bank — Singapore’s largest bank by assets — offers fixed deposit accounts in Singapore dollars, with terms ranging from 1 to 36 months. A fixed deposit locks in a guaranteed interest rate for the chosen tenure, making it one of the simplest capital-preservation tools available to Singapore residents.
As at November 2026, the DBS 1-year (12-month) fixed deposit rate is 1.00% per annum for new placements where the customer’s total balance across all DBS and POSB fixed deposit accounts remains below S$20,000. This is a non-promotional board rate — DBS has not published any special promotional fixed deposit rate at time of writing.
However, there is a critical catch that many depositors overlook: if your total DBS deposit portfolio exceeds S$20,000, the rate is not tiered — it drops entirely to 0.05% p.a. across every tenure. This is not a marginal rate that applies only to the amount above S$20,000; it applies to your entire balance.
DBS Fixed Deposit Rates by Tenure (November 2026)
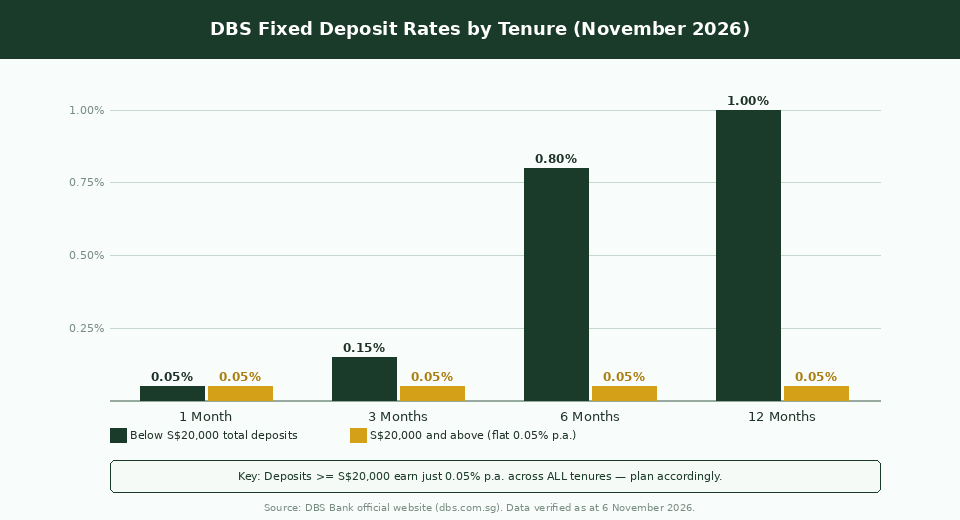
The table below shows the full range of DBS SGD fixed deposit rates across all available tenures, as at 6 November 2026:
| Tenure | Rate: Below S$20,000 | Rate: S$20,000 & Above |
|---|---|---|
| 1 Month | 0.05% p.a. | 0.05% p.a. |
| 3 Months | 0.15% p.a. | 0.05% p.a. |
| 6 Months | 0.80% p.a. | 0.05% p.a. |
| 12 Months | 1.00% p.a. | 0.05% p.a. |
Source: DBS Bank official website (dbs.com.sg). Data verified as at 6 November 2026. Rates subject to change without notice.
What this means in practice: A depositor placing S$10,000 for 12 months earns S$100 at the end of the year. But someone placing S$25,000 earns just S$12.50 — because their total DBS deposits exceed S$20,000, the rate collapses to 0.05% p.a. for the entire S$25,000.
How DBS Compares to Other Singapore Banks (1-Year FD)
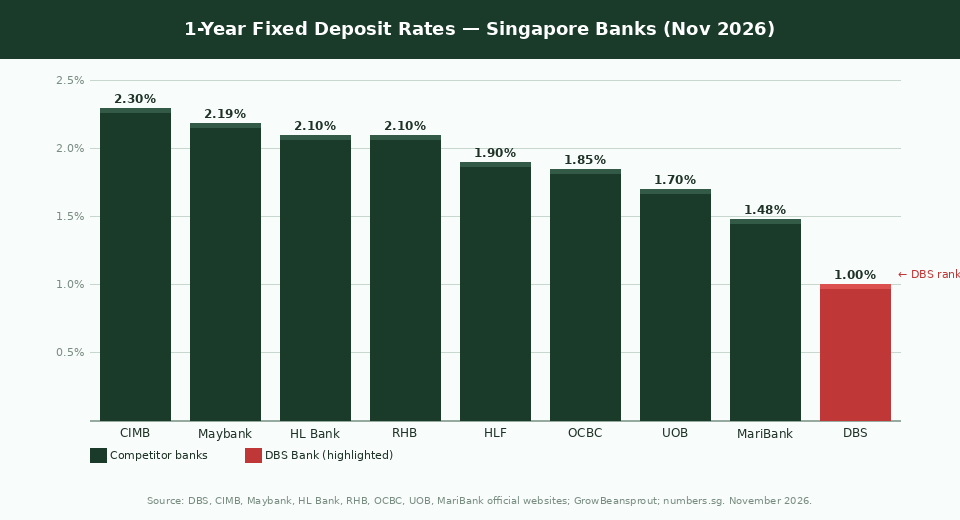
To understand what you are giving up by choosing DBS, the comparison below shows 1-year fixed deposit rates from across the Singapore banking market as at November 2026. For a comprehensive look at the full market, see our highest fixed deposit rate in Singapore tracker.
| Bank | 1-Year Rate | Notes |
|---|---|---|
| CIMB | 2.30% p.a. | No minimum. Online placement. |
| Maybank | 2.19% p.a. | iSAVvy Plus; min. S$500. |
| HL Bank | 2.10% p.a. | Min. S$10,000. |
| RHB | 2.10% p.a. | Min. S$20,000. |
| Hong Leong Finance | 1.90% p.a. | Min. S$10,000. Finance company, not bank. |
| OCBC | 1.85% p.a. | Via OCBC app; min. S$30,000. |
| UOB | 1.70% p.a. | Min. S$10,000. |
| MariBank | 1.48% p.a. | Digital bank; min. S$1,000. |
| DBS (<S$20K) | 1.00% p.a. | Lowest in category. Deposits must remain below S$20K total. |
| DBS (≥S$20K) | 0.05% p.a. | Effectively negligible return. |
Source: MAS, individual bank official websites, GrowBeansprout, numbers.sg. As at 6 November 2026. Rates and conditions subject to change. All rates in SGD.
The gap is stark: at 2.30% p.a. from CIMB versus 1.00% p.a. from DBS, a S$10,000 placement earns S$130 more per year at CIMB — a difference of 130% more income from the same capital.
Who Should Consider a DBS Fixed Deposit?
Despite offering below-market rates, a DBS fixed deposit still makes sense in a narrow set of circumstances:
- Total DBS deposits below S$20,000: If you are placing a small sum (under S$20,000 combined across all DBS fixed deposits), the 1.00% p.a. is still real return, though uncompetitive.
- Relationship banking convenience: If your salary, home loan, and investment accounts are all with DBS, the administrative simplicity of placing a fixed deposit within the same banking dashboard may outweigh the rate differential — particularly for smaller sums.
- Corporate or trust accounts: Some entities that already operate on DBS infrastructure may prefer to consolidate liquidity within DBS for governance reasons.
For the vast majority of individual savers in Singapore — particularly those with deposits exceeding S$20,000 — the DBS rate is not competitive. The question is simply where to redirect your capital.
Better Alternatives to DBS Fixed Deposit
If you are looking to maximise returns on idle cash in Singapore, consider these government-backed or regulated alternatives:
Singapore T-Bills (91-day and 182-day): Singapore Government Treasury Bills are among the safest instruments available, backed by the AAA-rated Singapore Government. Recent cutoff yields have hovered in the 3% range. Our Singapore T-bills 2026 guide explains how to apply via your CPF or cash account.
Singapore Savings Bonds (SSBs): With 10-year average interest currently above 2.5% p.a. and full principal protection with monthly liquidity, SSBs are an excellent alternative for sums up to S$200,000 per individual. See our Singapore Savings Bonds 2026 guide for full details on how to apply.
Competitor fixed deposits: CIMB currently leads the 1-year fixed deposit market at 2.30% p.a. with no minimum deposit requirement and online placement. For a full ranking updated monthly, refer to our highest fixed deposit rate Singapore comparison.
Digital bank savings accounts: Platforms like Syfe referral code and sign-up bonus offer high-yield cash management solutions. For longer-term wealth building beyond fixed deposits, Endowus referral code gives access to low-cost institutional funds that have historically outpaced fixed deposit rates over multi-year horizons.
The key principle: Fixed deposits and cash instruments play an important role in an emergency fund or short-term liquidity buffer. But for sums beyond your 6-month emergency fund, rate shopping — not convenience — should drive the decision. A 1.30 percentage-point difference on S$30,000 is S$390 per year, compounding silently in someone else’s account.
Frequently Asked Questions
What is the current DBS 1-year fixed deposit rate in Singapore?
Why does DBS charge different rates above and below S$20,000?
Is a DBS fixed deposit safe?
Can I break a DBS fixed deposit before maturity?
Is there a minimum deposit amount for DBS fixed deposits?
How does the DBS 1-year fixed deposit compare to Singapore T-Bills?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.