MediSave Limit 2026: What You Can Claim for Fertility Treatment and IVF in Singapore
MOH-verified limits, government co-funding, and how your Integrated Shield Plan fits in.
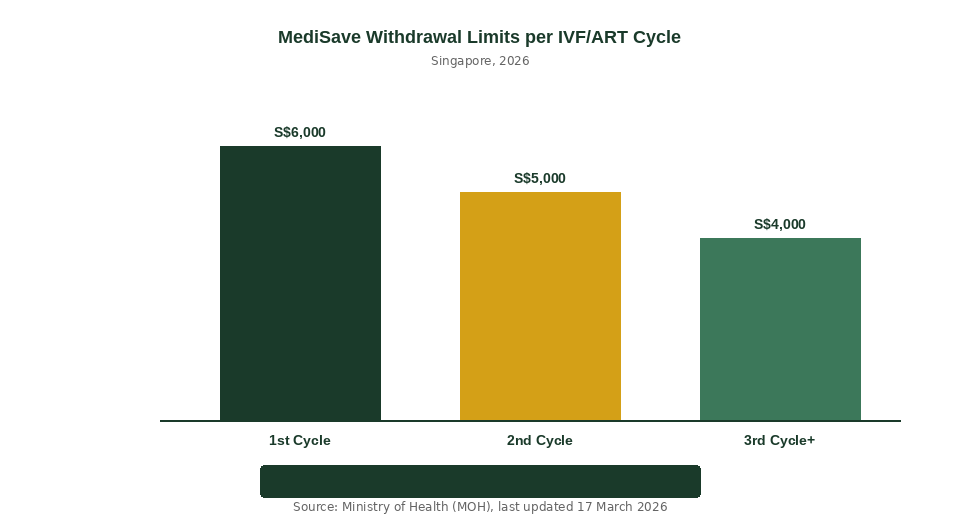
Singaporeans can use MediSave for fertility treatment — but the withdrawal limits are separate from your hospitalisation account and work differently. For IVF and other assisted reproduction procedures (ART) at MOH-approved centres, MediSave covers up to S$6,000 for the first cycle, S$5,000 for the second, and S$4,000 from the third cycle onwards, with a lifetime cap of S$15,000. On top of that, eligible Singapore Citizen couples receive government co-funding of up to 75% per cycle at public AR centres.
Not financial advice. All figures are for educational reference only. Data verified against MOH as at 7 November 2026.
Table of Contents
Contents — Click to expand
- What Does MediSave Cover for Fertility Treatment?
- MediSave Withdrawal Limits per IVF Cycle (2026)
- Government Co-Funding on Top of MediSave
- Total Cost Breakdown: A Typical IVF Journey
- How Your Integrated Shield Plan Fits In
- What Is NOT Covered by MediSave
- 5 Practical Tips for Fertility Treatment Cost Planning
- Frequently Asked Questions
What Does MediSave Cover for Fertility Treatment?
MediSave can be used for Assisted Conception Procedures (ACPs) — the umbrella term MOH uses for fertility treatments. ACPs that are MediSave-claimable include:
- IVF (In Vitro Fertilisation) — standard fresh and frozen cycles
- IVF with ICSI (Intracytoplasmic Sperm Injection)
- In-Vitro Maturation (IVM) cycles
- Donor egg or sperm cycles
- Double stimulation cycles
- GIFT (Gamete Intrafallopian Transfer)
- IUI (Intrauterine Insemination) — up to 3 cycles
- PGT-M and PGT-SR (preimplantation genetic testing for monogenic/structural rearrangement conditions) — within the ACP MediSave limits
Standard preparatory procedures that are part of the ACP cycle can also be covered. MediSave can be drawn from either the patient’s own account or the spouse’s account, giving couples flexibility if one partner has a higher balance.
Importantly, MediSave for fertility treatment is a separate withdrawal allowance from your annual hospitalisation withdrawals. Using it for IVF does not reduce what’s available for your shield plan deductible or other hospitalisation bills — a point many couples miss when planning for a family. For a full picture of how MediSave interacts with your hospitalisation coverage, see our MediSave hospitalisation step-by-step guide.
MediSave Withdrawal Limits per IVF Cycle (2026)
The table below sets out the MediSave withdrawal caps per ACP cycle. These limits apply whether you are treated at a public or MOH-approved private AR centre.
| Cycle Number | MediSave Per Cycle Cap | Lifetime Cap (Cumulative) |
|---|---|---|
| 1st cycle | S$6,000 | S$6,000 |
| 2nd cycle | S$5,000 | S$11,000 |
| 3rd cycle | S$4,000 | S$15,000 (lifetime cap reached) |
| 4th cycle onwards | S$0 (lifetime cap exhausted) | S$15,000 |
Source: Ministry of Health (MOH), Marriage and Parenthood Schemes, last updated 17 March 2026
Once you reach the S$15,000 lifetime cap, no further MediSave can be used for ACP cycles — regardless of cycle outcome. This cap is per patient (not per couple), and it applies across all public and private centres.
Government Co-Funding on Top of MediSave
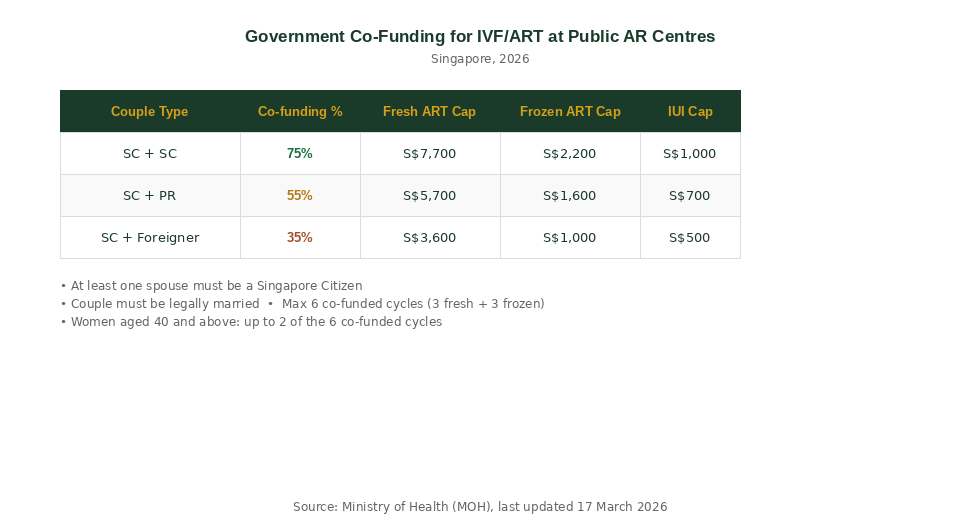
Couples treated at public AR centres (KKH, NUH, SGH) may qualify for government co-funding — a subsidy paid directly to the hospital that reduces your bill before you draw on MediSave. This is separate from, and additional to, your MediSave withdrawal.
Eligibility: at least one spouse must be a Singapore Citizen, and the couple must be legally married. Couples where only the spouse is an SC (but the patient is not) may still qualify under certain conditions.
| Couple Type | Co-Funding % | Fresh ART Cap | Frozen ART Cap | IUI Cap |
|---|---|---|---|---|
| SC + SC | 75% | S$7,700 | S$2,200 | S$1,000 |
| SC + PR | 55% | S$5,700 | S$1,600 | S$700 |
| SC + Foreigner | 35% | S$3,600 | S$1,000 | S$500 |
Source: Ministry of Health (MOH), last updated 17 March 2026. Co-funding is per cycle. Max 6 co-funded cycles: up to 3 fresh ART + 3 frozen ART cycles. For IUI: up to 3 co-funded cycles. Women aged 40 and above: up to 2 of the 6 co-funded ART cycles (provided ART was attempted before age 40).
MediSave for fertility treatment — especially the co-funding element — is effectively a government-backed subsidy scheme, quite different from how MediSave works for standard hospitalisation under the MediSave limit 2026. No application is needed; the co-funding is applied automatically at the point of billing.
Total Cost Breakdown: A Typical IVF Journey
To put the numbers in context, here is a worked example for a first-cycle fresh IVF at a public AR centre for a Singapore Citizen couple:
| Cost Component | Amount | Notes |
|---|---|---|
| Estimated total cycle cost (public) | ~S$12,000–S$14,000 | Includes stimulation, monitoring, retrieval, transfer, lab |
| Less: Government co-funding | −S$7,700 | SC+SC couple, fresh ART, 75% |
| Remaining after co-funding | ~S$4,300–S$6,300 | This is what you need to settle |
| Less: MediSave (1st cycle) | −S$6,000 | 1st cycle MediSave cap |
| Estimated out-of-pocket | S$0 – S$300 | Varies by hospital and exact procedure mix |
Note: Total cycle costs are estimates and vary by hospital and individual treatment plan. Medication costs (S$1,500–S$3,000) may be separate and are partly MediSave-claimable. Confirm exact figures with your AR centre.
At a private AR centre, government co-funding does not apply, but MediSave can still be used. Total costs at private centres typically range from S$15,000–S$25,000+ per fresh cycle, making out-of-pocket expenses significantly higher.
How Your Integrated Shield Plan Fits In
Your Integrated Shield Plan (ISP) may cover certain components of a fertility treatment cycle — but the interaction is narrower than many couples assume.
What your ISP may cover:
- Hospitalisation for egg retrieval — The egg retrieval procedure typically requires a short-stay admission, which can be claimed under your ISP as a day-surgery or inpatient admission. Standard deductibles and co-payments under your 2026 rider apply.
- Hospitalisation for complications — If you experience Ovarian Hyperstimulation Syndrome (OHSS) or other complications requiring admission, these are generally claimable under your ISP, subject to your ward class and plan limits.
- Pre-admission tests — Outpatient tests done within 30 days before an admissible hospitalisation are often claimable.
What your ISP typically does NOT cover:
- The IVF procedure itself as an outpatient fertility service (not a treatment of an acute illness)
- Fertility medications and hormone injections
- Embryo storage or cryopreservation fees
- IUI as an outpatient procedure
With the ISP rider changes in 2026, the co-payment rules for hospitalisation have shifted. If you do use your ISP for a related admission (e.g. egg retrieval theatre time), confirm with your insurer whether the admission type triggers the standard or mandatory 10% co-pay under the new rider framework.
For a deeper look at how MediSave works alongside your shield plan rider for hospitalisations, see the MediSave maternity package guide, which covers a parallel set of overlapping coverage rules.
What Is NOT Covered by MediSave
Not everything fertility-related is MediSave-eligible. Key exclusions as at 2026:
- Elective egg freezing (social freezing) — MediSave cannot be used for egg freezing done for non-medical reasons. Only medically indicated egg preservation (e.g., before chemotherapy) may be considered under specific circumstances.
- Sperm banking for non-medical reasons
- An ACP cycle not completed for non-medical reasons — If you abandon a cycle midway for personal reasons, MediSave cannot be used for it.
- Surrogacy — Commercial surrogacy is illegal in Singapore; MediSave does not cover surrogacy-related costs.
- MediSave beyond the lifetime cap — Once your S$15,000 lifetime limit is used, no further ACP claims are possible regardless of your current MediSave balance.
- Procedures at non-MOH-approved centres — MediSave only applies at approved public and private AR centres.
These exclusions mean that for couples embarking on a fertility journey, it is worth understanding the full picture of what your MediSave account, government subsidies, and ISP each cover — and budgeting accordingly for the gaps.
5 Practical Tips for Fertility Treatment Cost Planning
1. Use your MediSave strategically across cycles. Since the per-cycle cap drops from S$6,000 to S$5,000 to S$4,000, your MediSave goes furthest in the earlier cycles. If you have multiple options, maximise the first-cycle MediSave draw at the public centre where the government co-funding is also highest.
2. Pool from your spouse’s MediSave. Both partners’ MediSave accounts can contribute to the same cycle. If one partner has a low balance, drawing from the other can close the gap — both still subject to the same per-cycle cap.
3. Confirm co-funding eligibility before you start. Public AR centres will apply co-funding automatically at billing, but it’s worth checking your age (women must be under 40 at cycle start, with limited exceptions) and citizenship status beforehand.
4. Plan around the 2026 MediSave Basic Healthcare Sum. Your MediSave balance is subject to the MediSave limit 2026 rules. CPF contributions above the Basic Healthcare Sum (BHS) flow to your Special Account. Having a healthy MediSave balance before starting treatment ensures you have the liquidity to cover the per-cycle caps without drawing cash out of pocket.
5. Keep your ISP active throughout treatment. Even if the IVF procedure itself is not covered, your ISP provides a crucial safety net for hospitalisations — including the egg retrieval admission and any complications. Letting your shield plan lapse during a fertility treatment cycle leaves you exposed. If you have questions about your rider structure, our integrated shield plan Singapore guide explains the 2026 rider framework in detail.
Frequently Asked Questions
How much MediSave can I use for IVF in Singapore?
You can use up to S$6,000 for the first IVF/ART cycle, S$5,000 for the second cycle, and S$4,000 from the third cycle onwards. The lifetime MediSave cap for fertility treatment is S$15,000 per patient. These limits apply regardless of whether you are treated at a public or MOH-approved private AR centre. MediSave can be drawn from your own account or your spouse’s account.
Does the government co-funding apply at private IVF clinics?
No. Government co-funding (up to 75% for a Singapore Citizen couple) only applies at the three public AR centres: KKH, NUH, and SGH. At private AR clinics, MediSave can still be used (up to the per-cycle caps) but there is no government subsidy on top. This is why public centre treatment can cost significantly less out-of-pocket for a first cycle.
Can I use MediSave for IVF if my spouse is a Permanent Resident, not a Citizen?
Yes, in two ways. First, MediSave can be used by either spouse at any MOH-approved centre, so both a Citizen and a PR can contribute their MediSave. Second, an SC + PR couple qualifies for government co-funding at public AR centres — but at a lower rate of 55% (vs 75% for an SC + SC couple), with a fresh ART cap of S$5,700.
Does using MediSave for fertility treatment affect my ISP premiums or deductible?
No. The MediSave limit for Assisted Conception Procedures (ACPs) is a separate withdrawal allowance from the standard hospitalisation MediSave withdrawals. Using it for IVF does not reduce what’s available for your ISP deductible or affect your premium payments. These are entirely separate pots within the same MediSave account.
Is the egg retrieval procedure covered by my Integrated Shield Plan?
It may be, partially. The egg retrieval is typically performed as a day-surgery or short-stay inpatient procedure, which falls within the type of admission your ISP covers. However, the ART procedure itself (IVF, lab work, embryo transfer) is usually not covered by ISP as it is a fertility service rather than treatment for an acute medical condition. Confirm with your insurer based on your specific plan and rider before the admission.
What happens to my unused MediSave lifetime cap if my IVF cycles succeed early?
Your unused ACP MediSave lifetime cap does not expire or carry over as a general balance — it simply stays unused, and your overall MediSave account retains those funds. For example, if you succeed on the first cycle and use S$6,000, the remaining S$9,000 of the S$15,000 lifetime cap is still available should you need further cycles in the future. The cap counts cumulative usage, not entitlement.
This article is for informational purposes only and does not constitute financial, medical, or legal advice. MediSave limits, co-funding rates, and ISP rules are subject to change. Always confirm current figures with CPF Board, MOH, and your insurer before making decisions. Data verified as at 7 November 2026.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.