Endowment Plan Free Look Period Singapore 2026: What You Can Cancel (And What It Costs You)
📋 Table of Contents
The free look period for an endowment plan in Singapore is a 14-day window — starting from when you receive your policy documents — during which you can cancel the policy and receive a full refund of premiums paid. After these 14 days, early cancellation triggers surrender charges that can cost you 10–15% or more of your premiums in Year 1. Here’s exactly what to check, and how to use your free look window wisely before it closes.
Not financial advice. All figures are for educational reference only. Data verified as at October 2026.
What Is the Free Look Period for Endowment Plans?
The free look period — also called the cooling-off period — is a mandatory right given to insurance policyholders in Singapore under the Life Insurance Association (LIA) guidelines. Every endowment plan sold in Singapore must offer at least a 14-day free look window.
During this window, you can cancel your endowment policy for any reason — even if you simply changed your mind — and receive a refund of the premiums you paid. This protection exists because endowment plans are long-term, illiquid commitments (typically 5 to 25 years), and regulators want consumers to have a last chance to review before they’re truly locked in.
The free look period is not the same as a “refund guarantee.” Depending on the insurer, a small deduction may be made for:
- Risk charges for the coverage period — the cost of life insurance protection while the policy was active
- Medical examination costs — if you underwent a medical exam as part of underwriting
- Investment losses — for unit-linked endowment or ILP components, if the sub-fund value fell during the free look period
In practice, for most straightforward endowment plans with short free look durations, refunds are close to 100% of premiums paid — but always check your specific policy contract or Product Highlights Sheet (PHS) for the exact terms.
If you’re still evaluating whether an endowment plan is right for you, it helps to understand the difference between an endowment plan and whole life insurance, as these have different free look and surrender structures.
How the 14-Day Clock Works
Many policyholders make the mistake of counting 14 days from the date they signed the application form. That’s wrong — and could cause you to miss your window.
The free look period starts from the day you receive your policy documents, not the date of purchase or policy commencement. This is a critical distinction.
| Event | Date (Example) | Notes |
|---|---|---|
| Application signed | 1 October | Policy not yet active |
| Policy commencement date | 5 October | Coverage begins |
| Policy documents received | 10 October | Free look period starts here |
| Free look deadline | 24 October | Last day to cancel penalty-free |
| After 24 October: Surrender charges apply. | ||
Source: LIA Singapore guidelines, insurer policy contracts. Example dates for illustration only.
Some tips to protect yourself:
- Note the date you physically receive or download the policy documents
- Take a screenshot or photograph of the delivery date (email timestamp, courier receipt)
- Some insurers send documents electronically — the email timestamp counts
- If you’re unsure when the period started, call your insurer immediately to confirm
If you’ve been considering par vs non-par endowment plans, note that par plans may have longer free look review periods — check your specific PHS.
What You Get Back When You Cancel During Free Look
Most Singaporeans assume they get 100% of their premiums back during the free look period. For the majority of straightforward endowment plans, this is roughly correct — but the exact refund depends on your specific policy terms.
| Plan Type | Refund Amount | Possible Deductions |
|---|---|---|
| Short-term endowment (1–5 yr) | Full premium refund | Usually none |
| Long-term par endowment (10–25 yr) | Full premium, minus risk charges | Cost of coverage for days active |
| Medically underwritten plan | Full premium, minus exam cost | Medical exam fee (if any) |
| Unit-linked / ILP component | Fund value (may be lower) | Market movement during 14 days |
Source: LIA Singapore, Manulife and FWD product summaries, MoneySense.gov.sg. Data as at October 2026.
The key takeaway: for most Singapore endowment plans (especially fixed-term, non-participating plans), you’ll get close to 100% back during the free look period. Compare this to what happens after the free look period closes — where surrender penalties can be substantial. This is why understanding your endowment plan’s break-even timeline before signing is so critical.
How to Cancel Your Endowment Plan: Step-by-Step
If you’ve decided to cancel within your free look period, act quickly. Here’s the standard process:
Step 1: Write a cancellation letter
Prepare a formal written notice stating: your full name, NRIC, policy number, policy commencement date, and your instruction to cancel under the free look provision. You don’t need to give a reason.
Step 2: Choose your delivery method
Most Singapore insurers accept cancellation via:
- Registered mail — send to the insurer’s head office; keep your postage receipt
- Email with read receipt — send to your insurer’s customer service email (check your PHS)
- Walk-in at branch — bring your NRIC, policy documents, and request written acknowledgment
- Via your financial adviser — they can submit on your behalf, but ensure you get a copy
Step 3: Keep proof of submission
The 14-day deadline is based on when you send your cancellation — not when the insurer processes it. Keep your registered mail receipt, email read receipt, or branch acknowledgment slip.
Step 4: Wait for refund processing
Most insurers process free look refunds within 5–14 business days. Refunds are typically made via cheque or bank transfer to the original payment method.
Step 5: Confirm the refund amount
When you receive confirmation, compare it to your premium paid. If there are any deductions, ask the insurer to itemize them.
What Happens After the Free Look Period? (Surrender Charges Explained)
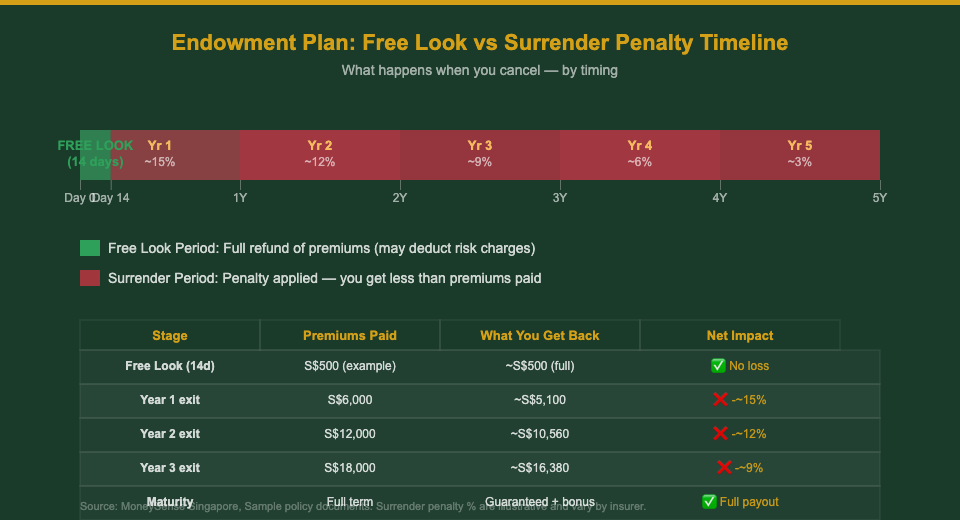
Once your 14-day free look window closes, you’re committed to the policy. If you need to exit early, you’ll face surrender charges — a penalty designed to recover the insurer’s acquisition costs (agent commissions, underwriting costs) that were front-loaded at policy inception.
Surrender charges are highest in Year 1 and decline each year until they disappear at maturity. The exact schedule varies by insurer and product, but the general structure for a Singapore long-term endowment plan looks like this:
Surrender Charges by Policy Year
| Policy Year | Typical Surrender Value | Effective Penalty on Premiums | Example (S$500/month plan) |
|---|---|---|---|
| Free Look | ~100% of premiums | Zero | Full S$500 refunded |
| Year 1 | ~0–85% of premiums paid | ~15–100% loss | ~S$0–S$5,100 of S$6,000 |
| Year 2 | ~65–88% of premiums paid | ~12–35% loss | ~S$7,800–S$10,560 |
| Year 3 | ~80–91% of premiums paid | ~9–20% loss | ~S$14,400–S$16,380 |
| Year 5 | ~94–97% of premiums paid | ~3–6% loss | ~S$28,200–S$29,100 |
| Break-even year | 100%+ of premiums paid | Zero | Typically Year 7–12 (varies) |
Source: Indicative range based on published Singapore endowment plan product summaries from Great Eastern, Manulife, and Etiqa. Actual surrender values vary significantly by product. Check your policy’s Guaranteed Surrender Value table. Data as at October 2026.
This table illustrates why the free look period is so valuable. Once you’re past Day 14, even exiting in Year 1 can mean losing 15–100% of your first year’s premiums.
A Singapore retirement calculator can help you compare how different savings vehicles — endowment plans, SSBs, CPF top-ups — stack up for your retirement goals, before you commit to anything.
Key Documents to Review During Your 14-Day Free Look Period
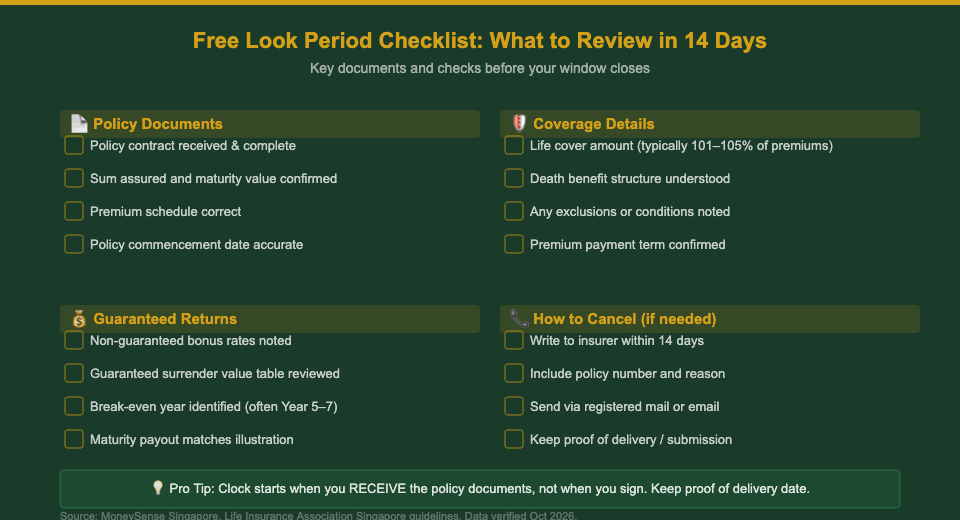
Don’t spend your 14 days agonising — spend them reviewing these specific items to confirm the plan actually delivers what was sold to you:
1. Product Highlights Sheet (PHS)
The PHS is a standardised MAS-regulated summary. Check: whether your policy is a participating or non-participating plan, the guaranteed versus non-guaranteed portions of your maturity benefit, and the key exclusions.
2. Benefit Illustration (BI)
The BI shows projected returns under two scenarios (typically 4.25% and 3.25% illustrated investment rates for par plans). Crucially, check the “Guaranteed Surrender Value” table — this shows exactly what you’d get back in each year if you had to exit early.
3. Policy Contract
The full policy contract is the legally binding document. Verify: premium amount, premium payment term, policy term, sum assured, and any riders attached. Confirm these match what your financial adviser presented.
4. Free Look Period Terms
Your policy contract should have a section specifically about the free look period. Find it and note: the exact duration (should be at least 14 days), how to exercise it, and what deductions apply.
For endowment plans that are structured around participating funds, it’s also worth understanding how the par fund’s bonus rates affect your guaranteed vs non-guaranteed returns before you commit past Day 14.
Common Mistakes Singapore Policyholders Make
| Mistake | Why It Matters | What to Do Instead |
|---|---|---|
| Counting from application date | Free look starts from document receipt, not signing | Record the document delivery date immediately |
| Assuming verbal cancellation is enough | Phone calls are not legally binding for policy cancellation | Always send written notice |
| Not keeping delivery proof | Without proof, insurers can dispute timeliness | Keep registered mail receipt or email read receipt |
| Waiting to “think about it” | 14 days is shorter than it seems, especially with weekends | Review documents within 48 hours of receipt |
| Relying only on adviser’s summary | Advisers may not highlight surrender charges prominently | Read the Guaranteed Surrender Value table yourself |
Source: Compiled from MoneySense Singapore guidance and policyholder community discussions, October 2026.
If you ultimately decide to stay in your endowment plan, consider using the retirement planning calculator to model whether your policy’s maturity payout aligns with your long-term savings goals. If not, you still have options including Endowus for CPF and SRS investing or Syfe’s managed portfolios as more liquid alternatives.
Frequently Asked Questions: Endowment Plan Free Look Period Singapore
How long is the free look period for endowment plans in Singapore?
The free look period for endowment plans in Singapore is a minimum of 14 days, as mandated by the Life Insurance Association (LIA) Singapore. The 14-day window starts from the date you receive your policy documents — not the date of application or policy commencement. Some insurers may offer longer windows, so check your specific policy contract or Product Highlights Sheet. After 14 days, surrender charges apply if you wish to exit early.
Do I get a full refund if I cancel during the free look period?
For most Singapore endowment plans, you’ll receive close to a full refund of premiums paid during the free look period. However, the exact amount depends on your insurer and policy type. Possible deductions include: (1) risk charges for the coverage period while the policy was active, (2) medical examination costs if underwriting was involved, or (3) for unit-linked components, any investment losses during the free look period. Always check your policy’s specific free look refund terms in your Product Highlights Sheet or policy contract.
Can I cancel my endowment plan after the free look period?
Yes, you can cancel (surrender) your endowment plan at any time after the free look period — but surrender charges will apply. These penalties are highest in the early years (Year 1 can mean losing 15–100% of premiums paid, depending on the plan) and gradually reduce each year. Most endowment plans break even — where your surrender value equals total premiums paid — somewhere between Year 7 and Year 12.
What if I received the policy documents by email — when does the 14 days start?
If your policy documents were delivered electronically (via email), the 14-day free look period typically starts from the email’s timestamp — i.e., when you received the email. Save this email as it serves as your record of the delivery date. If you’re unsure whether a digital delivery counts, call your insurer directly to confirm.
Do I need to give a reason for cancelling during free look?
No. During the free look period, you can cancel your endowment plan for any reason — or no reason at all. It is a no-questions-asked right guaranteed to you under LIA Singapore guidelines. You simply need to submit your cancellation in writing within the 14-day window.
What is the difference between the free look period and the grace period?
These are two separate protections. The free look period (14 days from document receipt) allows you to cancel a new policy and get your premiums refunded — it’s about changing your mind after purchase. The grace period is different: it’s typically a 30-day window after a premium due date during which you can make a late payment without losing your policy coverage. Both are consumer protections, but they apply to completely different situations.
Should I buy an endowment plan or explore other savings options?
An endowment plan suits you if: (1) you want disciplined, long-term forced savings with guaranteed returns, (2) you have a specific financial goal (e.g., a child’s education fund in 15 years), and (3) you’re comfortable with the illiquidity. If you want more flexibility, consider Singapore Savings Bonds (SSBs), CPF top-ups, or robo-advisers like Syfe and Endowus. Use a retirement calculator to model which option fits your timeline and goals.
The Bottom Line
The 14-day free look period is your most powerful — and time-limited — right as an endowment plan policyholder in Singapore. Use it as a final verification window, not a passive waiting period. Review your policy contract, confirm the Guaranteed Surrender Value table, and make sure the plan genuinely fits your timeline and financial goals.
If anything doesn’t match what was explained to you at point of sale, this is your chance to walk away at zero cost. After Day 14, those same issues become expensive lessons.
Already past your free look period? You still have options — including comparing more liquid alternatives through Syfe and Endowus for your future savings goals.
This article is for educational purposes only and does not constitute financial advice. Please consult a licensed financial adviser before making insurance or investment decisions. Data verified as at October 2026.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.