Mapletree Logistics Trust Dividend History 2012–2026: DPU Track Record & Yield on Cost Analysis (SGX: M44U)
Updated: October 2026 · S-REIT Dividend Guide · SGX: M44U
Mapletree Logistics Trust (SGX: M44U) has paid uninterrupted quarterly distributions since its 2005 IPO, growing its annual DPU from 6.55 SGD cents in FY2013 to a record 9.014 cents in FY2023 before retreating to approximately 7.80 cents in FY2025 due to Japanese yen headwinds and China portfolio restructuring. This article presents the complete MLT dividend history, yield on cost at different entry prices, distribution schedule, and 2026 outlook for Singapore income investors.
Not financial advice. DPU data sourced from Mapletree Logistics Trust Annual Reports and SGX filings. Estimates clearly labelled. Data as at October 2026 unless otherwise noted.
Table of Contents
- What Is Mapletree Logistics Trust (M44U)?
- Key Facts at a Glance
- MLT Dividend History 2013–2026: Full Annual DPU Table
- Yield on Cost Analysis: What Early Investors Earn Today
- Factors Affecting MLT’s DPU in 2026
- MLT Distribution Schedule and Payment Dates
- Should You Buy MLT for Dividends in 2026?
- Frequently Asked Questions
What Is Mapletree Logistics Trust (M44U)?
Mapletree Logistics Trust (SGX: M44U) is a logistics-focused Singapore REIT that owns and manages warehouses, distribution centres, and cold-storage facilities across nine countries in Asia Pacific: Singapore, China, Japan, Hong Kong, South Korea, Australia, Malaysia, Vietnam, and India. Managed by Mapletree Logistics Trust Management Ltd — a wholly-owned subsidiary of Mapletree Investments Pte Ltd — MLT has grown from a Singapore-focused REIT at its 2005 IPO to one of Asia’s largest logistics real estate platforms, with over 180 properties and approximately SGD 13–14 billion in assets under management as at 2026.
MLT earns rental income from logistics tenants including manufacturers, third-party logistics (3PL) providers, e-commerce fulfilment operators, and FMCG companies, distributing the majority of this income to unitholders each quarter. For investors building a passive income portfolio in Singapore, MLT’s 20-year listing history and geographic diversification make it one of the most widely tracked S-REITs among the best S-REITs in Singapore 2026.
Key Facts at a Glance
| Attribute | Detail |
|---|---|
| SGX Code | M44U |
| Listed Date | 28 July 2005 |
| REIT Manager | Mapletree Logistics Trust Management Ltd |
| Sponsor | Mapletree Investments Pte Ltd |
| Financial Year End | 31 March (FY = 1 April – 31 March) |
| Distribution Frequency | Quarterly (4 distributions per year) |
| Gearing (FY2026E) | ~38–40% |
| Assets Under Management | ~SGD 13–14 billion |
| No. of Properties (2026) | ~180+ |
| Countries | SG, CN, JP, HK, KR, AU, MY, VN, IN |
| IPO Price | SGD 0.68 per unit |
| Approx. Price (Oct 2026) | ~SGD 1.28–1.35 |
| FY2025 DPU (estimated) | ~7.80 SGD cents (annualised) |
| Forward Yield (at SGD 1.30) | ~6.0% |
Source: SGX, MLT Annual Reports, The Kopi Notes estimates. Data as at October 2026.
MLT Dividend History 2013–2026: Full Annual DPU Table
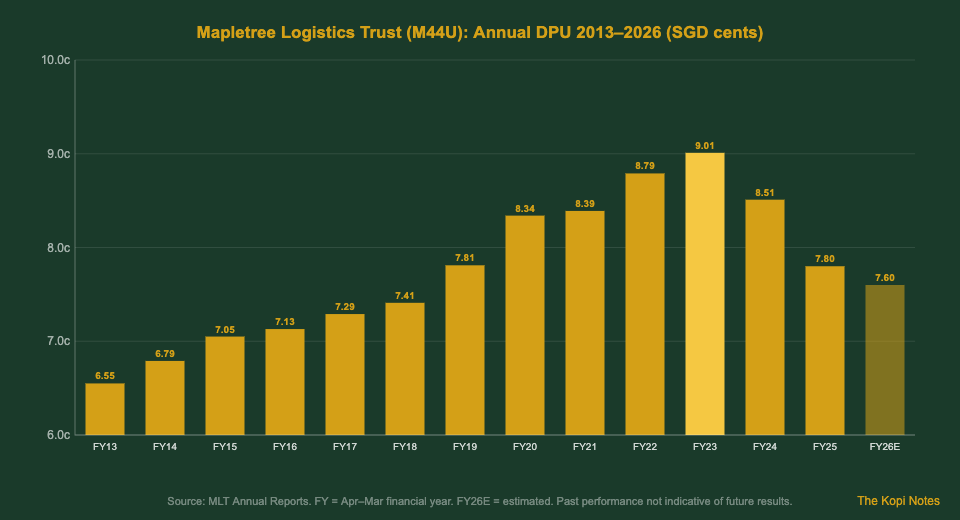
The table below shows Mapletree Logistics Trust’s annual DPU from FY2013 to FY2026. Figures represent the full-year DPU (sum of all four quarterly distributions). MLT’s financial year runs 1 April to 31 March, so FY2013 covers April 2012 to March 2013.
MLT achieved ten consecutive years of DPU growth from FY2013 to FY2023, a streak interrupted only from FY2024 when JPY depreciation, China portfolio headwinds, and rising interest costs converged. The all-time high of 9.014 cents was reached in FY2023. Current DPU compression is widely regarded as cyclical rather than structural, given MLT’s high occupancy and the ongoing structural growth in Asia Pacific e-commerce logistics.
| Financial Year | Annual DPU (SGD cents) | Change YoY | Key Context |
|---|---|---|---|
| FY2013 (Apr 12–Mar 13) | 6.55 | — | Base year; SG-focused portfolio |
| FY2014 (Apr 13–Mar 14) | 6.79 | +3.7% | Portfolio expansion; AU entry |
| FY2015 (Apr 14–Mar 15) | 7.05 | +3.8% | Vietnam & India acquisitions |
| FY2016 (Apr 15–Mar 16) | 7.13 | +1.1% | China headwinds; SG robust |
| FY2017 (Apr 16–Mar 17) | 7.29 | +2.2% | Recovery; HK/KR expansion |
| FY2018 (Apr 17–Mar 18) | 7.41 | +1.6% | Capacity growth in AU & JP |
| FY2019 (Apr 18–Mar 19) | 7.81 | +5.4% | India established; strong leasing |
| FY2020 (Apr 19–Mar 20) | 8.34 | +6.8% | COVID-19 e-commerce logistics boom |
| FY2021 (Apr 20–Mar 21) | 8.39 | +0.6% | AUM crossed SGD 10 billion |
| FY2022 (Apr 21–Mar 22) | 8.787 | +4.8% | Post-COVID logistics peak |
| FY2023 (Apr 22–Mar 23) | 9.014 | +2.6% | 🏆 All-time high DPU |
| FY2024 (Apr 23–Mar 24) | 8.514 | −5.5% | JPY depreciation; China weakness |
| FY2025 (Apr 24–Mar 25) | ~7.80 (est.) | −8.4% (est.) | China disposals; debt cost headwinds |
| FY2026E (Apr 25–Mar 26) | ~7.60 (est.) | −2.6% (est.) | Stabilisation; India & Vietnam offset |
Source: Mapletree Logistics Trust Annual Reports. FY2025 estimated from H1 disclosed results + H2 estimate. FY2026E = full-year estimate. Past DPU is not a guarantee of future distributions.
Yield on Cost Analysis: What Early Investors Earn Today
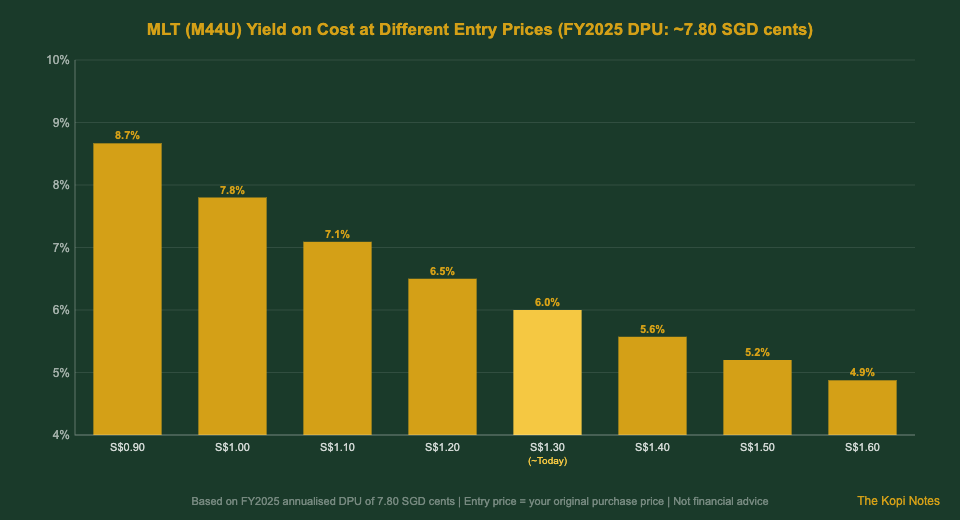
Yield on cost is the annual income you receive relative to what you originally paid, not today’s market price. Investors who accumulated MLT units below SGD 1.00 in the early post-IPO years now earn a double-digit yield on their cost basis — a powerful illustration of the compounding effect of holding quality income REITs through market cycles.
The table below shows yield on cost at different purchase prices, using an estimated FY2025 annualised DPU of ~7.80 SGD cents. To model how REIT distributions compound over time, use our Singapore retirement planning calculator.
| Original Entry Price (S$) | FY2025 DPU (~7.80c) | Yield on Cost | Notes |
|---|---|---|---|
| S$0.68 (IPO, July 2005) | 7.80c | 11.5% | IPO investors: exceptional long-term yield |
| S$0.80 | 7.80c | 9.8% | Early 2006–2010 range |
| S$0.90 | 7.80c | 8.7% | Pre-2015 entry |
| S$1.00 | 7.80c | 7.8% | Pre-COVID rally entry |
| S$1.10 | 7.80c | 7.1% | Strong long-term income yield |
| S$1.20 | 7.80c | 6.5% | 2018–2019 accumulation range |
| S$1.30 (~Today) | 7.80c | 6.0% | → Current approximate market yield |
| S$1.40 | 7.80c | 5.6% | Post-peak recovery entry |
| S$1.60 | 7.80c | 4.9% | Near 2020 COVID highs |
| S$1.80 | 7.80c | 4.3% | Mid-2021 range (rate fear era) |
| S$2.00 | 7.80c | 3.9% | Near all-time price highs (2021) |
Based on FY2025 estimated annualised DPU ~7.80 SGD cents. Entry price = original purchase price. Yield on cost is not a forecast of future income. Not financial advice.
Factors Affecting MLT’s DPU in 2026
1. Japanese Yen Depreciation
Japan is MLT’s second-largest market by asset value (~20–25% of portfolio). JPY/SGD depreciation directly reduces the SGD value of Japan rental income. This has been the single largest headwind on MLT’s DPU since FY2024. Any JPY recovery would be a significant positive catalyst for distributions.
2. China Portfolio Restructuring
MLT has been strategically divesting lower-yielding China properties and redeploying capital into higher-quality assets in Japan, Australia, and India. While short-term disposals reduce income, they improve the portfolio’s long-run quality. China’s domestic logistics demand also softened materially post-2022.
3. Rising Financing Costs
MLT’s cost of debt rose as fixed-rate loans were refinanced at higher market rates during 2023–2025. With gearing at ~38–40%, interest expense is material. As global rates stabilise or decline, this headwind is expected to moderate from FY2026 onwards.
4. E-Commerce and 3PL Demand (Structural Tailwind)
Despite income headwinds, MLT’s occupancy has remained strong (>95% in Singapore, Japan, South Korea, and Australia). E-commerce penetration continues to rise across Asia, supporting long-term demand for MLT’s distribution centres. This demand tailwind underpins confidence in DPU stability at current levels.
5. India and Vietnam Growth
MLT’s India and Vietnam portfolios — both entered in 2019 — offer higher rental growth than mature markets. Continued investment in these markets provides a DPU growth engine for the medium term, partially offsetting China and JPY headwinds.
MLT Distribution Schedule and Payment Dates
MLT pays quarterly distributions. The ex-dividend date and payment date are announced via SGX each quarter. Typical timing is as follows (check SGX for exact dates each quarter):
| Quarter | Period Covered | Results Month | Payment Month |
|---|---|---|---|
| Q1 | Apr–Jun | July | ~Aug/Sep |
| Q2 (H1 results) | Jul–Sep | Oct/Nov | ~Nov |
| Q3 | Oct–Dec | Jan | ~Feb |
| Q4 (Full Year) | Jan–Mar | Apr/May | ~May |
Dates are indicative. Always verify ex-date and payment date via SGX announcements before trading to ensure you hold units by the record date.
Should You Buy MLT for Dividends in 2026?
At an approximate price of SGD 1.28–1.35 and estimated FY2025 DPU of ~7.80 cents, MLT offers a forward yield of approximately 5.8–6.1%. Compared to Singapore T-bills (~3.5–4.0%) or bank fixed deposits (~2.8–3.4%), MLT provides a yield premium of roughly 2.0–2.5 percentage points for taking on REIT risk.
MLT’s long-term investment case rests on: (1) 20+ years of uninterrupted quarterly distributions; (2) a quality sponsor (Mapletree Investments) with a proven pipeline injection track record; (3) structural e-commerce demand tailwind across Asia Pacific; and (4) geographic diversification reducing single-market concentration risk. The near-term DPU headwinds from JPY and China appear cyclical rather than permanent.
Investors may wish to compare MLT against other industrial S-REITs. Mapletree Industrial Trust (MIT) offers exposure to Singapore data centres and flatted factories; Keppel DC REIT (AJBU) focuses purely on data centres. For a broader income strategy, pairing MLT with higher-yield retail or hospitality REITs is a common approach among investors referenced in our guide to the best S-REITs in Singapore 2026.
If you are investing through a robo-advisor, Syfe (referral code SRPRFFFCD) and Endowus (referral code 2V343) both offer REIT portfolios that include M44U. For direct stock purchase at competitive commissions, FSMOne (P0544985) is a popular SGX brokerage choice among Singapore retail investors.
Frequently Asked Questions: MLT Dividend History
What is Mapletree Logistics Trust’s current dividend yield?
At approximately SGD 1.28–1.35 per unit in October 2026, Mapletree Logistics Trust (M44U) offers a forward dividend yield of approximately 5.8–6.1%, based on an estimated FY2025 annualised DPU of ~7.80 SGD cents. The actual yield fluctuates with the unit price and quarterly DPU announcements. Always check the latest SGX filing for the most recent declared DPU before making investment decisions.
How often does Mapletree Logistics Trust pay dividends?
MLT pays distributions quarterly — four times per year. Each payment covers a three-month period: Q1 (April–June), Q2 (July–September), Q3 (October–December), and Q4 (January–March). Payments are typically made one to two months after each quarter closes. This makes MLT one of Singapore’s most frequent income-paying REITs, appealing to investors building a passive income stream in Singapore.
What is MLT’s financial year and how does it affect the DPU data?
MLT’s financial year runs from 1 April to 31 March. So FY2026 covers 1 April 2025 to 31 March 2026, and FY2013 covers April 2012 to March 2013. This differs from the calendar year. When reading DPU tables, note whether figures refer to a financial year (Apr–Mar) or calendar year. Full-year results including the final DPU announcement are typically released in May or June following each financial year end.
Has Mapletree Logistics Trust ever cut its DPU?
MLT achieved 10 consecutive years of DPU growth from FY2013 to FY2023, without a single cut even during the COVID-19 pandemic. In fact, DPU grew in FY2020 and FY2021 as logistics demand surged. The DPU declined in FY2024 (−5.5%) and is estimated to have fallen further in FY2025 (~−8%), primarily due to Japanese yen depreciation and higher debt financing costs, not from falling occupancy or tenant issues. Management has not suspended distributions. The pullback is widely considered cyclical.
Is Mapletree Logistics Trust suitable for retirement income?
MLT is frequently held by Singapore retirement-oriented investors for its quarterly income, geographic diversification, and long track record. At ~6% forward yield, it offers a meaningful premium over risk-free alternatives. However, as a REIT, MLT’s unit price and DPU are not guaranteed. Key risks include JPY/AUD/CNY currency exposure, interest rate risk on borrowings, and China market uncertainty. Investors should consult the Singapore retirement calculator to model sustainable withdrawal scenarios incorporating REIT income. This is not financial advice.
How does MLT compare to Mapletree Industrial Trust (MIT) and Keppel DC REIT for dividends?
MLT (M44U), Mapletree Industrial Trust (MIT, ME8U), and Keppel DC REIT (AJBU) are all popular Singapore industrial REITs. In 2026, MLT at ~SGD 1.30 offers the highest forward yield (~6.0%), reflecting greater JPY and China exposure. MIT at ~SGD 2.10–2.20 offers ~5.5–5.8%, backed by its Singapore data centre portfolio. Keppel DC REIT at ~SGD 2.10–2.30 offers ~4.5–5.0% as a pure-play data centre REIT. For detailed comparisons, see our guide to the best S-REITs in Singapore 2026.
Invest in MLT and Other S-REITs
Use these platforms to buy M44U and other Singapore REITs. Sign up with our referral codes for welcome bonuses:
Syfe REIT+: SRPRFFFCD · Endowus: 2V343 · FSMOne: P0544985
Not financial advice. Referral links may earn The Kopi Notes a commission at no additional cost to you.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.