Income Travel Insurance Review 2026: Per-Trip vs Yearly Plans, Coverage and Promos
What Income’s Standard travel plans cover, what they cost, and how to tell whether a yearly plan beats buying per trip, flash sales included.
Income’s Standard travel insurance comes in three tiers, Classic, Deluxe and Preferred, sold per trip or as a yearly plan. Coverage is solid, with overseas medical cover from S$350,000 up to unlimited. A yearly plan only pays off if you travel often enough: because Income runs frequent per-trip flash sales, most people need four or more trips a year before yearly wins.
Not financial advice. Figures are for educational reference only. Data as at October 2026 unless noted. TKN may earn a commission if you buy through our Income links, at no extra cost to you.
Table of Contents
Contents (click to expand)
- Income travel insurance plans at a glance
- Coverage by tier: Classic vs Deluxe vs Preferred
- How much Income travel insurance costs
- Per-trip vs yearly: how to work out which is cheaper
- Current Income travel insurance promotions
- Watch-outs before you buy
- Our verdict: who Income travel insurance suits
- Frequently asked questions
Income travel insurance plans at a glance
Income (formerly NTUC Income) is one of Singapore’s biggest insurers, and its travel insurance is among the most searched in the country. Its main product is the Standard travel plan, which comes in three tiers: Classic, Deluxe and Preferred.
You can buy each tier for a single trip or as a yearly plan that covers every trip you take in 12 months. Income also sells Enhanced PreX, a separate plan for travellers with pre-existing medical conditions.
| Per-trip plan | Yearly plan | |
|---|---|---|
| Tiers | Classic, Deluxe, Preferred | Classic, Deluxe, Preferred Yearly |
| Trips covered | One trip | Unlimited trips in 12 months |
| Maximum length of each trip | Up to 180 days | Up to 90 days per trip |
| Cancelling after the start date | No premium refund | 85% of the unused premium refunded if cancelled within 180 days and no claim made |
| Changing the policy | S$10.90 admin charge; promo discount no longer applies | S$10.90 admin charge; promo discount no longer applies |
Source: Income travel insurance page and promotion T&Cs, October 2026
The yearly plan’s refund rule is worth knowing. If your plans change, you can cancel within 180 days and get 85% of the unused premium back, as long as you have not claimed. Per-trip plans give no refund once the trip has started.
Coverage by tier: Classic vs Deluxe vs Preferred
All three tiers cover the essentials. The main differences are the limits on medical bills, cancellations and lost bags.
| Benefit (adult under 70, per trip) | Classic | Deluxe | Preferred |
|---|---|---|---|
| Overseas medical expenses | S$350,000 | S$800,000 | Unlimited |
| Personal accident | S$150,000 | S$200,000 | S$500,000 |
| Trip cancellation | S$5,000 | S$10,000 | S$15,000 |
| Travel delay | S$1,000 | S$1,500 | S$2,000 |
| Loss or damage of baggage | S$3,000 | S$5,000 | S$8,000 |
Source: Income Standard travel insurance coverage, income.com.sg, October 2026
For trips within ASEAN, Classic’s S$350,000 medical cover is enough for most people. For Japan, the US, Europe or Australia, where hospital bills run much higher, Deluxe or Preferred gives a bigger buffer.
Preferred also has two extras. It covers cancelling, postponing or shortening a trip for any reason, with a 50% co-payment, and its travel and baggage delay limits go up to S$2,000.
How much Income travel insurance costs
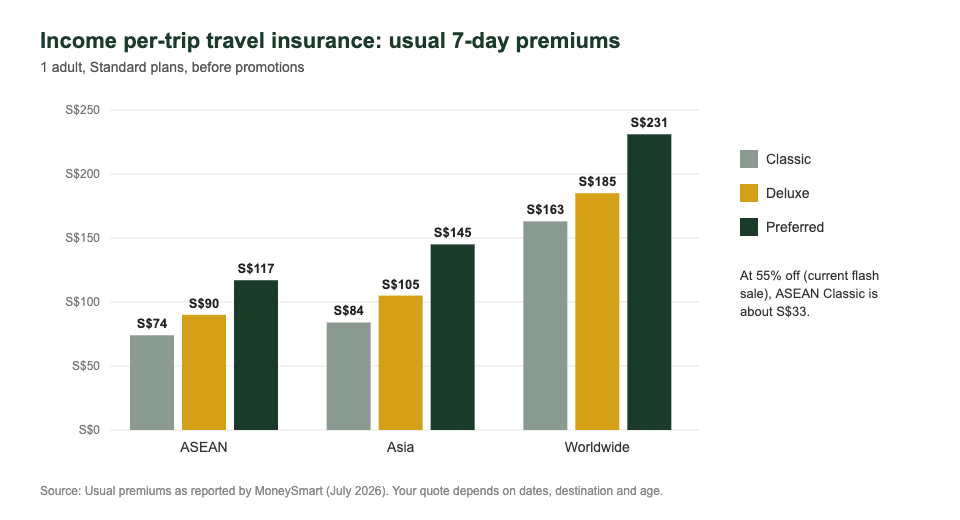
Income does not publish a premium table, so the price depends on your quote. As a guide, MoneySmart reported these usual prices for a 7-day trip in July 2026.
| Region (7-day trip, 1 adult) | Classic | Deluxe | Preferred |
|---|---|---|---|
| ASEAN | S$74 | S$90 | S$117 |
| Asia | S$84 | S$105 | S$145 |
| Worldwide | S$163 | S$185 | S$231 |
Source: Usual (undiscounted) per-trip premiums as reported by MoneySmart, July 2026. Your quote depends on dates, destination and age
Those are the undiscounted prices. Income often runs per-trip promotions, and the current flash sale takes 55% off Standard per-trip plans. At that rate, a 7-day ASEAN Classic plan comes to about S$33.
Per-trip vs yearly: how to work out which is cheaper
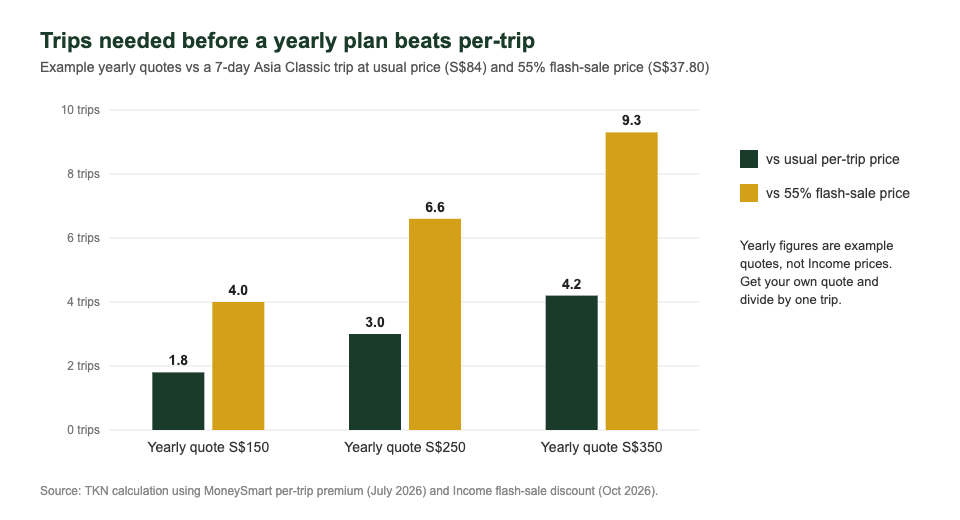
The question most people ask is whether yearly travel insurance is worth it. The answer is a simple sum: divide the yearly premium by what you would pay for one trip. If you take more trips than that a year, yearly wins.
The catch is the per-trip price you compare against. Income runs per-trip flash sales several times a year, and if you always buy during one, a single trip costs less than half the usual price. That pushes the break-even point much higher.
| Your yearly plan quote (after discount) | Trips to break even at usual per-trip price (S$84) | Trips to break even at a 55% flash-sale price (S$37.80) |
|---|---|---|
| S$150 | 1.8 trips | 4.0 trips |
| S$250 | 3.0 trips | 6.6 trips |
| S$350 | 4.2 trips | 9.3 trips |
Source: TKN calculation using a 7-day Asia Classic per-trip premium of S$84 (MoneySmart, July 2026). Yearly figures are example quotes, not Income prices. October 2026
Say your yearly quote, after the current 25% discount, is S$250. Against the usual price, three Asia trips a year make it worth it. Against flash-sale prices, you would need about seven.
Yearly plans still make sense if you travel four or more times a year, take spontaneous weekend trips to Malaysia or Bangkok, or do not want to time your purchase around sales. Each trip must be 90 days or shorter.
Get both quotes on Income’s site, then run the sum with your own numbers before you buy.
Current Income travel insurance promotions
- Yearly plans: 25% off Classic, Deluxe and Preferred Yearly plans for new policies bought by 31 December 2026. No code is needed. See the yearly plan offer
- Per-trip flash sales: the current sale gives 55% off Standard per-trip plans until 26 October 2026, 9am. Premiums of S$100 or more after the discount also get a Miffy keychain camera with code MIFFYCAM55, while stocks last. The next flash sales run 26 to 29 October and 2 to 5 November 2026; check Income’s page for each sale’s discount. See the per-trip offer
The per-trip flash sale cannot be combined with other Income promotions. We keep a list of Income’s other current offers, including home and helper insurance, on our Income Insurance promotions page.
Watch-outs before you buy
Pre-existing conditions. Income says regular travel insurance may not cover pre-existing medical conditions such as diabetes, heart conditions or asthma. If you have one, look at Income’s Enhanced PreX plan instead, which covers them up to set limits.
Buy early. Trip cancellation cover only helps if the policy is in place before something goes wrong. Buy as soon as you book flights, not the night before you fly.
Do not cancel to re-buy. Income’s promotion terms exclude anyone who cancels an existing Income travel policy and buys a new one for the same trip to get the discount.
Read the exclusions. Check the policy wording for activities that are not covered, and keep police, airline or hotel reports if something goes wrong, as claims usually need them.
Pay smart too. Insurance covers emergencies, but card fees cost you on every purchase. A no-FX-fee card saves around 3% on overseas spending; see our Trust vs YouTrip comparison or, if you collect miles, our guide to the best miles credit cards in Singapore.
Our verdict: who Income travel insurance suits
Good fit: travellers who want a big local insurer with clear tiers, families who travel a few times a year, and anyone happy to time purchases around Income’s frequent per-trip sales.
Think twice: if you have a pre-existing condition (look at Enhanced PreX), if you only drive across to Malaysia (see our Malaysia travel insurance guide), or if you travel just once a year, where a single per-trip policy bought on sale is usually cheapest.
Whichever you pick, compare at least two insurers on the same trip. Income is a solid choice, but it is not always the cheapest for every route. Heading to Europe? Our YouTrip Italy guide covers spending money there.
Not financial advice. Premiums, coverage and promotions change. Check the policy wording and current terms on Income’s website before you buy.
Frequently Asked Questions
Is Income travel insurance good?
Income’s Standard plans offer solid coverage, from S$350,000 overseas medical cover on Classic to unlimited on Preferred, and it is one of Singapore’s largest insurers. Whether it is the best value depends on your trip, so compare quotes for the same dates and destination.
Is yearly travel insurance worth it in Singapore?
Divide the yearly premium by the price of one per-trip policy. If you take more trips than that a year, yearly is cheaper. Because per-trip plans are often on sale, most people need about four or more trips a year before a yearly plan pays off.
What is the difference between Income's Classic, Deluxe and Preferred plans?
The tiers differ mainly in limits. Overseas medical cover is S$350,000 on Classic, S$800,000 on Deluxe and unlimited on Preferred, and trip cancellation cover is S$5,000, S$10,000 and S$15,000. Preferred also covers cancelling for any reason, with a 50% co-payment.
How long can each trip be on Income's yearly travel plan?
Each trip on a yearly plan can be up to 90 days. Per-trip plans can cover a single trip of up to 180 days.
Does Income travel insurance cover pre-existing conditions?
Income says regular travel insurance may not cover pre-existing conditions. Its Enhanced PreX plan is designed for travellers with conditions such as diabetes, heart conditions or asthma, with set limits.
Can I get a refund on Income's yearly travel insurance?
Yes, if you cancel within 180 days of the start date and have not made a claim, Income refunds 85% of the unused premium. Per-trip plans give no refund after the start date.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.