Mapletree Industrial Trust (ME8U): Data Centre Growth, DPU History and 2026 Outlook
Published September 2026 | SGX: ME8U | Deep-Dive
Mapletree Industrial Trust (SGX: ME8U) is Singapore’s largest industrial REIT by asset value, managing a S$9.3 billion portfolio where data centres now account for over half of total assets. With exposure to hyperscaler tenants in Singapore and North America, MIT offers income investors a 6%-plus yield and meaningful data centre growth at a time when AI-driven demand is reshaping industrial real estate fundamentals.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
- MIT is a S$9.3B industrial REIT with 57% of AUM in data centres, offering 6%+ distribution yield.
- Annual DPU has grown from 12.27 cents (FY2020) to approximately 14 cents, showing income resilience.
- Rising interest rates raise refinancing costs but long-term hyperscaler leases provide a stable DPU floor.
What is Mapletree Industrial Trust (SGX: ME8U)?
Mapletree Industrial Trust is a real estate investment trust listed on the Singapore Exchange under the ticker ME8U. It is managed by Mapletree Industrial Trust Management Ltd, a wholly owned subsidiary of Mapletree Investments Pte Ltd.
MIT was listed in 2010 and has since grown from a pure Singapore industrial REIT into a diversified industrial and data centre platform spanning Singapore, the United States, and Japan. As of 2026, its portfolio spans 143 properties with total assets under management of approximately S$9.3 billion.
What makes MIT distinct from traditional industrial REITs is its strategic pivot toward data centres. Since 2020, MIT has been systematically growing its data centre exposure through acquisitions in Singapore and North America, making data centres its single largest asset class today.
MIT Portfolio Breakdown: Data Centres vs Industrial Assets
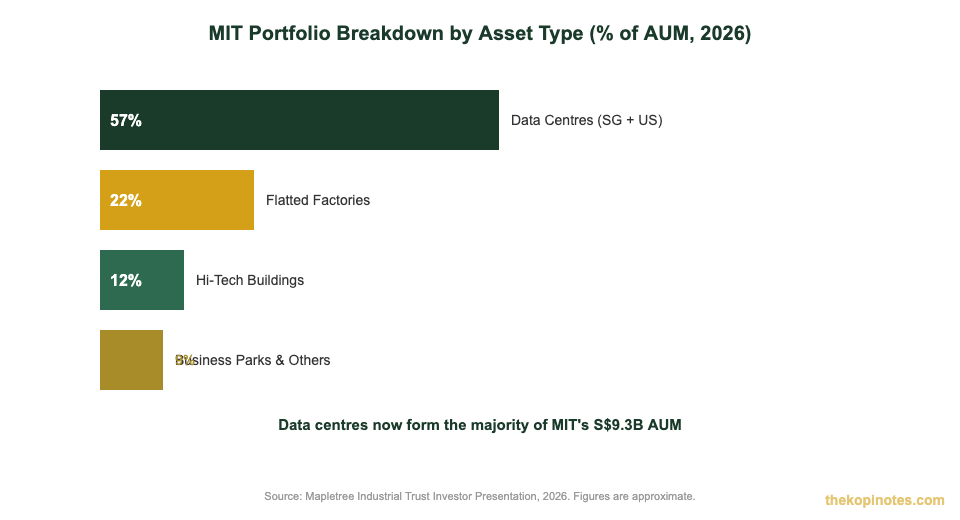
MIT’s portfolio is no longer what most investors picture when they hear “industrial REIT.” Data centres now represent the majority of its asset value, a transformation that began with Mapletree’s US data centre acquisitions and has continued through subsequent Singapore deals.
Here is how MIT’s portfolio breaks down by asset type as at 2026:
| Asset Type | % of AUM | Key Markets |
|---|---|---|
| Data Centres | ~57% | Singapore, USA |
| Flatted Factories | ~22% | Singapore |
| Hi-Tech Buildings | ~12% | Singapore |
| Business Parks and Others | ~9% | Singapore, Japan |
Source: Mapletree Industrial Trust Investor Presentation, 2026. Figures are approximate.
Data centre demand in Singapore is being driven by hyperscaler expansions from Google, Amazon, and Microsoft. These tenants sign long-term leases — often 10 to 20 years — providing MIT with highly predictable rental income that is relatively insensitive to short-term rate moves.
MIT DPU History: Track Record FY2020 to FY2026
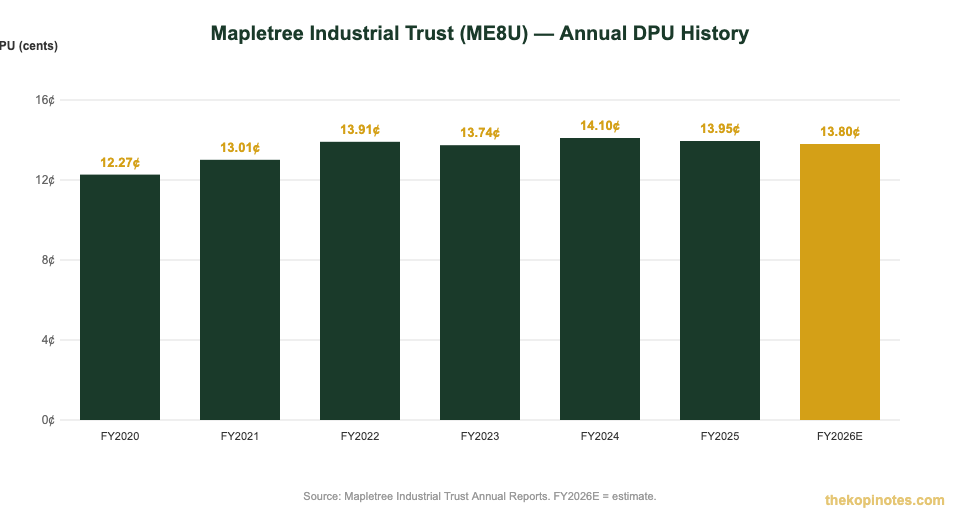
Distribution Per Unit (DPU) is the cash payout each MIT unit makes to you every quarter. MIT pays distributions quarterly, and its annual DPU has shown a broadly upward trend over the past six years despite navigating COVID-19, rising rate cycles, and global macro headwinds.
| Financial Year | Annual DPU (cents) | YoY Change |
|---|---|---|
| FY2020 | 12.27 | — |
| FY2021 | 13.01 | +6.0% |
| FY2022 | 13.91 | +6.9% |
| FY2023 | 13.74 | -1.2% |
| FY2024 (est.) | 14.10 | +2.6% |
| FY2025 (est.) | 13.95 | -1.1% |
| FY2026E | ~13.80 | ~-1.1% |
Source: Mapletree Industrial Trust Annual Reports. FY2024 onwards are estimates. Verify with latest MIT results.
The mild DPU softness from FY2023 reflects higher financing costs as rates rose. The decline has been modest — under 2% annually — because data centre income has held firm. At current prices around S$2.10 to S$2.20, MIT offers an indicative yield of approximately 6.2% to 6.6%. Compare it across the best S-REITs in Singapore 2026.
Mapletree Industrial Trust Share Price in 2026
MIT’s share price has been under pressure in 2026 as rate hike expectations raised the cost of capital for REITs globally. Higher rates compress REIT valuations by widening the spread investors demand over risk-free rates.
In the post-hike environment, MIT typically trades at a discount to its net asset value (NAV). For a long-term income investor, a below-NAV MIT with a 6%+ yield and a data centre portfolio anchored by hyperscaler tenants may represent fair value. To model the retirement income potential from a REIT position, use the Singapore retirement planning calculator.
Always check the latest MIT results on the Mapletree Industrial Trust investor relations page for current NAV and share price data before making any decision.
MIT Gearing and Refinancing Risk at Higher Rates
MIT’s aggregate leverage sits around 37%, comfortably below the 50% MAS regulatory limit. However, at higher interest rates, even modest gearing creates DPU drag.
If MIT has approximately S$3.5 billion of total borrowings and 25 basis points of debt refinances higher in a given year, the incremental annual interest cost is roughly S$8.75 million. With approximately 1.65 billion units outstanding, that is roughly 0.5 cents per unit of annual interest drag — about 3.5% of DPU.
MIT manages this risk through interest rate hedging, staggered debt maturities, and retained income. The weighted average debt maturity is historically around 3 to 4 years, so the full impact of any rate cycle is absorbed gradually. For a broader look at passive income options, read our guide on building passive income in Singapore 2026.
MIT vs Peers: Data Centre REIT Comparison 2026
How does MIT compare to Keppel DC REIT and CapitaLand Ascendas REIT? We covered the full head-to-head in the MIT vs Keppel DC REIT comparison. Here is a quick snapshot:
| Metric | MIT (ME8U) | Keppel DC (AJBU) | CLAR (A17U) |
|---|---|---|---|
| AUM | ~S$9.3B | ~S$3.5B | ~S$17.8B |
| Data Centre % | ~57% | ~100% | ~10% |
| Indicative Yield | ~6.2% | ~4.8% | ~5.5% |
| Gearing | ~37% | ~36% | ~39% |
Source: SGX disclosures, company investor presentations, September 2026. Indicative estimates only.
Who Should Invest in Mapletree Industrial Trust?
MIT makes most sense for investors who want data centre exposure within a diversified industrial REIT structure, without paying the premium multiple of a pure-play data centre REIT.
You are a good fit for MIT if you want 6%+ income from a large-cap S-REIT with a strong sponsor, believe in long-term AI data centre demand in Asia-Pacific, and are comfortable holding through rate volatility without needing to sell if NAV dips temporarily.
To buy MIT, platforms like Syfe (code SRPRFFFCD) and FSMOne (code P0544985) allow SGX access. For CPF and SRS investing, Endowus (code 2V343) offers REIT-inclusive portfolios. For the lowest brokerage costs on direct lot purchases, IBKR (code jianxiong368) is widely used by regular S-REIT investors.
Frequently Asked Questions
What is the current Mapletree Industrial Trust DPU?
How does MIT compare to Keppel DC REIT?
Is MIT a good investment with higher interest rates in 2026?
What percentage of MIT's portfolio is data centres?
Where can I buy Mapletree Industrial Trust (ME8U) in Singapore?
Explore More S-REIT Guides on TKN
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.