Medisave for Day Surgery Singapore 2026: What’s Covered, Limits & How Your ISP Fills the Gap
- What counts as day surgery in Singapore?
- MediSave ward charges for day surgery
- Surgery limits — the TOSP table explained
- How your Integrated Shield Plan covers the rest
- How to claim MediSave for day surgery (step-by-step)
- Bill comparison: Government vs private hospital
- 5 practical tips before your day surgery
- FAQ
MediSave covers two components of a day surgery bill in Singapore: ward charges (up to $830 per day) and the surgical procedure itself (between $240 and $5,290 depending on complexity). If your bill exceeds these MediSave limits — which it almost always does at a private hospital — your Integrated Shield Plan (ISP) kicks in to cover the remainder, subject to deductible and co-payment rules. Understanding exactly how these two layers work together can save you thousands of dollars in out-of-pocket costs.
Not financial advice. All figures are for educational reference only. Data verified as at September 2026 from CPF Board and MOH sources unless noted.
- MediSave pays up to $830/day for ward charges plus a surgery-specific limit (varies by procedure complexity)
- Your ISP base plan covers most of the gap — but your rider must be paid in cash, not MediSave
- Always confirm your surgery table (TOSP) and get a pre-admission cost estimate before checking in
What counts as day surgery in Singapore?
Day surgery — also called ambulatory surgery — means you go into hospital, have a procedure, and go home on the same day. You don’t stay overnight.
Common day surgeries in Singapore include:
- Cataract removal
- Laparoscopic (keyhole) procedures like gallbladder removal
- Colonoscopy with polyp removal
- Arthroscopy (knee or shoulder)
- Wisdom tooth extraction under general anaesthesia
- LASIK (not MediSave-claimable — see below)
Day surgeries are still classified as inpatient procedures for MediSave purposes. That means the same inpatient withdrawal rules apply — you can use MediSave for both the ward stay and the surgical fee.
Not all procedures qualify, though. Elective cosmetic surgery and LASIK are excluded. The full list of approved day surgery procedures is maintained by MOH.
MediSave ward charges for day surgery
For the hospital stay itself — things like the day ward, nursing care, investigations, and medicines — MediSave covers up to $830 per day. For most day surgeries, you’ll be in hospital for part of one day, so this $830 limit covers your entire inpatient stay component.
This covers:
| Item | Covered? |
|---|---|
| Daily ward charges | ✅ Yes |
| Nursing care & daily treatment fees | ✅ Yes |
| Investigations (X-rays, blood tests) | ✅ Yes |
| Medicines dispensed during admission | ✅ Yes |
| Outpatient medications after discharge | ❌ No |
| Surgeon’s fee | ✅ Yes (separate limit — see below) |
Source: CPF Board, MediSave for Hospitalisation, September 2026
Surgery limits — the TOSP table explained
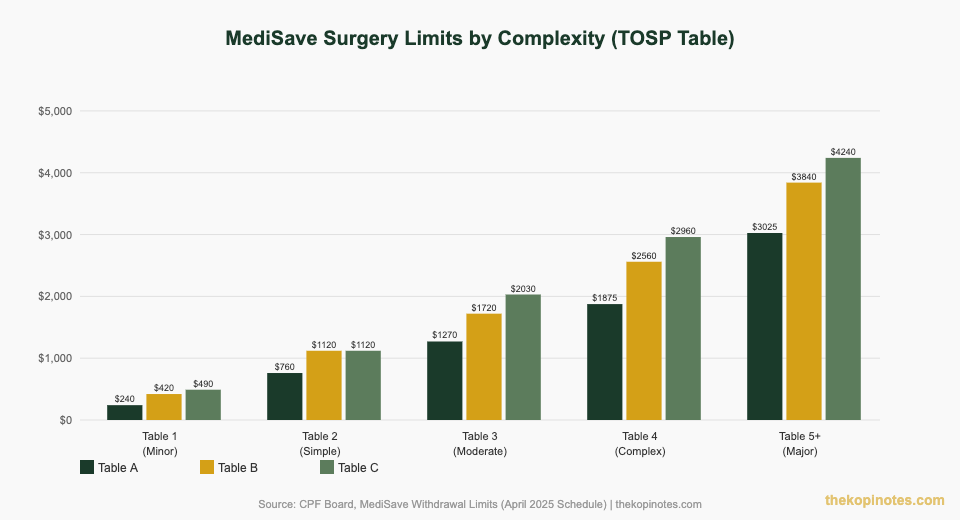
On top of the $830/day ward limit, MediSave also covers your surgeon’s fee. But this amount depends on the complexity of your procedure — not the actual cost.
CPF uses a document called the Table of Surgical Procedures (TOSP) to classify every approved surgery into complexity tables — from Table 1 (minor) to Table 7 (very complex). Each table has three sub-columns (A, B, C) based on approach and risk.
Here’s how the limits break down:
| TOSP Table | Column A | Column B | Column C |
|---|---|---|---|
| Table 1 (Minor) | $240 | $420 | $490 |
| Table 2 (Simple) | $760 | $1,120 | $1,120 |
| Table 3 (Moderate) | $1,270 | $1,720 | $2,030 |
| Table 4 (Complex) | $1,875 | $2,560 | $2,960 |
| Table 5 (Major) | $3,025 | $3,840 | $4,240 |
Source: CPF Board, MediSave Withdrawal Limits Schedule (effective April 2025). Tables 6 and 7 apply to highly complex procedures. Actual limits may vary — check the latest TOSP on the CPF website.
A cataract removal, for example, typically falls under Table 3B — so MediSave covers up to $1,720 of the surgeon’s fee. A straightforward laparoscopic cholecystectomy (gallbladder removal) usually falls under Table 4 or 5.
You can use MediSave for a maximum of 3 surgical procedures per admission, covering no more than 2 anatomical systems.
How your Integrated Shield Plan covers the rest
Most day surgery bills — especially at private hospitals — far exceed the MediSave limits. That’s where your Integrated Shield Plan (ISP) steps in.
Your ISP base plan (which you pay for with MediSave) covers hospital bills above the MediSave limits, subject to two key costs you bear yourself:
- Deductible — the first portion of the bill you pay each policy year (e.g. $3,500 for a typical private hospital ISP)
- Co-payment — a percentage of the remaining bill (typically 10%), capped at $3,000 per policy year under the post-April 2026 MOH rules
Your ISP rider (the add-on that historically covered your deductible and co-payment) has been significantly changed since April 2021. Since then:
- Riders can no longer cover 100% of the deductible
- You must pay at least $3,000 of your deductible in cash or Medisave
- Rider premiums must be paid entirely in cash — not MediSave
This is a common source of confusion. Your ISP base plan premium can be paid with your Additional Withdrawal Limit (AWL) from MediSave — $300/year (age ≤40), $600/year (age 41–70), or $900/year (age 71+) above the MediShield Life premium. But the rider is cash-only.
Using your ISP for a day surgery claim
When you check into hospital for a day surgery, give your ISP membership details at registration. The hospital’s billing department coordinates directly with your insurer. You typically receive a single bill showing what’s been offset by MediSave, what the insurer paid, and what you owe out of pocket.
For more on how ISP coverage works and which plan suits which ward class, see our guide on what an Integrated Shield Plan is.
How to claim MediSave for day surgery (step-by-step)
The good news: claiming MediSave for day surgery is mostly automatic. You don’t need to file a separate MediSave claim form. Here’s how it works:
- Get a cost estimate beforehand. Ask your surgeon or the hospital admissions team for a pre-admission cost estimate. This shows the estimated total bill, the MediSave-payable amount, and your estimated out-of-pocket cost.
- Complete the MediSave authorisation form at admission. When you’re admitted, you’ll sign a form authorising the hospital to withdraw from your MediSave (and your family members’ MediSave, if applicable).
- Present your ISP card at registration. Hand over your ISP membership card so the hospital can coordinate with your insurer. Check that the ward class matches what your ISP covers.
- The hospital handles the claims after your procedure. Within a few days of discharge, the hospital submits the MediSave claim electronically. Funds are deducted from your CPF MediSave account — you don’t transfer anything manually.
- Pay the out-of-pocket balance on discharge. You’ll pay any remaining deductible or co-payment amount at the billing counter — by cash, NETS, or credit card (not MediSave for this portion unless it’s specifically covered).
- Check your CPF statement. After your surgery, log into your CPF account to confirm the MediSave deduction matches the amount on your hospital bill.
You can also use a family member’s MediSave to pay for your day surgery, as long as they are your spouse, children, parents, grandparents, or siblings. See our full guide on MediSave for family members for eligibility rules.
Bill comparison: Government vs private hospital day surgery
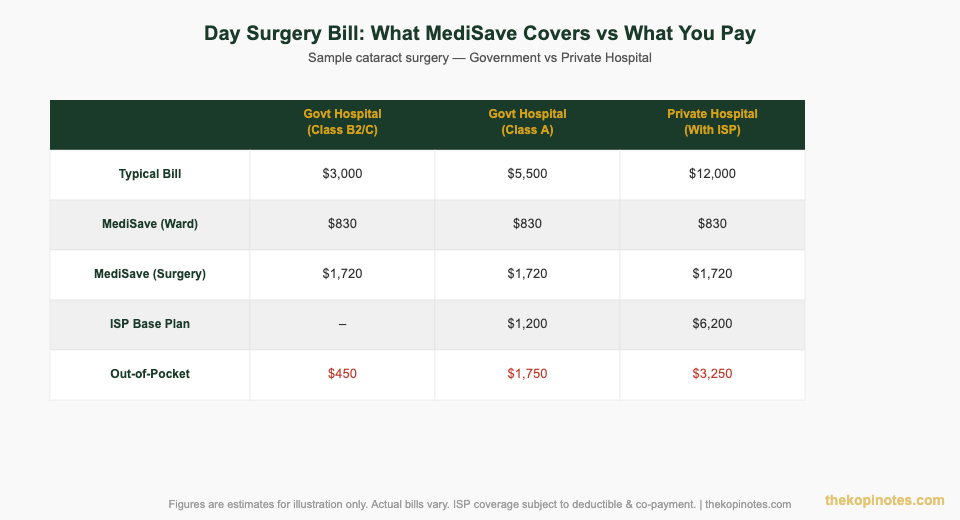
Here’s a real-world example using a cataract surgery to show how the numbers stack up across different hospital settings.
| Item | Govt Hospital B2/C | Govt Hospital A Class | Private Hospital (with ISP) |
|---|---|---|---|
| Estimated Total Bill | ~$3,000 | ~$5,500 | ~$12,000 |
| MediSave (ward charges) | $830 | $830 | $830 |
| MediSave (surgery — Table 3B cataract) | $1,720 | $1,720 | $1,720 |
| Government subsidy | ~$950 (50–80%) | Minimal | None |
| ISP base plan covers | – | ~$1,200 | ~$6,200 |
| Out-of-Pocket (cash) | ~$450 | ~$1,750 | ~$3,250 |
Estimates based on 2026 cataract surgery bills. Actual figures vary by hospital, surgeon, and ISP plan. Deductible and co-payment apply to the ISP portion.
The takeaway: even at a private hospital with a good ISP, you’re still paying around $3,000 out of pocket for a $12,000 bill. At a government hospital B2/C ward, your total cash cost can drop to under $500 for the same procedure.
5 practical tips before your day surgery
1. Ask for the TOSP code upfront
Your surgeon should be able to tell you which TOSP table your procedure falls under. This tells you exactly how much MediSave you can use for the surgical fee. Don’t be shy about asking — it’s your money.
2. Get a pre-admission cost estimate in writing
MOH requires all public hospitals and most private hospitals to provide written cost estimates before elective procedures. Request one at least a week before your procedure. This estimate shows the MediSave-payable amount, the ISP offset, and your out-of-pocket payment — so there are no surprises at the billing counter.
3. Check your ISP ward class entitlement
Your ISP has a “plan type” (for example, AIA HealthShield Gold Max A covers private hospital, while Plan B covers restructured hospital Class A). Going to a higher ward class than your plan covers means you bear more of the bill. For more on how ward classes and ISPs interact, see our full ISP co-payment and ward class guide.
4. Check your deductible has already been met
The deductible resets every policy year. If you’ve already had another hospitalisation this year, your deductible may already be met — which means you pay less out of pocket for a subsequent day surgery. Check with your insurer before assuming the worst.
5. Consider using a broker for ISP comparisons
If you don’t currently have an ISP or you’re reviewing your coverage, a financial adviser can run a side-by-side comparison. Alternatively, the Singapore retirement calculator on TKN can help you factor healthcare costs into your overall financial plan. You can also use Syfe referral code for savings tools, or explore Endowus referral code for CPF-OA and SRS investments that grow your healthcare buffer.
Frequently Asked Questions
Can I use MediSave to pay for a day surgery at a private hospital?
How much MediSave can I use for a cataract surgery in Singapore?
Can I use my family member's MediSave for my day surgery?
Can MediSave cover my ISP rider premium?
What day surgeries are NOT covered by MediSave?
How do I check how much MediSave I have left?
Do I need to file a MediSave claim myself after day surgery?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.