Singapore Fixed Deposit Rate (September 2026): Best Rates Compared
Compare every major bank’s FD rate — from GXS at 1.75% to DBS at 1.00% — and find the best Singapore fixed deposit for your savings goal.
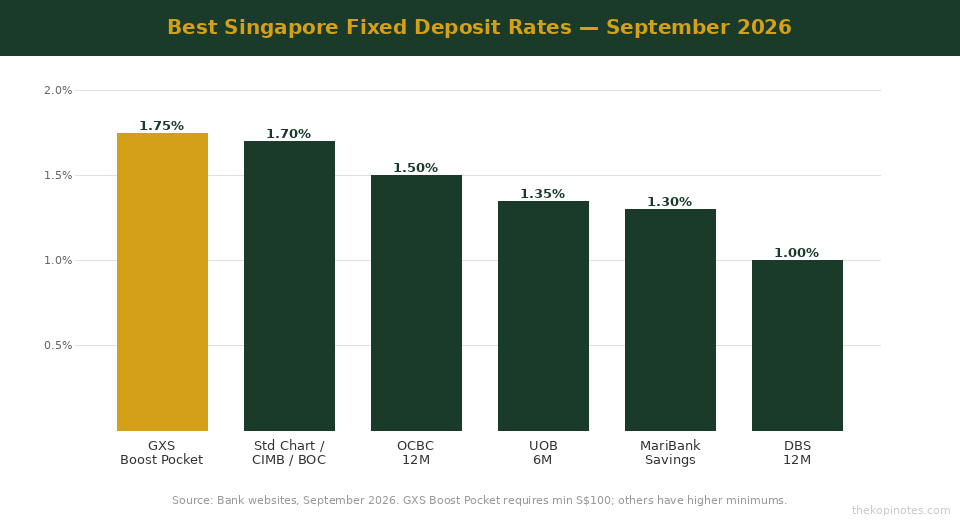
The best Singapore fixed deposit rate as at September 2026 is 1.75% p.a. — offered by GXS Bank’s Boost Pocket for 12 months, with a minimum of just S$100. Traditional banks offer 1.00% to 1.70% p.a. depending on tenure and minimum deposit. Your deposits are insured up to S$100,000 by the Singapore Deposit Insurance Corporation (SDIC), whether at a traditional bank or a licensed digital bank.
Not financial advice. All figures are for educational reference only. Data verified as at 19 September 2026. Rates are subject to change — always verify with your bank before placing a fixed deposit.
- GXS Bank’s Boost Pocket (1.75% p.a., 12 months, min S$100) is the best-rate option with the lowest minimum in Singapore as at September 2026
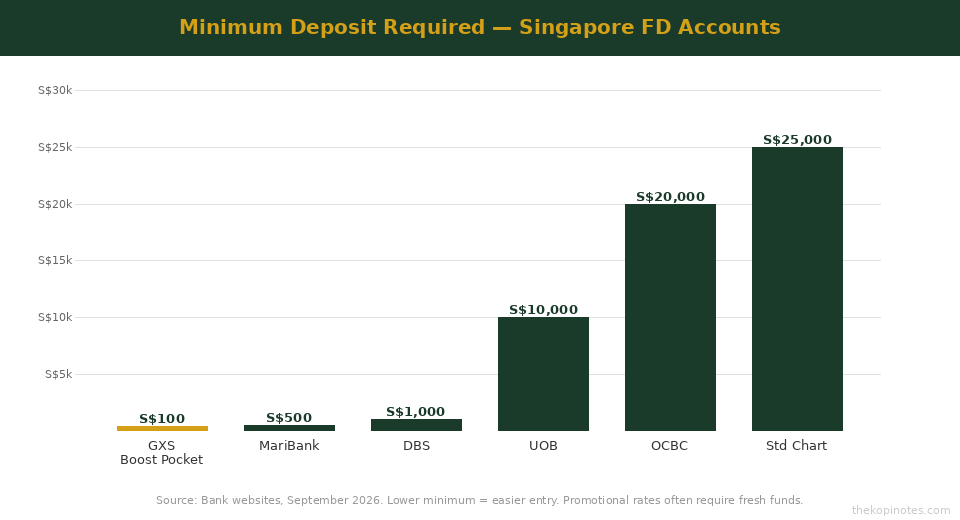
- Traditional banks like OCBC (1.50%), UOB (1.35%), and DBS (1.00%) require higher minimums (S$10,000–S$25,000) for competitive rates
- All deposits at MAS-licensed banks — including digital banks — are SDIC-insured up to S$100,000 per depositor
What Is a Fixed Deposit in Singapore?
A fixed deposit (FD) is a savings product where you lock a lump sum with a bank for a set period — typically 1 to 24 months. In exchange, the bank pays you a guaranteed interest rate for that period. At the end of the term (called maturity), you get your principal plus the interest earned.
In Singapore, fixed deposits are also called “time deposits.” They work the same way — the terms are interchangeable.
Fixed deposits differ from regular savings accounts in one key way: your money is locked in. You can usually break a fixed deposit early, but you’ll often forfeit the interest earned. That’s why FDs suit money you won’t need for 6–12 months.
All MAS-licensed banks — including digital banks like GXS and MariBank — are covered by the Singapore Deposit Insurance Scheme (SDIC). Your deposits are protected up to S$100,000 per depositor per financial institution. This limit was raised from S$75,000 in April 2024.
This means a GXS Boost Pocket is just as safe as a DBS fixed deposit — as long as your total at that bank stays within the S$100,000 SDIC limit.
Best Singapore Fixed Deposit Rates — September 2026
Here are the best fixed deposit rates available to Singapore residents as at September 2026. All rates are in SGD unless stated.
| Bank / Product | Rate (p.a.) | Tenure | Min. Deposit | Notes |
|---|---|---|---|---|
| GXS Boost Pocket ⭐ | 1.75% | 12 months | S$100 | Best rate + lowest minimum. Use code YONG477 |
| Standard Chartered / CIMB / Bank of China | Up to 1.70% | 6–12 months | S$10,000–S$25,000 | Vary by bank and tenure. Check individual bank sites |
| OCBC Fixed Deposit | 1.50% | 12 months | S$20,000 | Online placement; 1.35% for 6 months |
| UOB Fixed Deposit | 1.30–1.35% | 6 months | S$10,000 | Fresh funds required |
| MariBank Savings Account | 0.88% | Flexible (no lock-in) | No minimum | +1.60% new user bonus first 30 days. Use code 2DCT80WQ |
| DBS Fixed Deposit | 1.00% | 12 months | S$1,000 | Low minimum, but lower rate. S$1k–S$19,999 tier |
Source: Bank websites, MoneySmart, September 2026. Rates are subject to change without notice. Always verify with your bank before placing a fixed deposit. Fresh funds conditions may apply.
Digital Banks vs Traditional Banks: FD Rates Compared
One of the biggest surprises for Singapore savers in 2026 is how competitive digital banks have become on deposit rates — particularly GXS Bank.
Here’s how digital banks stack up against traditional banks for a S$10,000 placement over 12 months:
| Bank Type | Example | Rate (12M) | Interest on S$10,000 | Min Deposit |
|---|---|---|---|---|
| Digital Bank | GXS Boost Pocket | 1.75% | S$175 | S$100 |
| Traditional | OCBC FD | 1.50% | S$150 | S$20,000 |
| Traditional | UOB FD (6M × 2) | 1.35% | S$135 | S$10,000 |
| Traditional | DBS FD | 1.00% | S$100 | S$1,000 |
Source: Bank websites, September 2026. Interest calculated on S$10,000 principal for 12 months. OCBC rate requires S$20,000 minimum — rate for a S$10,000 placement may be lower.
The GXS Boost Pocket earns S$75 more per year on S$10,000 than DBS — with a much lower minimum deposit of S$100. The key difference: GXS is a newer digital bank backed by Grab and Singtel, while DBS is Singapore’s largest bank with 130+ years of history.
Both are MAS-licensed and SDIC-insured. The GXS article on TKN goes into more detail on its full product suite — see our GXS Bank Review Singapore 2026 for the complete breakdown.
How to Choose the Right Fixed Deposit in Singapore
Not every fixed deposit is right for everyone. Here’s a simple framework to decide:
Choose GXS Boost Pocket if: You want the highest available rate with the lowest minimum entry (S$100). Great for first-time FD savers or those testing digital banks before committing more. Open a GXS account with referral code YONG477.
Choose OCBC or UOB FD if: You have S$20,000+ in fresh funds to place and want the security of a traditional Big Three bank with branch support.
Choose Standard Chartered / CIMB / Bank of China if: You want competitive rates (up to 1.70%) and are comfortable with smaller foreign bank branches in Singapore.
Choose DBS FD if: You want the simplicity of your existing DBS relationship and have less than S$10,000 to place.
Watch out for the “fresh funds” condition. Most promotional FD rates require you to bring money from outside that bank — existing deposits usually don’t qualify. If you’re moving money between banks to chase rates, make sure you’re not breaking an existing FD prematurely (you’d forfeit the interest).
For emergency funds that you might need quickly, a high-yield savings account like the MariBank savings account (0.88% p.a. base, no lock-in) may be more appropriate than a 12-month FD.
Alternatives to Fixed Deposits in Singapore
Fixed deposits aren’t the only way to park your cash safely in Singapore. Here are three alternatives worth knowing about:
Singapore Savings Bonds (SSBs): Issued by the Singapore government, SSBs offer step-up interest rates over 10 years with full flexibility — you can redeem at any month end without penalty. The average 10-year rate is typically 2.5–3.5% p.a. They’re best for long-term savers who want government-backed returns. See our Singapore Savings Bonds guide for a full breakdown.
Singapore T-Bills (6-month): Treasury bills offer short-term government-backed returns at competitive rates. The cut-off yield for 6-month T-bills has recently been in the 2.8–3.2% range, making them very attractive vs. bank FDs. Check our Singapore T-bills 2026 guide for how to apply and current rates.
Robo-advisor cash management: Products like Syfe Cash+ (referral code SRPRFFFCD) typically offer 2.5–3.5% p.a. on cash with same-day liquidity. They’re not bank deposits and not SDIC-insured, but they invest in money market funds that hold short-term government and corporate paper.
The right choice depends on your time horizon and how much flexibility you need. If you’re building towards retirement, our Singapore retirement calculator can help you work out how much your savings need to grow.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Interest rates change frequently — verify all rates directly with your bank or product provider before making any financial decision. The Kopi Notes may earn referral fees from sign-ups via our referral links.
Frequently Asked Questions
What is the best fixed deposit rate in Singapore right now?
As at September 2026, the best fixed deposit rate in Singapore is 1.75% p.a. — offered by GXS Bank’s Boost Pocket for a 12-month placement with a minimum of just S$100. Among traditional banks, Standard Chartered, CIMB, and Bank of China offer up to 1.70% p.a., while OCBC offers 1.50% for 12 months and UOB 1.30–1.35% for 6 months. DBS offers 1.00% for 12 months. Rates change frequently — always verify with your bank before placing.
Are fixed deposits at digital banks like GXS safe?
Yes. GXS Bank holds a full digital bank licence from the Monetary Authority of Singapore (MAS) — the same regulatory level as DBS, OCBC, and UOB. Your deposits at GXS are insured by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per depositor. As long as your balance at GXS stays below S$100,000, your money is fully protected even if GXS were to fail. GXS is backed by Grab and Singtel — two of Southeast Asia’s largest companies.
Can I break a fixed deposit early in Singapore?
Generally, yes — but you’ll usually forfeit some or all of the interest earned. Most traditional banks allow early redemption but will pay you little or no interest on the amount withdrawn early. GXS’s Boost Pocket is slightly more flexible: if you withdraw before maturity, you still receive the base rate of 0.88% p.a. up to the date of withdrawal. Always check the early withdrawal terms before placing, especially for large sums or long tenures.
What does 'fresh funds' mean for fixed deposits?
“Fresh funds” means money coming from outside that specific bank — not money already sitting in your existing account there. Most banks offer promotional FD rates only to fresh funds. So if you want UOB’s 1.35% rate, your S$10,000 must be transferred from another bank (e.g. DBS or a SingSaver-linked account), not from your existing UOB savings account. If you break an existing UOB FD to qualify, you’d first forfeit your current interest, so the maths doesn’t always work out in your favour.
Is a fixed deposit better than a Singapore Savings Bond?
It depends on your time horizon and need for liquidity. Singapore Savings Bonds (SSBs) currently offer a higher average return over 10 years — typically 2.5–3.5% p.a. — and can be redeemed penalty-free at any month end. That beats most bank FD rates. However, SSBs have a monthly subscription cap (S$200,000 per person, S$200,000 minimum) and the best rates are back-loaded (you earn more in later years). If you need your money back in 6–12 months, a bank FD is simpler. If you’re parking savings you won’t touch for 3–5 years, SSBs usually win on rate.
How do I open a fixed deposit in Singapore?
For digital banks like GXS: download the GXS app, complete identity verification via Singpass, open a GXS savings account, and create a Boost Pocket to lock funds at the current rate. The whole process takes under 30 minutes. For traditional banks: you can apply online via internet banking (fastest), or visit a branch. You’ll typically need your NRIC/passport and the funds to transfer in. Promotional rates often require you to apply by a specific deadline, so always check the promotion terms first.
Get Started With the Best FD Rate in Singapore
Open a GXS account with referral code YONG477 and lock in 1.75% p.a. for 12 months — with just S$100.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.