TribeCar + MariBank + Syfe + IBKR: The Insured-First Cash Waterfall (2026)
A 4-platform strategy for freed-up car money — parked in order of protection, not just yield.
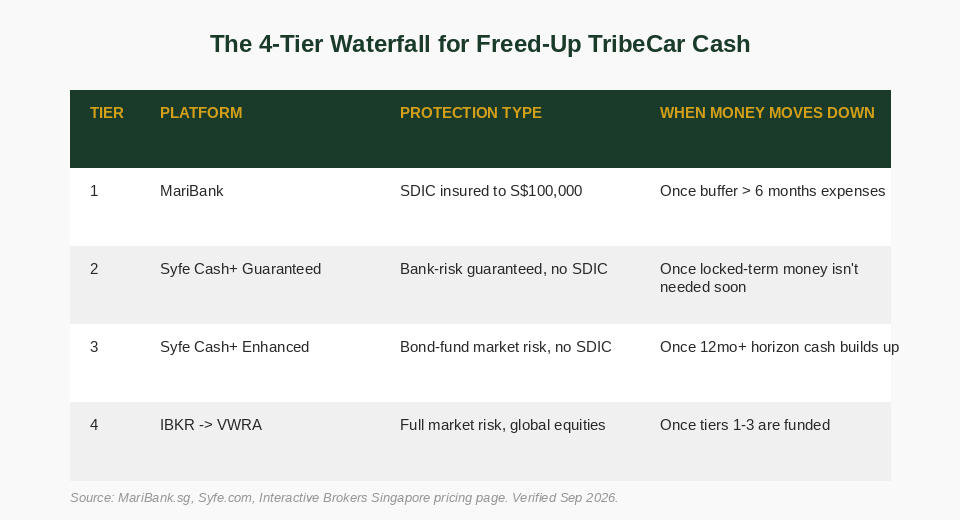
If you skip car ownership with TribeCar, the S$400-600 a month you free up should not all go to one place. Park it in order: MariBank first (SDIC-insured to S$100,000), then Syfe Cash+ Guaranteed (bank-risk guaranteed, no SDIC), then Syfe Cash+ Enhanced, and only then IBKR for global equity growth via VWRA.
Not financial advice. All figures are for educational reference only. Rates verified via direct fetch from MariBank.sg, Syfe.com and Interactive Brokers Singapore’s pricing page, September 2026.
- MariBank is the only platform here with government-backed deposit insurance (SDIC) — so it should hold your emergency buffer first, up to S$100,000.
- Syfe Cash+ products are guaranteed by contract, not by SDIC — that’s a real difference most people don’t check.
- IBKR only comes into play once tiers 1-3 are funded, and even then, watch the zero-interest cash thresholds while you wait to invest.
Table of Contents
Why order matters more than yield
Tier 1: MariBank — the SDIC-insured floor
Tier 2: Syfe Cash+ Guaranteed — guaranteed but uninsured
Tier 3: Syfe Cash+ Enhanced — accepting market risk for yield
Tier 4: IBKR + VWRA — the growth overflow
A worked example: S$500 a month
How this differs from our other TribeCar combos
FAQs
Why Order Matters More Than Yield
Skip car ownership with TribeCar and you free up real money. No COE, no insurance premium, no depreciation, no parking. For a typical two-car-swap household, that is easily S$400 to S$600 a month.
Most guides tell you to just “invest the difference.” That skips a question worth asking first: what happens if the platform holding your money fails? Not every account here answers that question the same way.
MariBank is a bank. Its deposits are covered by the Singapore Deposit Insurance Corporation (SDIC) — basically a government-backed guarantee that pays you back if the bank collapses, up to S$100,000 per depositor. Syfe Cash+ products are not deposits. They are investment portfolios that hold fixed deposits or bond funds on your behalf. Syfe’s own site says it plainly: “as this is an investment product, SDIC coverage doesn’t apply.” Your return is guaranteed by contract, not insured by the government.
That is not a reason to avoid Syfe. It is a reason to sequence your money correctly — insured protection first, contractual guarantees second, market-risk growth last.
Tier 1: MariBank — The SDIC-Insured Floor
Your first S$100,000 of parked cash belongs here, not because MariBank pays the highest rate, but because it is the only platform in this combo where the Singapore government stands behind your deposit.
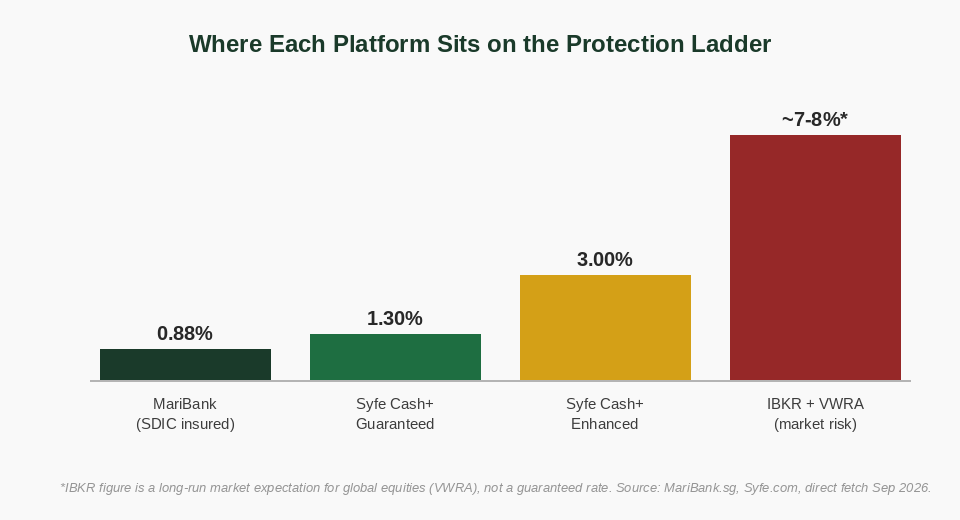
MariBank’s Mari Savings Account pays a base rate of 0.88% p.a., with no minimum deposit, no salary crediting, and no minimum spend required. New users get a 30-day bonus of an extra 1.60% p.a., taking the effective rate to 2.48% p.a. on the first S$100,000 during that window.
For most people freeing up TribeCar cash, this tier should hold 3 to 6 months of expenses — your true emergency fund. Anything beyond that, keep reading.
Tier 2: Syfe Cash+ Guaranteed — Guaranteed But Uninsured
Once your MariBank buffer is full, the next stop is Syfe Cash+ Guaranteed. This locks your money into fixed deposits with MAS-regulated partner banks for a term you choose — 1, 3, or 6 months in SGD.
As at the direct rate fetch for this article, Cash+ Guaranteed (SGD) pays 1.15% p.a. for a 1-month term, rising to 1.25% at 3 months and 1.30% at 6 months. There is no minimum or maximum funding amount, and no management fee.
Here’s the part people miss: because this is an investment product wrapping underlying bank deposits, SDIC coverage does not apply to your Syfe portfolio itself — only Syfe’s diversification across multiple MAS-regulated banks reduces (not eliminates) single-bank risk. That’s a meaningfully different guarantee from MariBank’s SDIC-backed deposit, even though both use the word “guaranteed.”
Use this tier for money you won’t need for the length of the term you pick — money that’s beyond your emergency fund but still needs a fixed, known return.
Tier 3: Syfe Cash+ Enhanced — Accepting Market Risk for Yield
Cash+ Enhanced is Syfe’s newer, higher-yield cash management option. It invests in short-duration bond funds rather than fixed deposits, projecting 3.0% p.a. net of fees as at the latest published figures — more than double the Guaranteed tier.
The tradeoff: capital is not guaranteed here. Bond funds can lose value, even short-duration ones, if credit spreads widen or rates move sharply. There is also, again, no SDIC coverage.
This tier belongs to money with a genuine 12-month-plus horizon — cash you’re comfortable seeing dip slightly in a bad month, in exchange for a materially better yield than tiers 1 and 2.
| Product | Rate (SGD) | SDIC Insured? | Capital Guaranteed? |
|---|---|---|---|
| MariBank savings | 0.88% p.a. base | Yes, to S$100,000 | Yes (deposit) |
| Syfe Cash+ Guaranteed | 1.15-1.30% p.a. | No | Yes (by contract, bank risk) |
| Syfe Cash+ Enhanced | ~3.0% p.a. projected | No | No (bond fund risk) |
| IBKR cash + VWRA | 0% below threshold* | No | No (market risk) |
*IBKR pays no interest on SGD balances below S$14,000 or USD balances below US$10,000. Source: MariBank.sg, Syfe.com, Interactive Brokers Singapore pricing page, September 2026.
Tier 4: IBKR + VWRA — The Growth Overflow
Once tiers 1 to 3 are funded — insured buffer, guaranteed term deposits, and enhanced-yield bond funds — any further overflow can go to work in global equities via Interactive Brokers (IBKR).
The catch here isn’t the equity risk itself; it’s what happens to cash sitting in your IBKR account before you invest it. IBKR pays 0% interest on SGD cash below S$14,000 and only 0.416% p.a. above that. On USD cash, it’s 0% below US$10,000, rising to roughly 3.1% p.a. above that threshold for Pro-tier accounts. Park too much idle cash there and you’re earning nothing while your MariBank and Syfe tiers keep working.
The fix: don’t let cash accumulate in IBKR. Once a lump sum clears your emergency and guaranteed-yield tiers, convert and invest promptly into a globally diversified ETF like VWRA rather than parking it.
A Worked Example: S$500 a Month
Say skipping car ownership with TribeCar frees up S$500 a month. Here’s how the waterfall plays out over the first two years for someone starting from zero:
Months 1-12: All S$500/month goes into MariBank, until the emergency buffer target (say S$6,000, or 6 months of a lean S$1,000 monthly expense) is reached around month 12.
Months 13-24: Buffer is full. New contributions now go into a rolling Syfe Cash+ Guaranteed 3-month ladder, so a tranche matures every quarter and can be redirected if a better rate appears, or a market emergency forces a withdrawal.
Year 3 onward: Once the guaranteed-tier balance reaches a comfortable multiple of near-term expenses, new contributions shift to Cash+ Enhanced for a 12-month-plus horizon, and any true overflow — bonus money, a good month, a one-off saving — goes to IBKR for a VWRA top-up.
The point isn’t the exact dollar thresholds. It’s that the order (insured, then guaranteed, then market-risk yield, then equities) stays fixed even as the amounts grow.
How This Differs From Our Other TribeCar Combos
We’ve covered MariBank and Syfe together before, in the TribeCar + MariBank + Syfe SDIC insurance barbell piece — that article stopped at two platforms and capped MariBank at the old S$75,000 SDIC limit (since raised to S$100,000).
This article adds IBKR as a fourth, genuinely growth-oriented tier, and reframes the whole stack around protection type — insured deposit, contractual guarantee, market-risk yield, full market risk — rather than just an insurance cap. It’s a different mechanic from our first 4-way combo, TribeCar + Trust Bank + GXS + FSMOne’s “floor vs flex” split, which was about where each bank’s bonus interest applies rather than protection tiers.
Get Started
Referral codes for the platforms in this combo:
Related Reading
For more on the individual platforms and other combos, see our TribeCar + GXS + IBKR SGD dead zone guide, our Singapore T-bills 2026 guide for another SDIC-free but government-backed option, and our passive income Singapore guide for the bigger picture on building multiple income streams.
You can also check the current MariBank interest rate breakdown and our TribeCar + Trust Bank + IBKR recycling loop for a different currency-focused mechanic.
Frequently Asked Questions
Is my money safe in Syfe Cash+ if SDIC doesn't cover it?
What is the current SDIC coverage limit in Singapore?
Why does IBKR pay 0% interest on some of my cash?
How much should I keep in MariBank before moving to Syfe?
Is Syfe Cash+ Enhanced riskier than Cash+ Guaranteed?
Do I need all four platforms to use this strategy?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.