Mapletree Industrial Trust (ME8U): How Fed Rate Cuts Boost DPU in 2026
SGX: ME8U | Updated: September 2026 | Pre-FOMC Rate Cut Analysis
Table of Contents
- MIT Overview: Singapore Largest Industrial REIT
- Share Price, Yield and Key Metrics (September 2026)
- DPU History: 12.71c in FY25/26
- How Fed Rate Cuts Boost MIT DPU
- Portfolio Breakdown: 136 Properties Across 3 Markets
- Gearing and Debt Profile
- 2H2026 Outlook: What to Expect from MIT
- Frequently Asked Questions
Mapletree Industrial Trust (SGX: ME8U) is one of Singapore most closely watched S-REITs. It carries a gearing ratio of approximately 37% and paid an annual DPU of 12.71 Singapore cents in FY25/26. With the US Federal Reserve meeting on 17 September 2026, investors want to know how much Fed rate cuts will actually help MIT distributions.
This analysis focuses on that question. MIT sensitivity to interest rate changes, its debt refinancing profile, and what a 25bps or 50bps rate cut means for unitholders are all covered below.
For background on MIT portfolio and investment thesis, see the full MIT investor guide and the MIT 2H2026 DPU outlook.
MIT Overview: Singapore Largest Industrial REIT
Mapletree Industrial Trust is Singapore largest industrial REIT by assets under management. Its portfolio spans S$8.3 billion across 136 properties as at March 2026. The three markets it operates in are Singapore, North America, and Japan.
MIT is managed by Mapletree Investments, a Singapore-based real estate investment manager backed by Temasek Holdings. This institutional backing provides MIT with access to capital markets and a steady deal pipeline.
The REIT portfolio includes flatted factories, business park buildings, data centres, and stack-up industrial buildings in Singapore. In North America, MIT focuses on data centres and light industrial assets. Japan contributes a smaller but stable stream of industrial income.
Data centres are MIT most valuable asset class. They generate stable, long-term income due to high switching costs and mission-critical nature. MIT data centre exposure spanning Singapore and North America has positioned it as a key beneficiary of AI infrastructure demand.
Share Price, Yield and Key Metrics (September 2026)
| Metric | Value | Notes |
|---|---|---|
| Ticker | SGX: ME8U | Listed on SGX Mainboard |
| Share Price (approx.) | S$2.08 | Verify on SGX before investing |
| DPU FY25/26 | 12.71 cents | Down 6.3% YoY |
| Distribution Yield | ~6.2% | At S$2.08 share price |
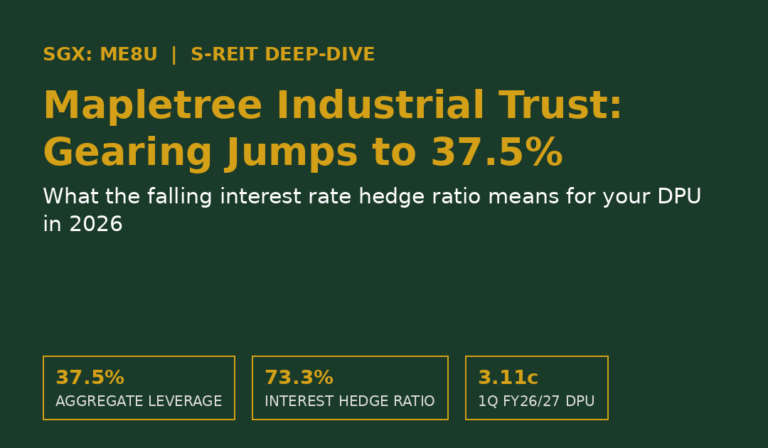
| Gearing Ratio | ~37.5% | Below MAS 50% limit |
| Total AUM | S$8.3 billion | 136 properties across 3 markets |
| Distribution Frequency | Semi-annual | 1H paid Nov, 2H paid May |
Data sourced from MIT IR and public filings. Share price is approximate. Always verify on SGX before making investment decisions.
DPU History: 12.71c in FY25/26
MIT has historically maintained a stable distribution of around 13 cents per unit per year. FY25/26 saw a decline to 12.71c due to lease non-renewals in North America and a weaker US dollar against the Singapore dollar.
| Financial Year | 1H DPU | 2H DPU | Full Year DPU | YoY Change |
|---|---|---|---|---|
| FY22/23 | 6.80c | 6.80c | 13.60c | — |
| FY23/24 | 6.81c | 6.81c | 13.62c | +0.1% |
| FY24/25 | 6.76c | 6.80c | 13.56c | -0.4% |
| FY25/26 | 6.34c | 6.37c | 12.71c | -6.3% |
| FY26/27E | 6.20-6.40c | 6.20-6.40c | ~12.40-12.80c | Flat/recovery |
E = estimated. Historical data from MIT annual reports. FY26/27 estimates are projections, not financial advice.

How Fed Rate Cuts Boost MIT DPU
MIT borrows in both Singapore dollars and US dollars. A significant portion of its debt is floating-rate or due for refinancing within the next two to three years. This means Fed rate cuts directly reduce MIT interest expense.
MIT own disclosures indicate that a 50 basis point change in interest rates results in approximately a 0.04 cent per annum change in DPU. That translates to roughly 0.02 cents for each 25bps move.
Rate Cut Scenario Analysis
| Fed Rate Cut Scenario | Estimated DPU Uplift | Annualised DPU Range |
|---|---|---|
| No cut (base) | 0c | ~12.40-12.55c |
| 25bps cut (Sep 2026) | +0.02c | ~12.42-12.57c |
| 50bps cut (Sep 2026) | +0.04c | ~12.44-12.59c |
| 100bps cumulative cuts | +0.08c | ~12.48-12.63c |
The direct DPU uplift from rate cuts is modest per cut. The more significant impact is on valuation. Lower rates reduce the discount rate used to value REIT portfolios. This generally leads to cap rate compression, which increases the value of MIT 136 properties and its NAV per unit.
A higher NAV narrows the discount at which MIT trades relative to book value. A rate-cut environment reduces this discount over time and typically re-rates REIT share prices upward.
Rate cuts also reduce the refinancing cost of MIT maturing debt. As MIT rolls over fixed-rate loans at lower rates over 2026 and 2027, the savings compound. This is where the longer-term structural benefit lies.
Currency is also a factor. A weaker US dollar reduces the SGD-equivalent DPU from North American assets. Management uses hedging to manage this exposure, but it remains a watch item for investors tracking USD/SGD movement.
For a comparison of MIT versus Keppel DC REIT on the data centre angle, see the MIT vs Keppel DC REIT comparison.
Portfolio Breakdown: 136 Properties Across 3 Markets
MIT portfolio is diversified across three geographies. Singapore remains the core market, contributing the largest share of AUM and income. North America adds data centre exposure and US dollar-denominated income. Japan provides a smaller but stable stream of industrial income.
| Geography | Key Asset Types | Notes |
|---|---|---|
| Singapore | Data centres, flatted factories, business parks | Core market, highest occupancy |
| North America | Data centres, light industrial | USD income; lease non-renewals impacted FY25/26 DPU |
| Japan | Industrial properties | Smaller contribution; JPY-denominated income |
The North American portfolio has faced headwinds. Lease non-renewals in FY25/26 reduced occupancy and income. Management is actively backfilling vacant space. The data centre assets in North America remain fully occupied.
Singapore industrial market remains tight. Flatted factory and business park occupancy rates are high. MIT Singapore assets benefit from limited new supply and steady demand from manufacturing and technology tenants.
MIT divested approximately S$550.6 million of properties in FY25/26 and issued S$300 million in perpetual securities. These moves reshaped the portfolio and reduced gearing. The divestment proceeds were not fully replaced with higher-yielding assets, which contributed to the DPU decline.
Gearing and Debt Profile
MIT gearing stood at approximately 37.5% as of FY25/26. Some sources indicate this has been reduced toward 34% following the divestment programme and perpetual securities issuance. MIT operates well within MAS 50% gearing ceiling.
The perpetual securities issuance of S$300 million is classified as equity under accounting standards. This reduces reported gearing and improves MIT financial flexibility. However, perpetual distributions must be paid before unitholders receive their DPU, so investors should monitor total cost of capital.
MIT weighted average debt maturity and hedging ratio are key metrics for rate cut analysis. A higher proportion of floating-rate debt means MIT benefits more quickly when rates fall. Long-dated fixed-rate debt insulates MIT but delays the benefit of lower rates.
Management typically provides a sensitivity disclosure in its quarterly results. The 50bps equals 0.04c DPU figure cited here comes from this standard management disclosure. Investors should look for updated sensitivity figures in the next quarterly results.
2H2026 Outlook: What to Expect from MIT
MIT 1H FY26/27 DPU (payable November 2026) is expected in the range of 6.20 to 6.40 cents. This would be broadly flat to the 6.34c paid in 1H FY25/26. The key swing factors are North American occupancy recovery and USD/SGD exchange rates.
The FOMC meeting on 17 September 2026 is a near-term catalyst. A 25bps or 50bps cut reduces MIT floating-rate borrowing costs from the next payment cycle onward. The quantum per cut is small, but the direction matters for investor sentiment and NAV re-rating.
AI-driven data centre demand continues to support MIT premium assets in this segment. Data centres account for a meaningful share of MIT AUM. This structural tailwind is independent of the rate cycle and provides a growth avenue beyond traditional industrial income.
Investors should watch three things in the next 6 months: occupancy recovery in North America, debt refinancing outcomes, and any acquisition announcements using FY25/26 divestment proceeds. Management has indicated a focus on strengthening the core portfolio.
For the full DPU outlook analysis, see the detailed MIT 2H2026 DPU forecast and the MIT price target 2026 analysis.
Frequently Asked Questions
]
What is the DPU of Mapletree Industrial Trust in 2026?
How do Fed rate cuts affect Mapletree Industrial Trust?
Is Mapletree Industrial Trust a good investment in 2026?
What is MIT gearing ratio in 2026?
When does MIT pay its next distribution?
Start Investing in Singapore REITs
Build your S-REIT portfolio through a fee-efficient platform. Singapore investors can access MIT and other S-REITs through these platforms with exclusive referral bonuses.
]
Referral links may earn The Kopi Notes a commission at no extra cost to you. This is not financial advice. All investment decisions should be made based on your own research and risk tolerance.
]
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.