UOB Fixed Deposit Rate Singapore (October 2026): Is a Digital Bank Better?
Updated: 11 October 2026 · 9 min read · Category: Digital Banks
UOB’s promotional fixed deposit rate in October 2026 reaches up to 1.70% p.a. for 12 months (valid 23 September to 31 October 2026), requiring at least S$10,000 in fresh funds. However, digital banks like Trust Bank (2.40% p.a.) and MariBank (up to 2.88% p.a.) currently offer significantly higher returns with no lock-in period — making them worth serious consideration before you commit.
Not financial advice. All figures are for educational reference only. Data verified as at 11 October 2026 from official bank websites.
What Is a UOB Fixed Deposit?
A fixed deposit (FD) — also called a time deposit — is a savings product where you lock a lump sum with a bank for a fixed period in exchange for a guaranteed interest rate. Unlike a regular savings account, you generally cannot withdraw your funds before the tenure ends without a penalty.
UOB (United Overseas Bank) is one of Singapore’s three major local banks, alongside DBS and OCBC. Its SGD fixed deposit is a popular choice among conservative savers who prioritise capital safety and predictable returns.
Core features of a UOB Fixed Deposit:
- Principal protected — your full deposit is returned at maturity
- SDIC insured — up to S$75,000 per depositor per institution under the Singapore Deposit Insurance Corporation
- Guaranteed rate — the rate is locked in at the time of placement
- Minimum deposit — S$10,000 for promotional rates; S$1,000 for standard board rates
When evaluating whether a UOB FD is the right choice, the key question is simple: can you get a better return elsewhere, at comparable or lower risk, without locking up your cash for months? In 2026, the answer often points to digital banks.
If you’re also thinking about longer-term savings instruments, you might want to explore our Singapore Savings Bonds guide and Singapore T-bills 2026 guide as complementary options.
UOB Fixed Deposit Rates — October 2026
UOB is currently running a promotional campaign valid from 23 September to 31 October 2026. To qualify for promotional rates, your deposit must use fresh funds — money not currently held with UOB. Internal UOB transfers do not qualify.
| Tenure | Promotional Rate | Standard Board Rate | Min. Deposit |
|---|---|---|---|
| 6 months | 1.60% p.a. | 0.30% p.a. | S$10,000 |
| 10 months | 1.65% p.a. | 0.45% p.a. | S$10,000 |
| 12 months | 1.70% p.a. | 1.00% p.a. | S$10,000 |
Source: UOB Singapore (uob.com.sg), promotional rates valid 23 Sep – 31 Oct 2026. Fresh funds only.
A few practical points worth noting. First, the gap between promotional and standard board rates is enormous — particularly at 6 months, where the standard rate is just 0.30% versus 1.60% on promotion. This means if you miss the promotional window or roll over without checking, your rate could drop dramatically. Second, interest is credited at maturity, not monthly — so for liquidity purposes, you effectively earn nothing until your tenure ends.
Example: S$50,000 in a UOB 12-month FD at 1.70% earns S$850 at maturity. The same S$50,000 in a Trust Bank savings account at 2.40% earns S$1,200 over a year — with the flexibility to withdraw at any time.
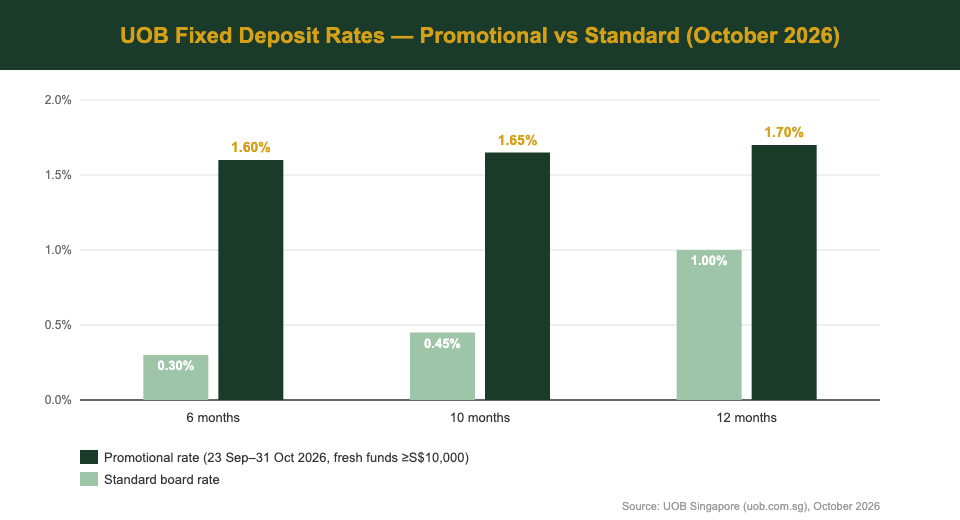
UOB promotional FD rates vs standard board rates by tenure. The uplift at 6 months is especially pronounced (0.30% → 1.60%).
UOB FD vs Digital Bank Savings: A Direct Comparison
Since MAS granted full digital bank licences to GXS Bank (backed by Grab and Singtel), MariBank (Sea Limited), and Trust Bank (Standard Chartered and FairPrice Group), the savings rate landscape in Singapore has shifted significantly. These banks compete aggressively for deposits — and in October 2026, all three offer savings rates that beat UOB’s promotional FD.
| Bank / Product | Interest Rate | Lock-in | Min. Balance | SDIC Insured |
|---|---|---|---|---|
| UOB FD 12M (Promo) | 1.70% p.a. | 12 months | S$10,000 | ✅ |
| OCBC FD 12M | Up to 1.65% p.a. | 12 months | S$20,000 | ✅ |
| GXS Bank Boost Pockets | Up to 1.75% p.a.* | None | S$0 | ✅ |
| Trust Bank Savings | 2.40% p.a. | None | S$0 | ✅ |
| MariBank Savings | Up to 2.88% p.a.† | None | S$0 | ✅ |
*GXS Boost Pockets rate subject to eligibility conditions. †MariBank up to 2.88% p.a. for ShopeeVIP members or new customers (first 30 days); base rate 0.88% p.a. Source: Official bank websites, October 2026.
The headline difference is striking: Trust Bank offers 2.40% with zero lock-in, compared to UOB’s 1.70% that requires tying up S$10,000 for a full year. For every S$50,000 placed, Trust Bank returns S$350 more per year — and you keep full liquidity throughout.
To open a Trust Bank account and get a sign-up bonus, use referral code HTWYQP95 during registration.
MariBank’s headline rate of up to 2.88% p.a. applies to ShopeeVIP members or new customers in their first 30 days. The base rate is 0.88% p.a. — so the headline is conditional. Use referral code 2DCT80WQ when signing up for MariBank for any applicable bonus.
GXS Bank’s Boost Pockets offer up to 1.75% p.a. with no lock-in — slightly ahead of UOB’s promo rate, and with flexibility. Sign up with referral code YONG477 for GXS Bank.
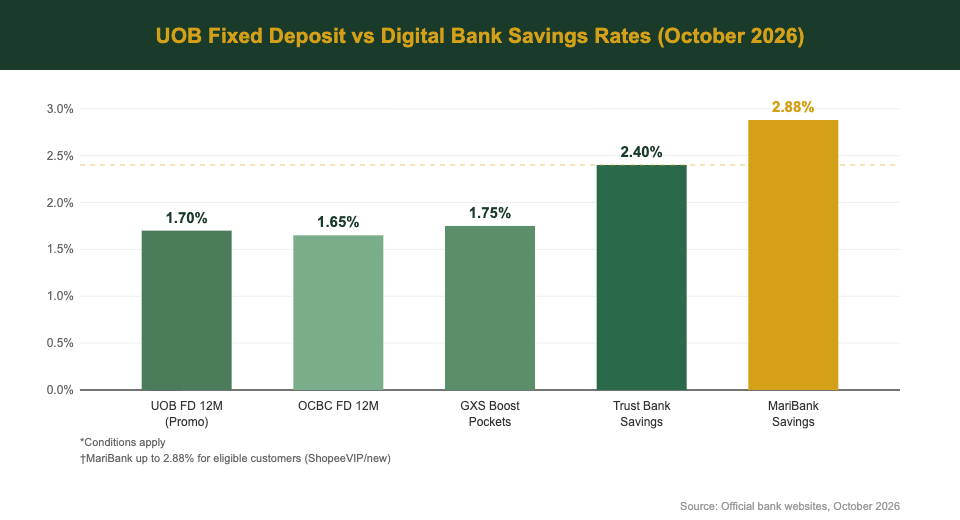
Digital bank savings rates in Singapore clearly outpace UOB’s promotional FD rate as at October 2026.
Key Differences: Flexibility, Safety and Conditions
Beyond the headline rate, there are structural differences between UOB FDs and digital bank savings accounts that matter for how you manage your money.
Lock-in vs Flexibility
A UOB FD locks your funds for the full tenure — 6, 10, or 12 months. Early withdrawal is possible but typically results in forfeiting some or all accrued interest. This matters if an unexpected expense arises (medical bills, home repair, travel) and your funds are tied up. Digital bank savings accounts let you withdraw anytime with no penalty.
SDIC Insurance
All MAS-licensed banks in Singapore — including UOB, MariBank, GXS Bank, and Trust Bank — are covered by the Singapore Deposit Insurance Corporation (SDIC) for up to S$75,000 per depositor per institution. This means digital bank deposits carry the same depositor protection as traditional bank fixed deposits. If safety is your primary concern, digital banks are equally safe for amounts under S$75,000.
Minimum Deposit
UOB’s promotional rate requires S$10,000 in fresh funds. Digital bank savings accounts typically have no minimum — you can open a Trust Bank or MariBank account and start earning 2.40%+ on any amount from day one. This makes digital banks more accessible for savers with smaller balances.
Rate Conditions
UOB’s promotional rate is simple: place S$10,000 or more in fresh funds and you earn the rate, no other hoops. Some digital banks have conditions (MariBank’s highest rate requires ShopeeVIP status or being a new customer). Trust Bank’s 2.40% is available to all customers with no additional requirements, making it arguably the cleanest comparison.
If you want to understand how to best deploy your savings for long-term goals, our Singapore retirement calculator can help you model the impact of different savings rates on your retirement corpus.
Who Should Still Choose a UOB Fixed Deposit?
Despite offering a lower rate than digital banks, there are scenarios where a UOB FD might still make sense:
- You already bank with UOB and want simplicity. If your salary comes into a UOB account and you have fresh funds arriving (e.g., from selling an asset, receiving a bonus), a UOB FD is frictionless to set up within your existing app.
- You want iron-clad certainty that you won’t touch the money. For savers who struggle with self-discipline around spending, the lock-in mechanism of an FD can act as a commitment device. Digital savings accounts are too easy to withdraw from.
- You want to diversify across institutions. If you already have S$75,000 (the SDIC cap) in a digital bank, placing additional funds in a UOB FD makes sense from a deposit insurance perspective.
- You’re parking short-term cash (6 months) with near certainty you won’t need it. If you have a known large expense in 6 months (e.g., paying a home renovation balance), a UOB 6-month FD at 1.60% earns more than a standard savings account while your funds are parked.
But for most Singapore savers who want to maximise returns on their savings with full flexibility, the rate gap is difficult to justify in 2026.
If you are considering broader investment options beyond savings, our CPF investment strategy guide covers how to make your CPF monies work harder alongside your savings.
Who Should Choose a Digital Bank Savings Account?
Digital bank savings accounts in Singapore are worth considering for the majority of savers, particularly those who value both rate and flexibility:
- Savers with less than S$10,000. UOB’s promotional rate requires S$10,000 minimum. Trust Bank and MariBank have no minimum — you earn 2.40% (Trust Bank) from dollar one.
- Anyone who values liquidity. Life is unpredictable. A digital savings account lets you access your funds same-day, without any penalty or rate sacrifice.
- Those wanting a higher return without complexity. Trust Bank’s 2.40% p.a. is unconditional and available to all customers — no minimum spend, no tiered structure, no qualifying criteria to navigate.
- Savers building an emergency fund. Emergency funds by definition should be liquid. Locking 3-6 months of expenses in a UOB FD defeats the purpose of an emergency fund. A digital bank savings account gives you high returns while keeping the money accessible.
It’s also worth noting that you don’t have to choose just one: many Singapore savers use a digital bank for their accessible savings and an FD or Singapore T-bills for cash they genuinely do not need for 6-12 months. Splitting your savings gives you both rate optimisation and flexibility.
How to Open a UOB Fixed Deposit
If you’ve decided a UOB FD is right for your situation, here’s how to place one efficiently:
- Log in to UOB TMRW or UOB Personal Internet Banking (PIB) on your mobile app or browser.
- Navigate to Deposits → Fixed Deposit in the main menu.
- Select your currency (SGD for the promotional rates listed above) and source account.
- Choose your tenure — 6, 10, or 12 months for the promotional rates. Check that the promotion is still active at the time of placement.
- Enter the amount — minimum S$10,000 for promotional rates, and ensure these are fresh funds not already held with UOB.
- Review and confirm — you’ll see the interest amount and maturity date before confirming.
- At maturity, review your options — UOB will typically auto-renew at the prevailing board rate (which may be much lower than the promo rate). Make a diary note to actively review and re-place at maturity.
For comparison, opening a Trust Bank or MariBank account takes 5-10 minutes via your phone. Trust Bank requires a National Registration Identity Card (NRIC) and is available to Singapore citizens and PRs. Use referral code HTWYQP95 for Trust Bank or 2DCT80WQ for MariBank for any applicable bonus.
Once you have both accounts set up, you can also use the Singapore retirement calculator to model how different interest rates compound your savings over time.
Frequently Asked Questions
What is UOB's best fixed deposit rate in October 2026?
UOB’s best fixed deposit rate in October 2026 is 1.70% p.a. for a 12-month tenure, available under the promotional campaign running from 23 September to 31 October 2026. A minimum of S$10,000 in fresh funds (not currently held with UOB) is required. For 10 months the rate is 1.65% p.a., and for 6 months it is 1.60% p.a.
How does UOB's fixed deposit rate compare to digital banks?
UOB’s best promotional FD rate of 1.70% p.a. is lower than the savings rates offered by Singapore’s digital banks as at October 2026. Trust Bank offers 2.40% p.a. with no lock-in; MariBank offers up to 2.88% p.a. for eligible customers; GXS Bank’s Boost Pockets offer up to 1.75% p.a. The key difference is that digital bank savings accounts have no minimum deposit and no lock-in period.
Is a UOB fixed deposit safe? Is it SDIC insured?
Yes, UOB fixed deposits are very safe. UOB is a MAS-licensed bank in Singapore, and deposits are insured by the Singapore Deposit Insurance Corporation (SDIC) for up to S$75,000 per depositor per institution. Principal protection means you receive your full deposit back at maturity, regardless of market conditions. Singapore’s digital banks (MariBank, GXS Bank, Trust Bank) are also MAS-licensed and SDIC-insured to the same limit.
What happens if I withdraw my UOB fixed deposit early?
If you need to break your UOB FD before the tenure ends, you can request an early withdrawal, but you will typically forfeit some or all of the interest accrued. UOB’s exact early withdrawal policy may vary — it’s best to check directly with UOB or via TMRW before placing your deposit if early access is a possibility. This is one of the key advantages digital bank savings accounts have over FDs: you can withdraw anytime with no penalty.
Which is better: UOB FD or Trust Bank savings account?
For most Singapore savers in October 2026, Trust Bank’s savings account at 2.40% p.a. offers a better deal than UOB’s 12-month FD at 1.70% p.a. You earn 0.70 percentage points more per year, with full liquidity and no minimum deposit. On S$50,000, that’s an extra S$350 per year. The main case for UOB FD over Trust Bank is if you want a formal lock-in mechanism (to prevent yourself spending the money) or if you’re diversifying beyond the S$75,000 SDIC cap with a different institution.
Do I need to be a UOB customer to open a fixed deposit?
No, you do not need to be an existing UOB customer to open a fixed deposit. You can open a UOB FD as a new customer by visiting a UOB branch or through online banking after completing account opening. However, fresh funds are required for the promotional rate — so you cannot simply transfer from an existing UOB savings account and qualify for the promo.
Ready to Get a Better Rate on Your Savings?
While UOB’s promotional FD rate of 1.70% p.a. is reasonable for a traditional bank in October 2026, digital banks are offering meaningfully higher returns without any lock-in. Here’s where to start:
- Trust Bank — 2.40% p.a. savings, no minimum, no lock-in. Use referral code HTWYQP95 to sign up.
- MariBank — Up to 2.88% p.a. for eligible customers. Use referral code 2DCT80WQ to sign up.
- GXS Bank — Boost Pockets up to 1.75% p.a. Use referral code YONG477 to sign up.
This article is for informational purposes only and does not constitute financial advice. Rates are subject to change. Always verify current rates directly with the bank before placing any deposit. The Kopi Notes may receive a referral benefit when you sign up using the codes above.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.