TribeCar + Trust Bank + Syfe + IBKR: The Rate Certainty Ladder (2026)
Three “high rate” destinations for your freed-up TribeCar savings — but only one of them guarantees the number you see. Here’s how to rank Trust Bank, Syfe Cash+ Guaranteed, and IBKR by certainty, not just headline rate.
Not financial advice. All rates as at September 2026, verified via WebSearch cross-check. Rates change — verify current figures on each platform before acting.
Skipping car ownership with TribeCar frees up S$1,000–S$2,000 a month that would otherwise go to COE depreciation, loan interest, insurance, and parking. The usual question is where that freed-up cash should go — but most comparisons only look at the headline percentage. That’s a mistake, because not every “high rate” is equally likely to actually land in your account.
This guide ranks three very different platforms — Trust Bank, Syfe Cash+ Guaranteed, and Interactive Brokers (IBKR) — not by rate size, but by rate certainty type: is the number conditional on your behaviour, contractually fixed once you commit, or dependent on crossing a balance threshold?
The Rate Certainty Mechanic
Every “up to X% p.a.” headline hides a different kind of condition. This guide sorts the three platforms into three certainty types:
- Behavioural-conditional (Trust Bank): the top rate only applies if you keep meeting monthly criteria — salary credit, card spend, PayNow transactions. Miss a month and you fall back to the base rate.
- Contractual-fixed (Syfe Cash+ Guaranteed): once you lock in a term, the rate is fixed for that term regardless of what you do afterwards — closer to a fixed deposit than a bonus-tiered savings account.
- Threshold-binary (IBKR): you earn nothing at all below a specific balance line, then the rate switches on and scales with your account’s net asset value (NAV).
None of these is “better” in isolation — they suit different amounts of freed-up TribeCar cash at different stages.
Trust Bank: Behavioural-Conditional
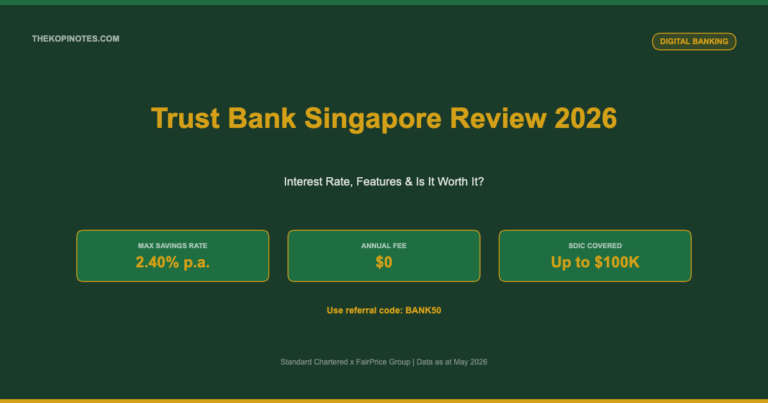
Trust Bank‘s savings account advertises up to 2.40% p.a. on balances up to S$1.2 million — but that headline number requires meeting a mix of monthly conditions (salary GIRO credit, a minimum number of card spends, and PayNow transactions). Base rate with none of those conditions met is just 0.05% p.a.
In practice, most freed-up-TribeCar-savings users realistically clear a smaller combination — commonly cited as landing around 0.75–0.85% p.a. “achievable” once you factor in only the easy-to-hit scoops, not the full stack. Trust Bank now lets you switch between plans monthly in-app, so this can be actively managed, but the certainty of hitting the top rate every single month is genuinely conditional on your spending behaviour that month.
Best for: the first tranche of freed-up cash, where you’re already paying for daily expenses on a card and can route that spend through Trust Bank’s criteria without extra effort.
Syfe Cash+ Guaranteed: Contractual-Fixed
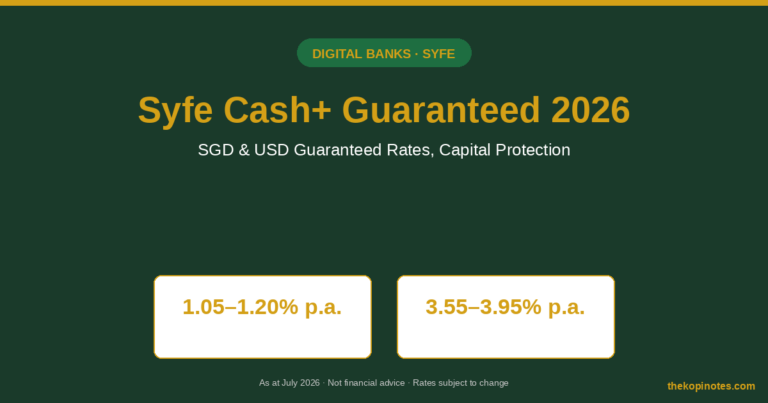
Syfe Cash+ Guaranteed works differently: your money is placed into fixed deposits with MAS-regulated banks for a chosen term, and the rate is locked at purchase — currently around 1.05% p.a. for 1-month, 1.15% p.a. for 3-month, and 1.25–1.30% p.a. for 6-month SGD terms (USD terms pay meaningfully more, currently in the 3.6–4.1% p.a. range).
There’s no monthly condition to track and no risk of falling to a lower base rate mid-term — the number you see when you commit is the number you get at maturity, subject only to the underlying bank’s own risk (not SDIC-insured directly, but spread across MAS-regulated institutions). This makes it a genuinely contractual rate rather than a behavioural one.
Best for: the second tranche — cash you’re confident you won’t need for the length of the term, where you’d rather lock in certainty than chase a conditional bonus.
IBKR: Threshold-Binary
Interactive Brokers (IBKR) pays 0% interest on SGD and USD cash balances below a specific line — broadly the SGD-equivalent of US$10,000 per currency held. Below that line, freed-up TribeCar savings parked at IBKR earn precisely nothing. Above it, the rate switches on and scales up further as your account’s total net asset value (NAV) approaches US$100,000, where SGD balances can earn up to roughly 0.2% p.a. and USD balances considerably more.
This is a binary threshold, not a gradient: there is no partial credit for being close to the line. For most TribeCar-savings routing plans, IBKR only becomes relevant as the final overflow destination once MariBank, Trust Bank, GXS, or Syfe tranches are already topped up and the leftover has crossed the threshold — typically once it’s being used for actual investing (VWRA, individual equities) rather than sitting as idle cash.
Best for: overflow only, once your balance is large enough to clear the threshold — or as a pure investing account where the “interest” question is secondary to the low commission and FX fee structure.
Recommended Routing Order
- Trust Bank first — route your everyday card spend and salary credit through Trust Bank’s criteria to realistically capture the achievable ~0.75–0.85% p.a. tier on your emergency-fund-sized balance, since you’re already spending that money anyway.
- Syfe Cash+ Guaranteed second — once you have a clear sense of how long a chunk of freed-up TribeCar savings can sit untouched, lock it into a 1, 3, or 6-month Guaranteed term for a contractual rate with zero behavioural risk.
- IBKR last, as overflow — only once cumulative freed-up savings clear the SGD/USD threshold does IBKR make sense, at which point it’s usually functioning as an investing account (e.g. a globally diversified ETF like VWRA) rather than a place to park idle cash.
This order ranks destinations by how sure you can be of the number you’re being quoted — not by which headline percentage looks biggest on the page.
Full Comparison Table
| Platform | Certainty Type | Headline Rate | Realistic Rate |
|---|---|---|---|
| Trust Bank Flex | Behavioural-conditional | Up to 2.40% p.a. | ~0.75–0.85% p.a. achievable |
| Syfe Cash+ Guaranteed (SGD) | Contractual-fixed | 1.05–1.30% p.a. by term | Same — locked at purchase |
| IBKR (SGD/USD cash) | Threshold-binary | 0% below threshold, scales to NAV $100k | 0% until ~US$10k-equivalent cleared |
Rates verified via WebSearch cross-check, September 2026. All figures are indicative and change without notice — confirm on each platform before committing funds.
Start With the TribeCar Savings
Before any of this cash exists, it starts with skipping car ownership. New TribeCar members get S$10 in free credits with a valid referral code:
Other TribeCar Routing Combos
This is one of many ways to route freed-up TribeCar savings, each ranking the same handful of platforms by a different mechanic:
- TribeCar + Trust Bank + Endowus + IBKR — achievable-rate funding ladder
- TribeCar + MariBank + Syfe + IBKR — insured-first cash waterfall
- TribeCar + MariBank + Trust Bank + FSMOne — zero-fee cash buffer
- TribeCar + GXS + IBKR — the SGD dead-zone explainer
Use the one that matches how much cash you’re routing and how soon you’ll need it back.
Frequently Asked Questions
Why does Trust Bank advertise 2.40% but most people don't earn that?
The 2.40% p.a. top tier requires meeting a specific mix of monthly conditions — salary GIRO credit, a minimum number of card transactions, and PayNow payments. Most users realistically hit only some of these each month, landing closer to 0.75–0.85% p.a. Miss all the conditions and you fall to the 0.05% p.a. base rate. This is why it’s classified here as “behavioural-conditional” rather than guaranteed.
Is Syfe Cash+ Guaranteed actually guaranteed?
The rate is fixed for the term once you commit — that part is contractual. The underlying capital sits in fixed deposits with MAS-regulated banks, so returns depend on the health of those banks rather than Syfe itself; it is not SDIC-insured the way a direct bank deposit is. It’s “guaranteed” in the sense of a locked interest rate, not government-backed insurance.
Why does IBKR pay 0% interest on some balances?
IBKR only pays interest on cash balances above a set threshold, roughly the SGD-equivalent of US$10,000 per currency. Below that line, the balance earns nothing at all — there’s no partial or scaled rate for smaller amounts. This threshold exists per currency held, so SGD and USD balances are each measured against their own line.
Should I route all my TribeCar savings to one platform?
Generally no. Splitting across a behavioural-conditional account (Trust Bank), a contractual-fixed term (Syfe Cash+ Guaranteed), and an overflow investing account (IBKR) balances certainty, liquidity, and growth rather than concentrating all your savings under one rate structure.
Where does the TribeCar savings actually come from?
Owning a mid-range car in Singapore typically costs S$1,800–S$2,500/month once COE, loan interest, insurance, road tax, petrol, and parking are added up. Regular TribeCar users spending S$400–S$600/month on car-sharing instead can free up S$1,000+/month, which is the pool of cash this guide is routing.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.